


EN
Independence Realty Trust (IRT) Faces Activist Pressure, Is It Still 19% Undervalued?
Irenic Capital’s push at Independence Realty Trust (IRT) puts a major decision on the table. The investor wants the board to drop the planned US$8.1b Centerspace deal and instead explore a sale of the REIT.
Independence Realty Trust’s latest move comes after a choppy year for the stock, with the share price down about 15% year to date and the 90 day share price return falling 10.3%, even as the 3 year total shareholder return is up 28.3% and the 5 year total shareholder return is down 29.5%.
Recent quarterly earnings on 2 November 2026 set the backdrop. Higher revenue and net income figures were reported, followed days later by lowered full year earnings guidance and now Irenic’s call for a sale. Together, these factors help explain why sentiment around the US$14.96 share price has been shifting between renewed interest and concern about future risk.
Compare how Independence Realty Trust’s situation stacks up against other real estate names under pressure by scanning our hand picked 30 resilient stocks with low risk scores for potential alternatives with sturdier profiles.
For investors watching Independence Realty Trust at about US$15 and facing an activist pushing for a sale, the immediate fork in the road is clear. Buy into the uncertainty now, or wait for a cleaner entry after the dust settles?
Most Popular Narrative: 19% Undervalued
On the Simply Wall St analyst consensus Narrative, Independence Realty Trust’s fair value sits at $18.46 against a last close of $14.96. This frames Irenic’s sale push against a backdrop of modeled upside based on detailed earnings and cash flow forecasts.
The pending all stock merger with Centerspace is expected to add about 10,500 units and roughly US$24m of annualized synergies. Management guides to around 5% accretion to 2027 Core FFO per share on a leverage neutral basis, which creates potential for higher revenue scale, lower G&A as a share of assets and stronger earnings power.
See why 0 investors see Independence Realty Trust as 19% undervalued.
Result: Fair Value of $18.46 (UNDERVALUED)
Still, the Irenic Capital thesis runs into two clear pressure points: potential multifamily oversupply in key Sun Belt cities and any setback to the Centerspace merger closing.
Find out about the key risks to this Independence Realty Trust narrative.
Another View: Multiples Paint A Tougher Picture For Independence Realty Trust
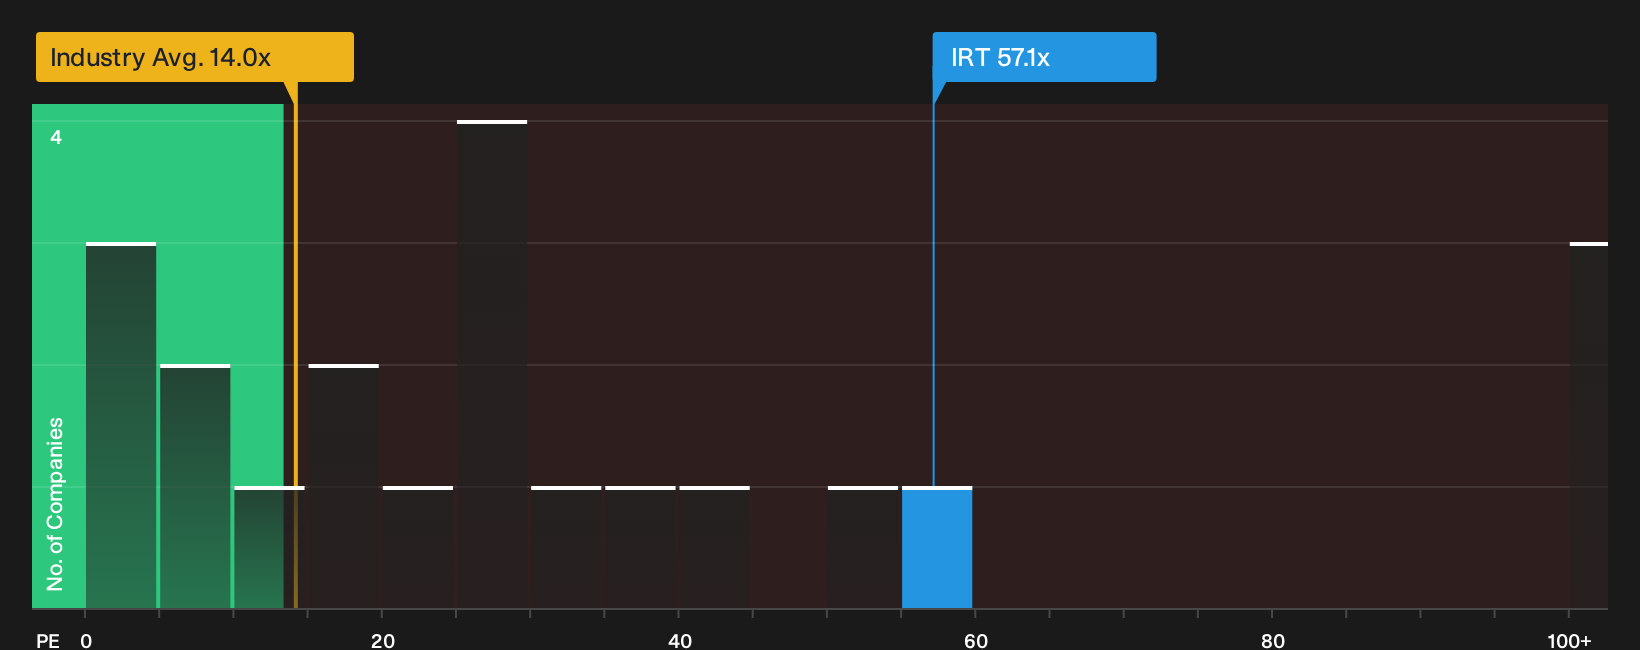
There is a very different message when looking at Independence Realty Trust through its P/E. The shares trade on roughly 57.1x earnings, compared with 14x for global Residential REITs and a fair ratio of 26.5x. That gap suggests meaningful valuation risk if sentiment weakens.
For a closer look at how this pricing stacks up against peers and the fair ratio that the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Independence Realty Trust is clearly split, with both pressure points and bright spots on the table today. Act while the information is fresh and weigh both sides by reviewing the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Independence Realty Trust?
If Independence Realty Trust has your attention, use that momentum and line up a few fresh watchlist candidates using targeted screeners built for different styles.
- Target resilient potential by reviewing companies with sturdier balance sheets and cash profiles through our curated list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced opportunities by scanning the 34 high quality undervalued stocks tailored to highlight quality businesses trading below their estimated worth.
- Stack your income options by checking the 6 dividend fortresses focused on higher yielding stocks that aim to pair stability with meaningful payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com