


EN
How $500 Million Buyback At PTC Therapeutics (PTCT) Has Changed Its Investment Story
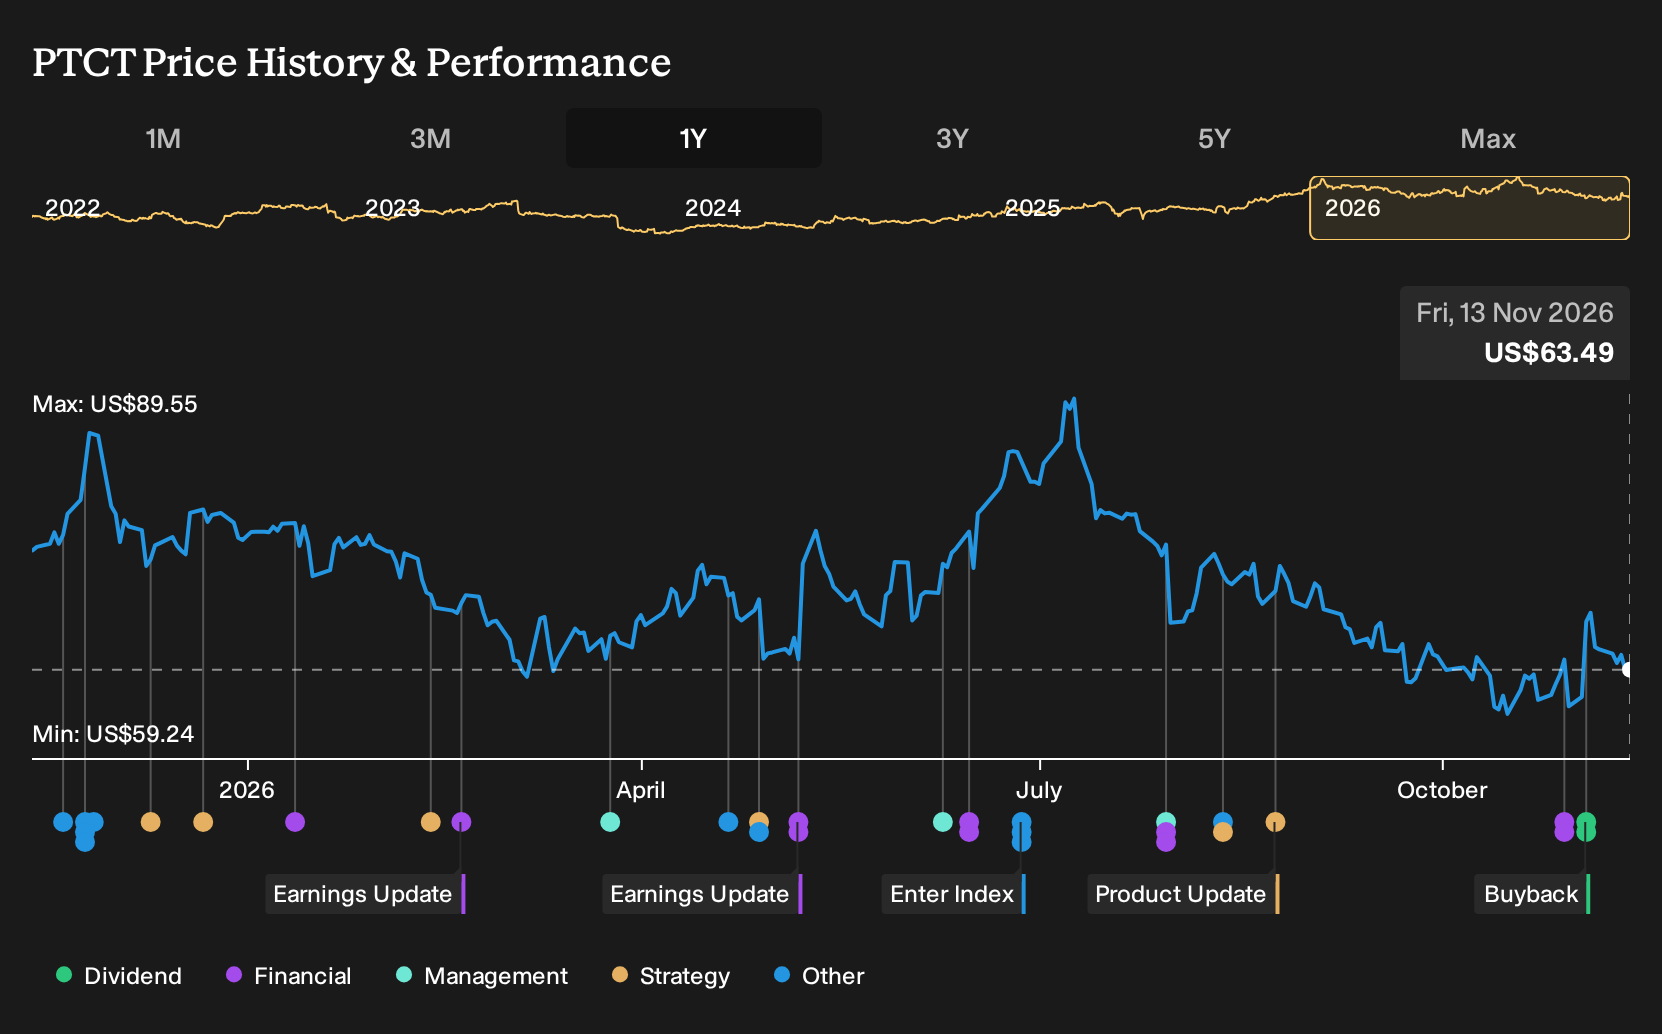
- PTC Therapeutics announced in early November 2026 that its Board authorized a share repurchase program of up to US$500 million of common stock, providing flexibility to reduce the share count over time.
- This buyback capacity, set against a rare disease portfolio backed by over US$2.1 billion in cash and late-stage assets such as ST 920, could influence how investors weigh dilution risk and future capital allocation choices.
- This article examines how PTC Therapeutics' investment narrative is affected by this US$500 million repurchase authorization and its rare disease ambitions.
PTC Therapeutics Investment Narrative Recap
To own PTC Therapeutics, you need to believe the rare disease engine, especially Sephience and ST 920, can more than offset pressure in the Duchenne muscular dystrophy portfolio and eventually move the group into sustainable profitability. The analyst consensus Narrative on Simply Wall St leans on Sephience uptake, the ST 920 Fabry program and a broad pipeline to do that heavy lifting.
The fresh US$500 million repurchase authorization does not change those operational swing factors. In the short term, progress on the rolling ST 920 BLA and maintaining growth in Sephience patient starts look like the key potential catalysts. The main risk remains that DMD revenue headwinds outpace the ramp of newer treatments.
The most relevant backdrop to the buyback is PTC Therapeutics' balance sheet and late stage pipeline. Analysts highlight a cash position of about US$2.1b alongside financing moves that pushed most 2026 convertible notes into 2031 zero coupon paper. That combination supports the capacity to commit capital to both development and repurchases.
If ST 920 clears regulatory hurdles and Sephience continues to see broader PKU adoption, those products could help absorb the strain from Emflaza generics and lumpier Translarna orders. If uptake underwhelms, the firm would be relying more heavily on its cash pile and cost control while it is still reporting losses of roughly US$106 million.
PTC Therapeutics' narrative projects US$1.7b revenue and US$380.7 million earnings by 2029. This implies 14.8% yearly revenue growth and an earnings swing of about US$486.7 million from the current loss of US$106.0 million.
Uncover why PTC Therapeutics' fair value indicates a 54% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view suggests the real swing factor for PTC Therapeutics is Sephience slowing as easy PKU wins fade. Those bearish analysts were only modeling revenue of about US$1.4b and earnings of roughly US$180.2 million by 2029 before this US$500 million buyback news. Their story is therefore far more cautious. Analyst opinions can differ widely, so it can help to compare several narratives and decide which assumptions feel closer to how you see the business.
Explore 2 other PTC Therapeutics fair value estimates, including one that suggests it could be worth just $97.80!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your PTC Therapeutics research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PTC Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PTC Therapeutics' overall financial health at a glance.
Looking for more investment ideas beyond PTC Therapeutics?
Once the PTC Therapeutics story is clear in your mind, it can help to compare it with other potential opportunities that fit different risk profiles and income goals. The Simply Wall St Screener lets you jump straight into shortlists that match what you care about most.
- If you want potential value ideas backed by solid fundamentals, start with a focused set of 34 high quality undervalued stocks that already clear some basic quality hurdles.
- If balance sheet strength matters to your sleep at night, filter for companies on our list of solid balance sheet and fundamentals (24 results) and see which ones merit a deeper look.
- If you are building an income focused portfolio, review a curated group of 6 dividend fortresses that combine higher yields with an emphasis on resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com