


EN
Did Clinical Study Results Just Shift BioGaia's (OM:BIOG B) Investment Narrative?
- BioGaia reported past clinical data for its Protectis Plus BABY dual strain probiotic drops in Nutrients, where 50 infants with infant distress syndrome received either the product or placebo for 21 days, and the probiotic group showed statistically significant reductions in total distress and inconsolable crying with good tolerability.
- The study underpins BioGaia’s effort to anchor its next generation Protectis Plus BABY line in published evidence as the formulation rolls out across the UK, Sweden, Finland, France and additional markets, linking product pipeline claims directly to peer reviewed outcomes in infants.
- We will now explore how BioGaia's investment narrative could be influenced by peer reviewed evidence backing its next generation infant probiotic.
Compare BioGaia’s clinically backed probiotic story with other health-focused stocks by scanning our hand picked 123 healthcare AI stocks that are also tying product claims to hard data.
BioGaia Investment Narrative Recap
To stay on board with BioGaia, you need to believe the business can keep turning clinically supported probiotics into commercial products across both Pediatrics and Adult Health, while managing regional swings and heavier capital spending. The analyst consensus Narrative on Simply Wall St leans on that mix shift and on management keeping operating costs broadly flat as net sales grow.
The new Protectis Plus BABY data reinforces BioGaia’s effort to tie infant products to published evidence, which supports the case for its higher margin, proprietary portfolio. The near term swing factor still looks more operational, though, around Asia Pacific volatility, cash conversion and whether recent production investments match actual demand.
The Nutrients publication on Protectis Plus BABY is the clearest recent proof point for that product pipeline. It validates the BG R46 dual strain formulation in infants and lands at the same time as the next generation drops reach the UK, Sweden, Finland and France, with more markets coming.
For catalysts, that matters because ongoing launches of proprietary, clinically supported products such as Protectis Plus with BG R46 are one of the core growth drivers highlighted in the analyst consensus Narrative on Simply Wall St. The key execution question is whether these evidence based rollouts translate into steady orders that support BioGaia’s expanded production footprint and offset softer, more volatile Asia Pacific demand.
BioGaia's narrative projects SEK 2.3b revenue and SEK 623.2m earnings by 2029. This assumes 11.6% yearly revenue growth and an earnings increase of about SEK 231.6m from SEK 391.6m today.
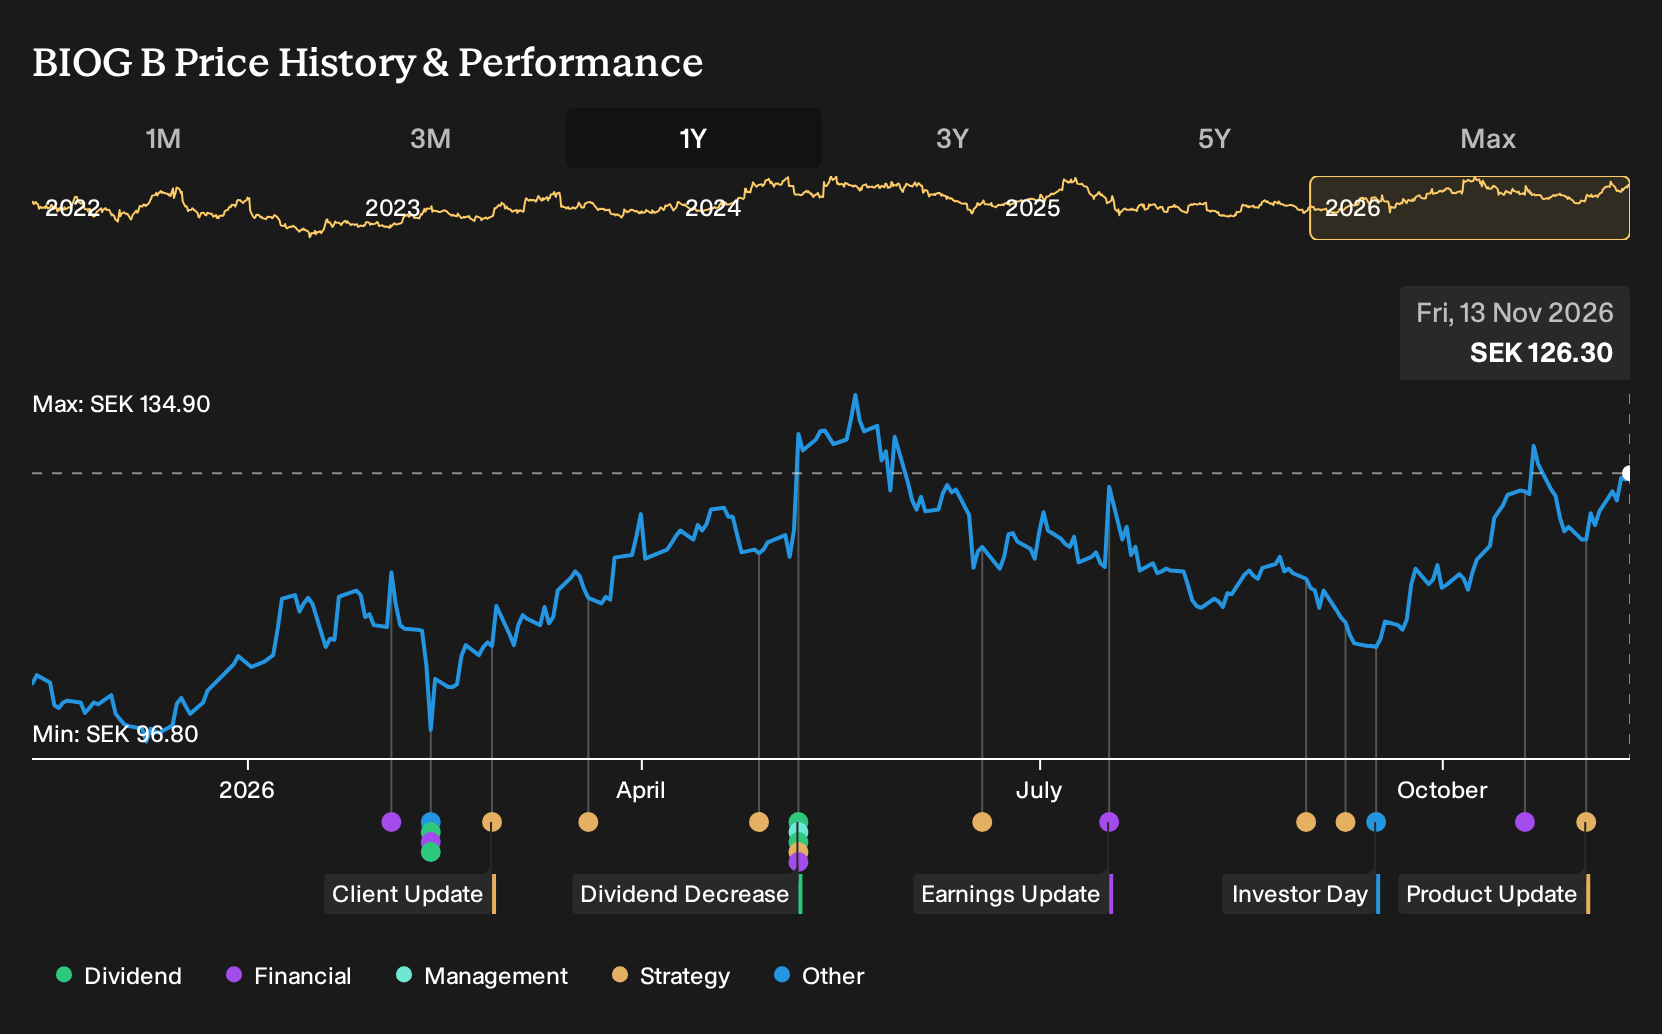
Discover how BioGaia's fair value indicates a 25% potential upside to its current price, which could narrow quickly if sentiment improves.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between SEK 152 and about SEK 174.9 per share, which already shows how far opinions on BioGaia can stretch. You now need to weigh that spread against risks around Asia Pacific volatility and cash conversion, as well as product launch momentum that could reshape future expectations.
Explore 2 other BioGaia fair value estimates, including one that suggests as much as 38% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Consider your own analysis and judgment.
- A great starting point for your BioGaia research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for BioGaia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BioGaia's overall financial health at a glance.
Looking for more investment ideas beyond BioGaia?
If the BioGaia story has sharpened your focus on quality and evidence, it can be useful to line it up against other opportunities that share similar traits, whether that means balance sheet strength, income potential or mispriced quality.
- For investors who care most about financial resilience, compare BioGaia with a list of solid balance sheet and fundamentals (198 results) that can handle tougher conditions without stressing their capital structure.
- If dependable income is your priority, set BioGaia alongside a 221 dividend fortresses that aim to combine meaningful yield with sustainability checks.
- When you want to hunt for quality that the market has not fully priced, weigh BioGaia against a 567 high quality undiscovered gems that pairs strong fundamentals with relatively low investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com