


EN
Unum Group (UNM) Faces A Valuation Test After Q3 Loss And SEC Driven Reporting Change
Unum Group (UNM) has moved into the spotlight after reporting a third quarter 2026 net loss of US$419.7 million and revising its after tax adjusted operating income definition following discussions with the SEC.
The weak third quarter results and SEC driven reporting change have come after a sharp swing in the share price, with Unum Group’s stock down 13.4% on a 1 month share price return and 12.8% on a 3 month share price return. This is the case even though the 1 year total shareholder return of 6.2% and very large 5 year total shareholder return suggest long term holders have still seen meaningful gains.
Look beyond Unum Group's selloff and compare this setup with a hand picked 30 resilient stocks with low risk scores that may better balance headline risk with balance sheet resilience.
After a drop that leaves Unum Group trading well below both analyst targets and some intrinsic value estimates, the key issue now is where fair value really sits within that range.
Most Popular Narrative: 19.7% Undervalued
On the analyst consensus Narrative on Simply Wall St, Unum Group’s fair value is pegged at about $99.38 compared with a last close of $79.84. This frames the recent selloff as a discount that hinges on execution in its core benefits franchise and long term care derisking.
Unum Group’s ongoing work to shrink and reinsure its long term care block, including the additional US$3.8b of statutory reserves ceded and the reaffirmation that the remaining block is self supporting, keeps more capital and management focus available for employee benefits. This can support earnings stability and reduce pressure on net margins.
Expanded use of Unum Group’s digital platforms such as HR Connect, Total Leave and Broker Connect, now tied to roughly half of Unum U.S. in force premium and accounting for over 20% of recent new sales, is deepening employer connectivity and helping sustain premium growth and fee revenue.
See why 23 investors see Unum Group as 20% undervalued.
Result: Fair Value of $99.38 (UNDERVALUED)
Still, elevated benefit ratios in group disability and life, along with renewed pressure in the long term care closed block, could quickly challenge that undervaluation story.
Find out about the key risks to this Unum Group narrative.
Another View on Unum Group’s Valuation
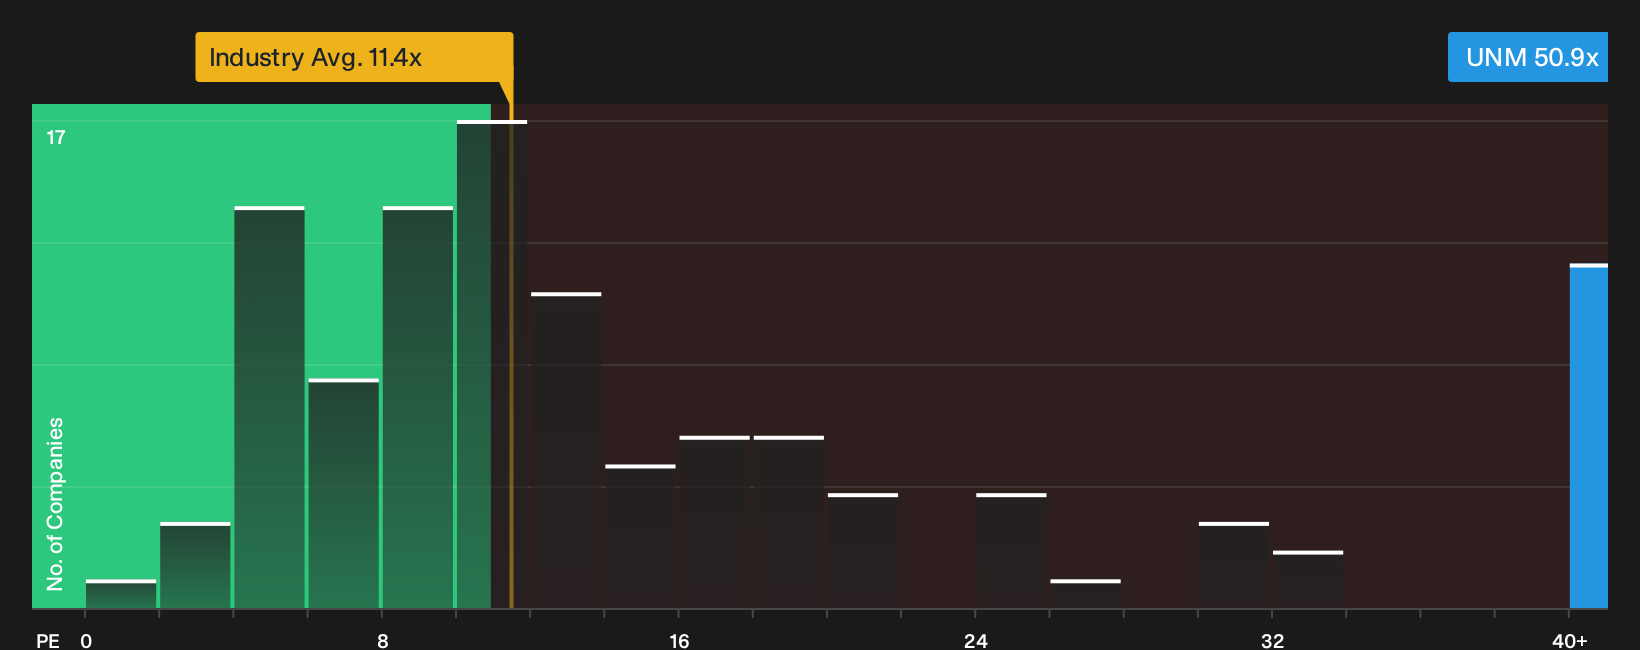
The first fair value story for Unum Group leans on analyst targets around $99.38. On simple P/E maths, the picture looks very different. UNM trades on roughly 50.9x earnings, compared with about 11.5x for the US Insurance group, a peer average of 15.2x and a fair ratio of 20x in our model. That gap points to meaningful valuation risk if sentiment shifts. The key question is which signal you treat as the anchor.
See what the numbers say about this price in more depth, and how they stack up against that fair ratio, in our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views about whether Unum Group’s selloff signals an opportunity or a warning. Act quickly, walk through the data for yourself, and weigh both the risks and potential upsides in the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Unum Group?
If Unum Group has sharpened your focus on risk, reward and valuation, use this moment to refresh your watchlist with fresh, high conviction ideas.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (24 results) that prioritises financial strength when market headlines turn noisy.
- Hunt for potential mispriced opportunities through a carefully filtered 34 high quality undervalued stocks that focuses on quality alongside attractive valuation signals.
- Build a cash flow focused portfolio by reviewing a curated 6 dividend fortresses aimed at pairing higher yields with business durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com