


EN
3 US Consumer Staples Stocks Investors May Revisit As Inflation Stays Above 3%
Retail sales are cooling just as the holidays approach, gasoline is eating into wallets, and inflation is still sitting above 3%. That mix is pushing many investors to rethink where they feel comfortable putting money to work, since not every stock reacts the same way when budgets tighten and rates stay high. This article walks through three consumer staples and defensive retailers from our screener that look most directly exposed to the latest macro shock.
The stocks highlighted below are just a sample drawn from this defensive corner of the market, and the full screen surfaced 9 more large US consumer staples and retail companies with equally compelling stories that are not covered here. To go deeper right now, identify your own shortlist and analyze each ticker in one place. Head straight into the US Consumer Staples and Defensive Retailers screener.
J&J Snack Foods (JJSF)
Overview: J&J Snack Foods sells soft pretzels, frozen novelties, churros, bakery items and frozen beverages to supermarkets and food service customers across North America.
Operations: J&J Snack Foods generates about US$947 million from Food Service, US$364 million from Frozen Beverages, and US$214 million from Retail Supermarket channels, mostly in the United States.
Market Cap: US$1.7b
J&J Snack Foods fits the consumer staples and defensive retailers theme because it operates in that space where low-ticket treats meet repeat purchasing. The bullish analyst Narrative on Simply Wall St states that the current focus is on how internal efficiency work could matter more than headline sales trends.
"Project Apollo savings that already support higher gross margin, including a raised annual run rate of at least US$25 million and plant consolidation now largely complete, leave room for J&J Snack Foods to redirect some of that freed up cash flow into additional automation or process changes that could push net margins higher than current models assume."
One question is what happens if a relatively quiet shift in how J&J Snack Foods earns each snack dollar ends up influencing overall profitability more than demand swings.
If that margin mix is where your thesis really lives, read the full narrative for J&J Snack Foods to see how J&J Snack Foods’ efficiency work could decouple profits from softer demand.

Spectrum Brands Holdings (SPB)
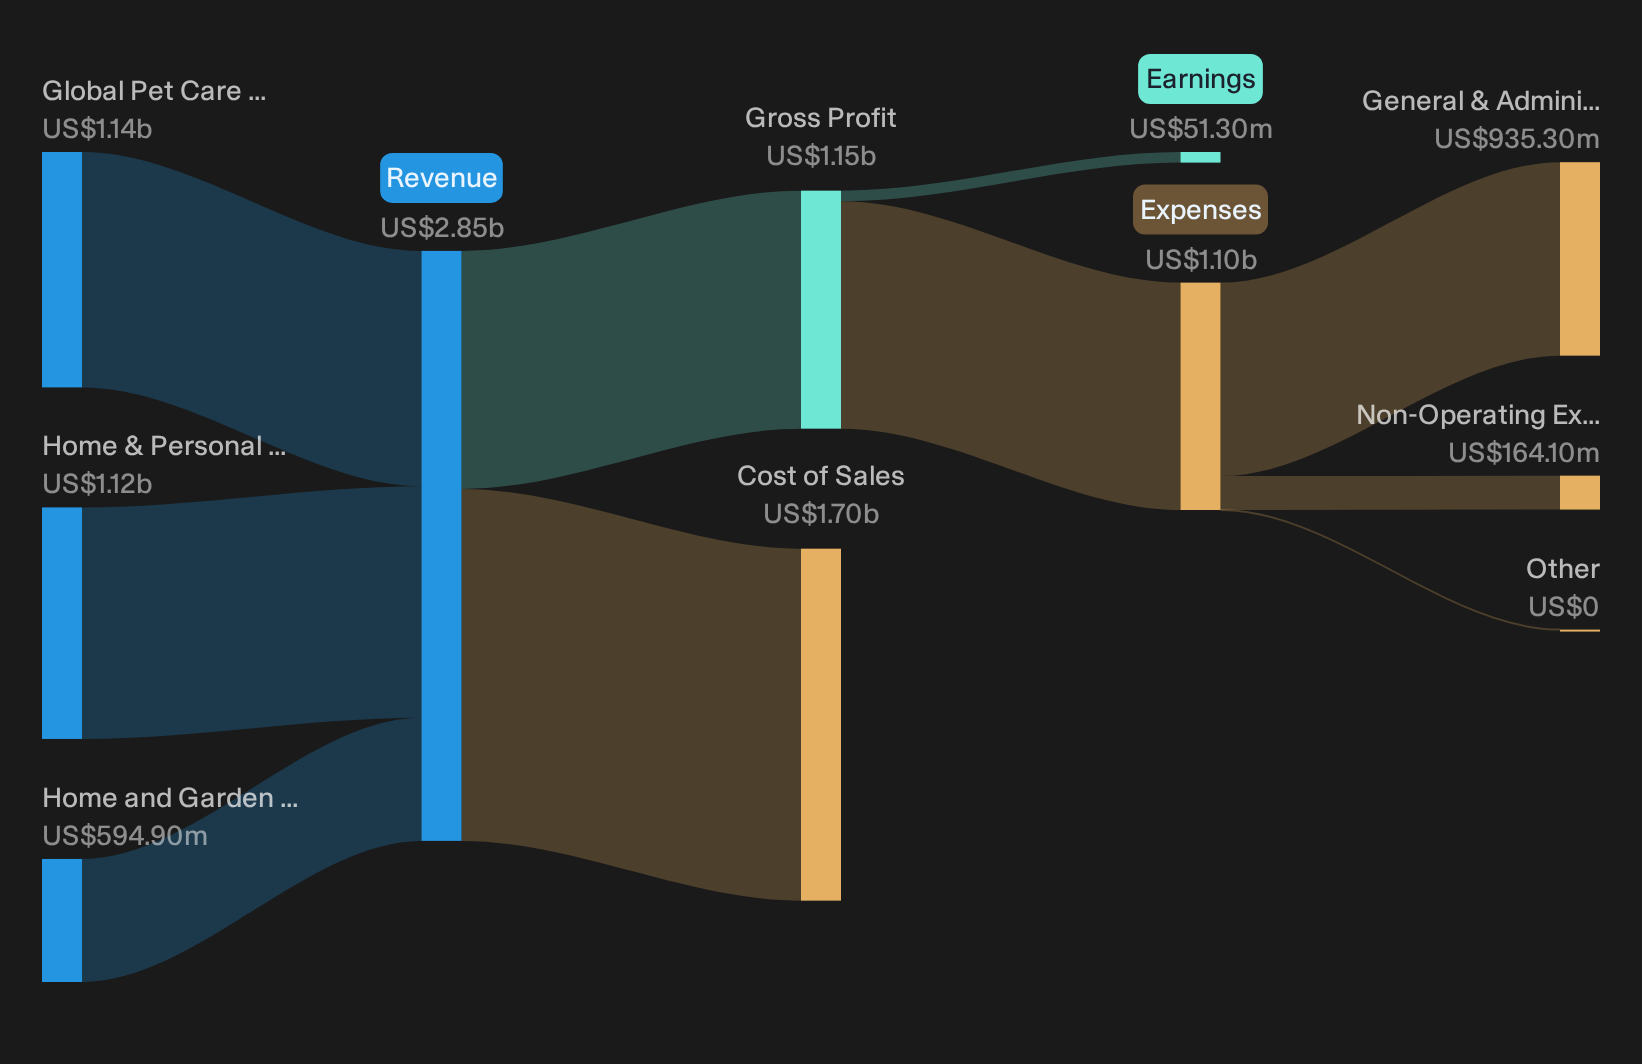
Overview: Spectrum Brands Holdings sells branded home appliances, pet care and home and garden products that plug straight into everyday household needs worldwide.
Operations: Spectrum Brands Holdings generates about US$1.1b from Global Pet Care, US$1.1b from Home & Personal Care, and US$595 million from Home and Garden products.
Market Cap: US$2.0b
For a consumer staples and defensive retailers screen built around everyday spending rather than big-ticket splurges, Spectrum Brands Holdings offers a mix of pet consumables, household pest control and small appliances that still sit close to the weekly shop. This is why the analyst consensus Narrative on Simply Wall St highlights one structural shift that could matter more than the latest sales headline.
"The separation of the Home & Personal Care segment through the US$127 million Oaktree investment, structured as preferred equity and a term loan that are non recourse to Spectrum Brands Holdings, creates a clearer path toward a focused Global Pet Care and Home & Garden profile that could shift how investors value future revenue and earnings."
What happens if a single assumption about how quickly that tighter pet and garden platform converts higher pricing into sturdier margins proves wrong.
That single assumption is the hinge. Read the full narrative for Spectrum Brands Holdings to see how Spectrum Brands Holdings could turn segment separation into accelerating value rather than stalled potential.
Flowers Foods (FLO)
Overview: Flowers Foods is a pure-play U.S. bakery group that supplies everyday packaged breads, buns and snacks to supermarkets and other food retailers.
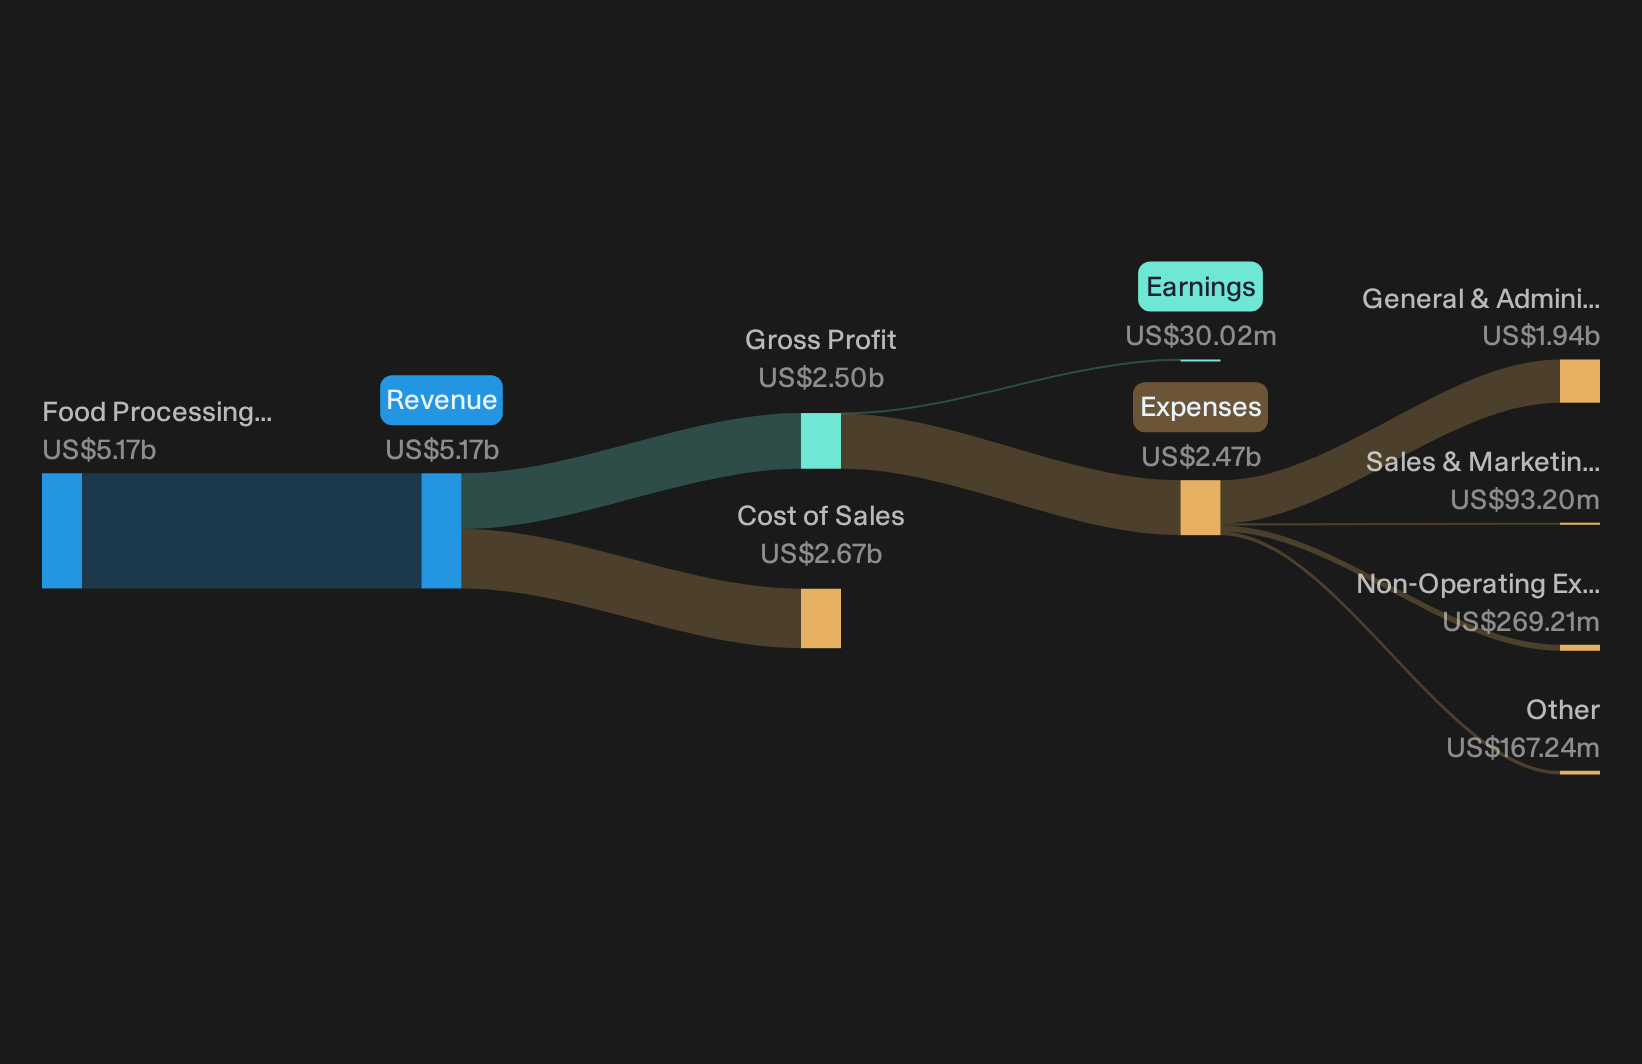
Operations: Flowers Foods generates about US$5.2b from Food Processing, effectively all of it in the United States, tying revenue tightly to domestic grocery demand.
Market Cap: US$1.2b
For an investor looking at consumer staples that track the weekly grocery run more than holiday splurges, Flowers Foods offers direct exposure to bread and baked goods that many households still buy even when budgets tighten. This is how the analyst consensus Narrative on Simply Wall St frames its role in this screener.
"Execution on the shift in Flowers Foods' portfolio toward Better For You bread and snacks, including products such as Nature’s Own Keto, Dave’s Killer Bread, Canyon Bakehouse gluten-free lines, and the Simple Mills platform, could support revenue mix toward categories that have recently shown unit and dollar share gains as well as faster retail sales growth."
One less visible pressure on Flowers Foods’ earnings path could quietly decide whether that mix shift restores margins or keeps them thin.
That pressure point is exactly where the story gets interesting. Read the full narrative for Flowers Foods to see whether Flowers Foods’ mix shift is quietly accelerating an earnings reset.
Seeking Alternatives While Curiosity Is High
Fresh opportunities move fast and can slip away before the crowd even looks. Scan new breakouts and quiet movers still under the radar for now, then evaluate them carefully.
- Track early momentum shifts in smaller companies and scan the 12 elite penny stocks with strong financials before these stories get fully priced.
- Spot rising leaders in automation and industrial efficiency by running through the curated 88 robotics and automation stocks while these trends develop.
- Review companies connected to potential power grid upgrades and search the hand-picked 44 power grid technology and infrastructure stocks as infrastructure-related themes evolve.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com