


EN
Should Dividend Policy Changes Require Action From GMO Payment Gateway Stock Investors?
- GMO Payment Gateway held its 2026 earnings call and a board meeting on 13 November 2026, with directors reviewing potential changes to the dividend policy alongside financial results.
- The pairing of fresh earnings commentary with a live discussion on dividend policy places both cash returns and reinvestment priorities under the spotlight for GMO Payment Gateway.
- The focus now turns to what this dividend policy review could mean for GMO Payment Gateway's broader investment narrative and risk profile.
Scan how other payout focused companies are positioning themselves after earnings calls by reviewing our curated 29 dividend fortresses alongside GMO Payment Gateway's latest dividend policy discussion.
What Is GMO Payment Gateway's Investment Narrative?
The big picture for GMO Payment Gateway is pretty simple. Investors need to believe that digital payments, value added services and money solutions can keep supporting solid earnings, and that management allocates capital sensibly between new products, lending and shareholder returns. The business currently reports a net margin of 27.6% on ¥91,225 of revenue and a 20.3% return on equity, which gives it room to fund growth while still running a dividend yield of 1.94%.
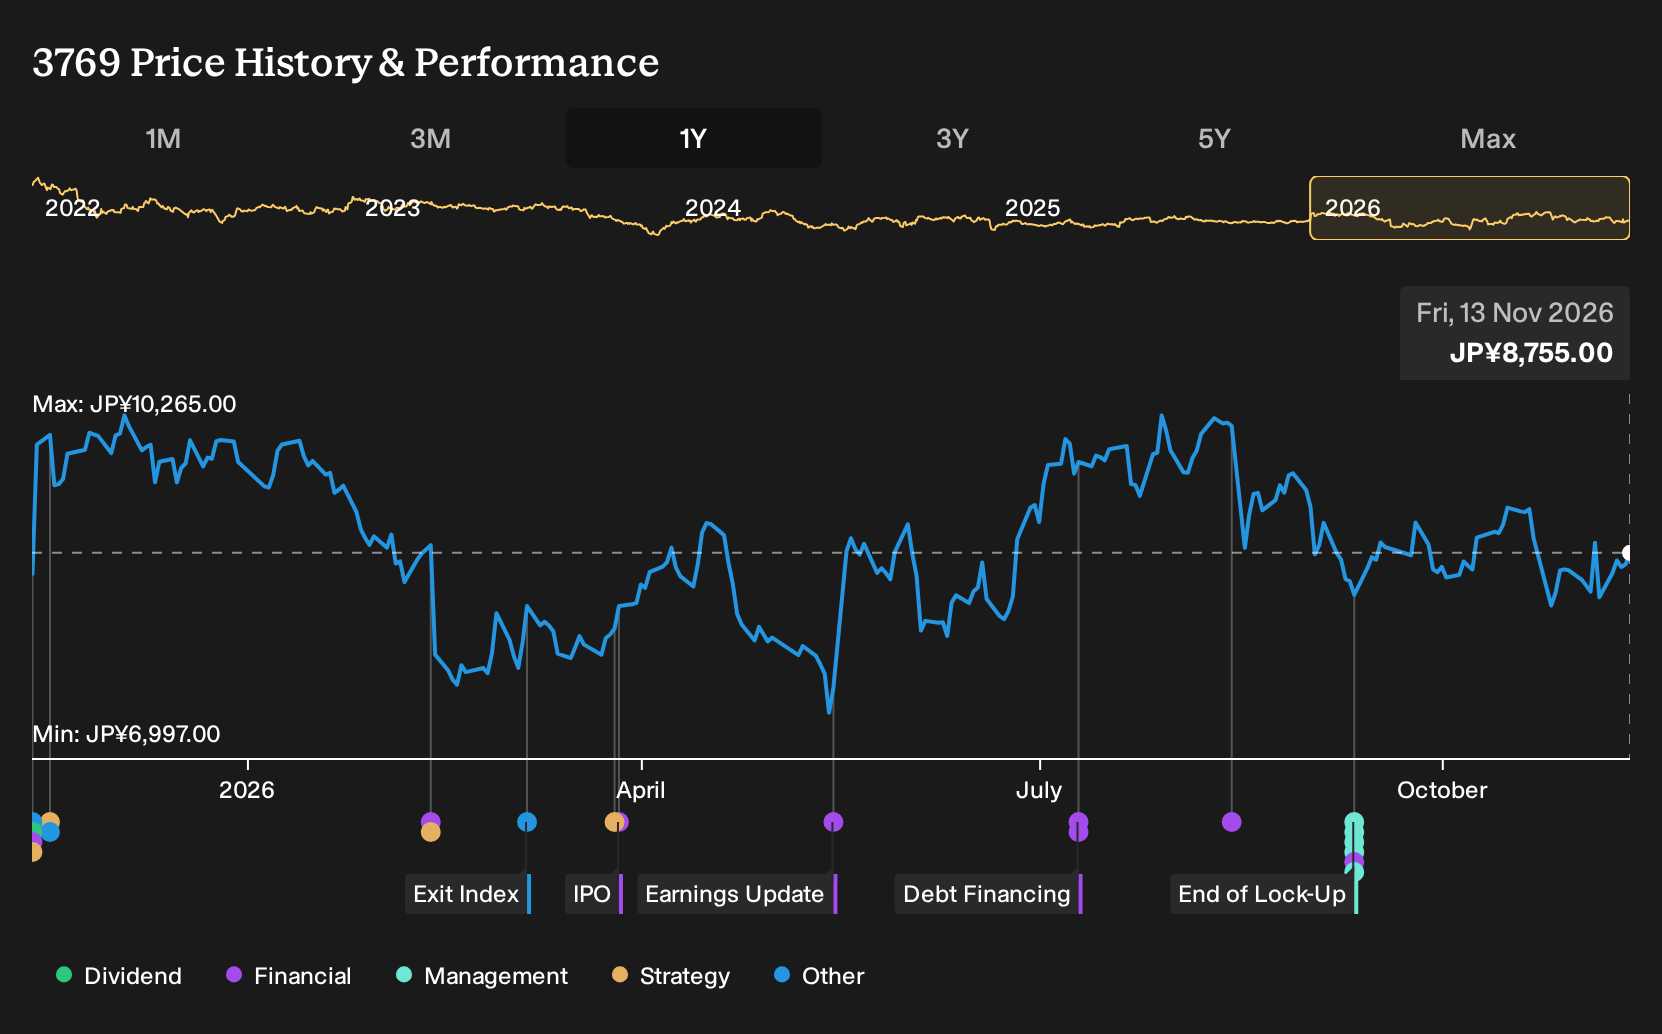
The recent earnings call and board discussion on dividend policy sit at the center of the key short term catalysts. Any change to the payout could shift the balance between reinvestment and cash returns. This matters when the share price has fallen 13.7% over 3 months while the stock still trades on a 26.4x P/E. Volatile trading and reliance on higher risk funding sources remain active watchpoints rather than background noise.
That said, there is a specific pressure point in this story that could become hard to ignore if ...
There's only one way to know the right time to buy, sell or hold GMO Payment Gateway. Head to Simply Wall St's company report for the latest analysis of GMO Payment Gateway's Fair Value.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your GMO Payment Gateway research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for GMO Payment Gateway. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate GMO Payment Gateway's overall financial health at a glance.
Looking For More Ideas Beyond GMO Payment Gateway?
If you want to stress test your thesis on GMO Payment Gateway, it helps to line it up against other opportunities that fit different income, quality and risk profiles on the Simply Wall St Screener.
- For income focused investors who still care about balance sheet resilience, compare GMO Payment Gateway with a 29 dividend fortresses that already screen for higher yields and durable payouts.
- If you are hunting for potential mispriced opportunities instead of only following well known tickers, check out a 73 high quality undiscovered gems that pair solid fundamentals with lighter market attention.
- For readers who want to keep downside risk in check first and worry about upside later, start with a 19 resilient stocks with low risk scores that filters for more resilient business profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com