


EN
What Consolidated Edison (ED)'s Earnings Beat Means For Shareholders
- Consolidated Edison reported third quarter 2026 revenue of US$4.913b and net income of US$766m, with basic EPS from continuing operations of US$2.07 compared with US$1.91 a year earlier.
- Across the first nine months of 2026, Consolidated Edison recorded US$14.078b in revenue and US$1.998b in net income. These figures highlight the scale of cash needed for its large grid and clean energy buildout in New York.
- We will now look at how Consolidated Edison’s third quarter earnings shape the investment narrative around its large grid program.
Compare Consolidated Edison's grid buildout story with other potential beneficiaries of the energy transition by scanning our hand picked 44 power grid technology and infrastructure stocks today.
Consolidated Edison Investment Narrative Recap
To own Consolidated Edison, you need to be comfortable with a long term regulated utility story built around New York grid investment, customer electrification and climate resiliency spending described in the analyst consensus Narrative on Simply Wall St. The third quarter results show the business currently producing earnings that support that thesis while funding demands for the large capital program remain heavy.
The key near term swing factor is how regulators treat future rate cases as these grid and renewables projects move from plans into the field. Higher earnings and EPS for the quarter do not materially change that central catalyst or the main risk around cost recovery, potential earnings sharing caps and pressure on debt and free cash flow coverage.
The most relevant fresh data point is the third quarter and nine month earnings release itself. Revenue of US$4.913b and net income of US$766m for the quarter, alongside US$14.078b of revenue and US$1.998b of net income year to date, show how large the New York platform is as it invests in grid upgrades, storage and renewables.
For catalysts, this profit base interacts directly with about US$38b of planned CECONY infrastructure spending over five years and US$72b over a decade highlighted in the analyst consensus Narrative on Simply Wall St. Execution risk sits around keeping reliability solid during extreme weather, containing operating costs and convincing regulators and customers that bill impacts from this capex and associated borrowing remain acceptable.
What The Current Forecasts Assume For Consolidated Edison
Consolidated Edison's narrative projects US$20.0b revenue and US$2.9b earnings by 2029. This rests on analysts assuming 3.5% yearly revenue growth and about a US$0.6b earnings increase from US$2.3b today.
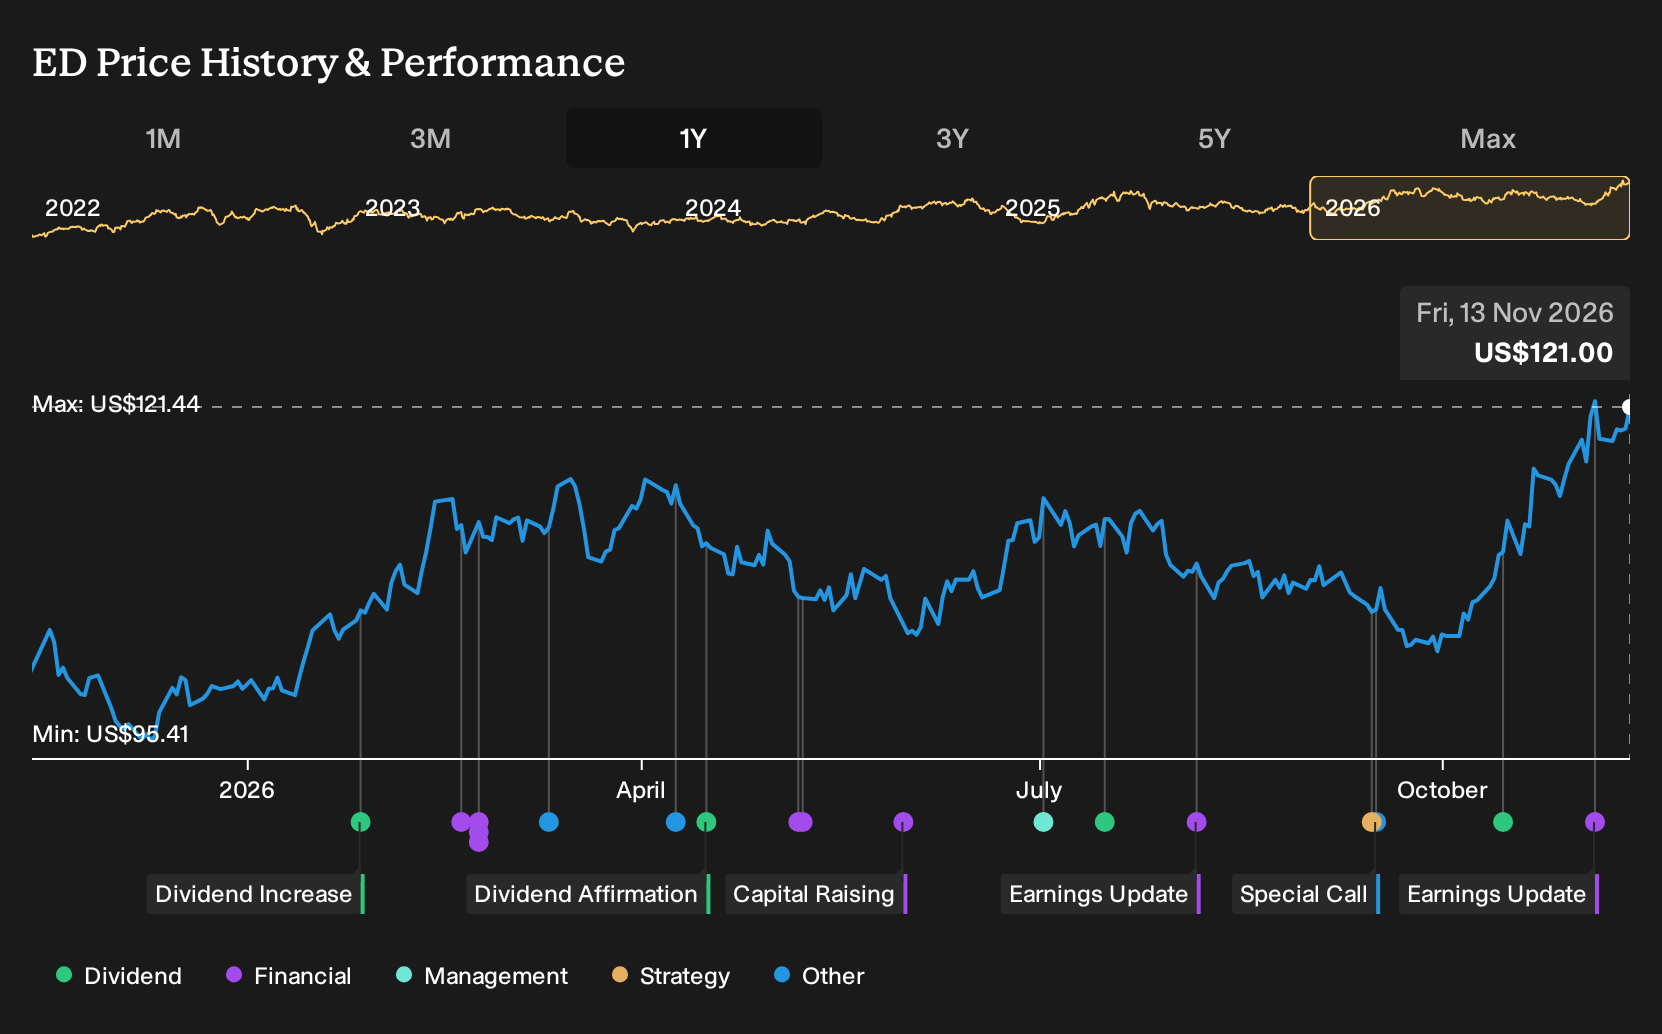
Uncover why Consolidated Edison's fair value indicates a 9% potential downside to its current price, suggesting that the current premium may not hold.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster tightly between about US$108.21 and US$109.79, so retail views on Consolidated Edison currently sit in a narrow band. Those opinions were formed before the latest earnings and before any fresh signals on New York regulation, so treat them as one starting point and compare them with other community perspectives.
Explore 2 other Consolidated Edison fair value estimates, including one that suggests it could be worth as much as $109.79.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view.
- A great starting point for your Consolidated Edison research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Consolidated Edison. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Consolidated Edison's overall financial health at a glance.
Looking For More Investment Ideas Beyond Consolidated Edison?
Once you have a handle on Consolidated Edison, it can help to widen your watchlist with stocks that fit different roles in a portfolio using the Simply Wall St Screener.
- If you want potential growth with strict risk controls, start by reviewing a curated 31 resilient stocks with low risk scores that aims to keep volatility and financial stress in check.
- For investors who care about balance sheet strength and fundamental resilience, scan a focused list of solid balance sheet and fundamentals (24 results) that surfaces businesses with sturdier finances.
- If you are hunting for opportunities the wider market might be overlooking, look through a targeted 20 high quality undiscovered gems that filters for quality first and visibility second.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com