


EN
Redwire (RDW) Stock Dropped, So What Is Behind The Latest Attention?
Redwire (RDW) is back under the microscope after third quarter revenue fell short of Wall Street forecasts, even as the company reaffirmed full year sales guidance and highlighted new NASA and defense awards.
Redwire's share price has been under pressure since the third quarter update, with the stock down 42.36% over 90 days and 14.40% year to date, even though the 1 year total shareholder return of 42.88% and roughly tripled 3 year total shareholder return point to earlier momentum that now looks to be fading as investors reassess execution risks in light of the recent run of NASA, DARPA and U.S. Army contract wins.
Scan how other space and defense stocks are reacting to contract wins and execution risks by reviewing our curated list of 20 high quality undiscovered gems alongside Redwire.
After a sharp pullback in Redwire, despite new NASA and defense wins and reaffirmed sales guidance, the key issue now is simple. Does the current valuation still compensate you for the execution risk just revealed?
Most Popular Narrative: 40% Undervalued
Redwire last closed at $7.73, while the most followed valuation narrative on Simply Wall St pegs fair value at $12.82. According to Bailey, an investor in the Simply Wall St Community who wrote that narrative, the current gap between price and intrinsic value rests heavily on how investors view the contract pipeline, integration progress and future cash generation.
The pipeline of roughly US$10 billion of identified opportunities, with US$3 billion of proposals submitted year to date and a Q3 2025 book to bill ratio of 1.25x that lifted backlog to US$355.6 million, suggests that converting even a portion of this funnel could support revenue visibility and a path toward positive adjusted EBITDA and cash from operations.
See why 44 investors see Redwire as 40% undervalued.
Result: Fair Value of $12.82 (UNDERVALUED)
Still, the Redwire narrative can break if government contracts slip during budget disruptions or if ongoing Edge Autonomy integration fails to lift earnings and cash generation.
Find out about the key risks to this Redwire narrative.
Another View: Redwire Looks Expensive On Sales
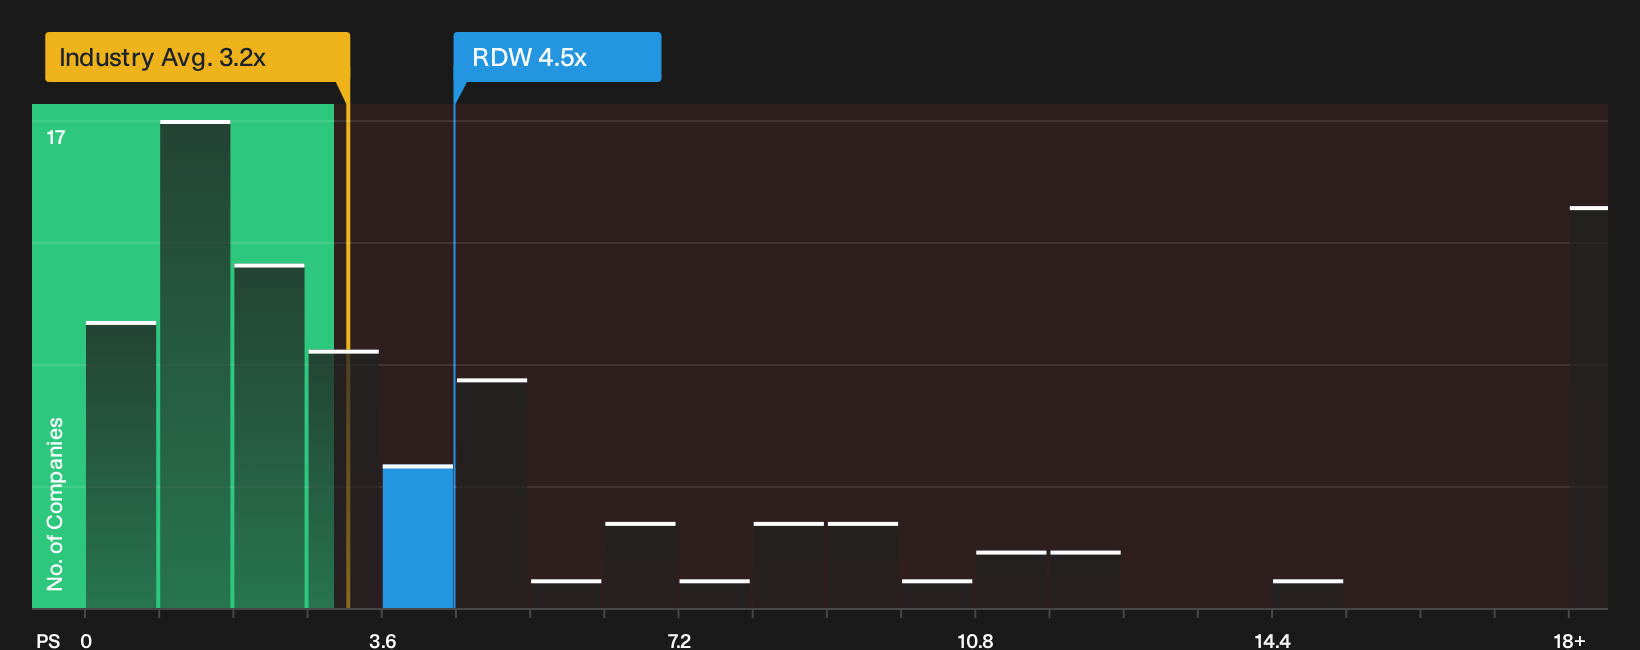
The user narrative leans on future cash flows and pegs Redwire at a fair value of $12.82. The sales multiple paints a tougher picture. At a P/S of 4.5x, Redwire trades well above the US Aerospace & Defense industry on 3.2x, peers on 3.4x, and the fair ratio on 2.3x.
That gap suggests you are paying a premium sales price for a business that is still loss making, which raises the bar for execution on contracts and profitability before the share price feels comfortable at these levels in a setback.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Redwire can either paralyze you or prompt a closer look at the underlying data and narrative drivers. Take a moment to assess both sides for yourself and pressure test your thesis against the 2 key rewards and 3 important warning signs.
Looking for more Redwire sized opportunities?
If Redwire has you rethinking risk, do not stop here. Use the Simply Wall St screener to hunt for fresh ideas before others move first.
- Target steady compounders by reviewing a curated 31 resilient stocks with low risk scores that prioritises resilience when conditions get choppy.
- Hunt for mispriced quality through the 32 high quality undervalued stocks that filters for stronger fundamentals at prices that may not fully reflect them yet.
- Zero in on balance sheet resilience by scanning the list of solid balance sheet and fundamentals (24 results) that filters for financial strength beyond headline earnings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com