


EN
Peloton Interactive (PTON) Prices $700 Million Notes, Is The Stock Cheap?
Peloton Interactive (PTON) is back in the spotlight after upsizing and pricing a private offering of US$700 million in senior secured notes due 2032, a refinancing move closely watched by equity investors.
The fresh refinancing news arrives after a mixed stretch for Peloton Interactive’s investors. A 12.65% one-month share price return and a 3.07% move higher over the last session contrast with a year-to-date share price decline of 6.86% and a one-year total shareholder return that is down 23.8%. This suggests recent momentum is improving even as longer-term holders still face pressure.
Scan how Peloton Interactive’s refinancing move compares with peers by reviewing companies on the 31 resilient stocks with low risk scores that pair balance sheet strength with more resilient share price profiles.
Peloton Interactive now trades at a steep discount to both analyst targets and some fair value estimates, even after the refinancing bounce. Is the market correctly pricing lingering risk, or is it leaning too hard into caution?
Most Popular Narrative: 27% Undervalued
Peloton Interactive’s last close at $5.70 sits below the analyst consensus Narrative fair value of $7.83, which uses an 8.44% discount rate and ties that gap directly to detailed earnings and revenue forecasts in the analyst consensus Narrative on Simply Wall St.
The main thing that has to go right is that Peloton turns its early connected wellness and AI traction, its commercial and Spotify reach, and its more accessible hardware and micro stores into stable or rising memberships and durable subscription economics, despite recent churn and revenue pressure.
The current valuation implies that the market remains cautious about Peloton’s ability to sustain its recent profitability and cash generation while dealing with declining memberships, a P/E above industry averages, and concerns raised by at least one major bank about long term subscription headwinds.
See why 26 investors see Peloton Interactive as 27% undervalued.
Result: Fair Value of $7.83 (UNDERVALUED)
Still, the Peloton Interactive thesis depends on stabilising memberships and managing a premium P/E. Prolonged hardware or subscription weakness could quickly challenge that story.
Find out about the key risks to this Peloton Interactive narrative.
Another View: Peloton Interactive Through The Earnings Lens
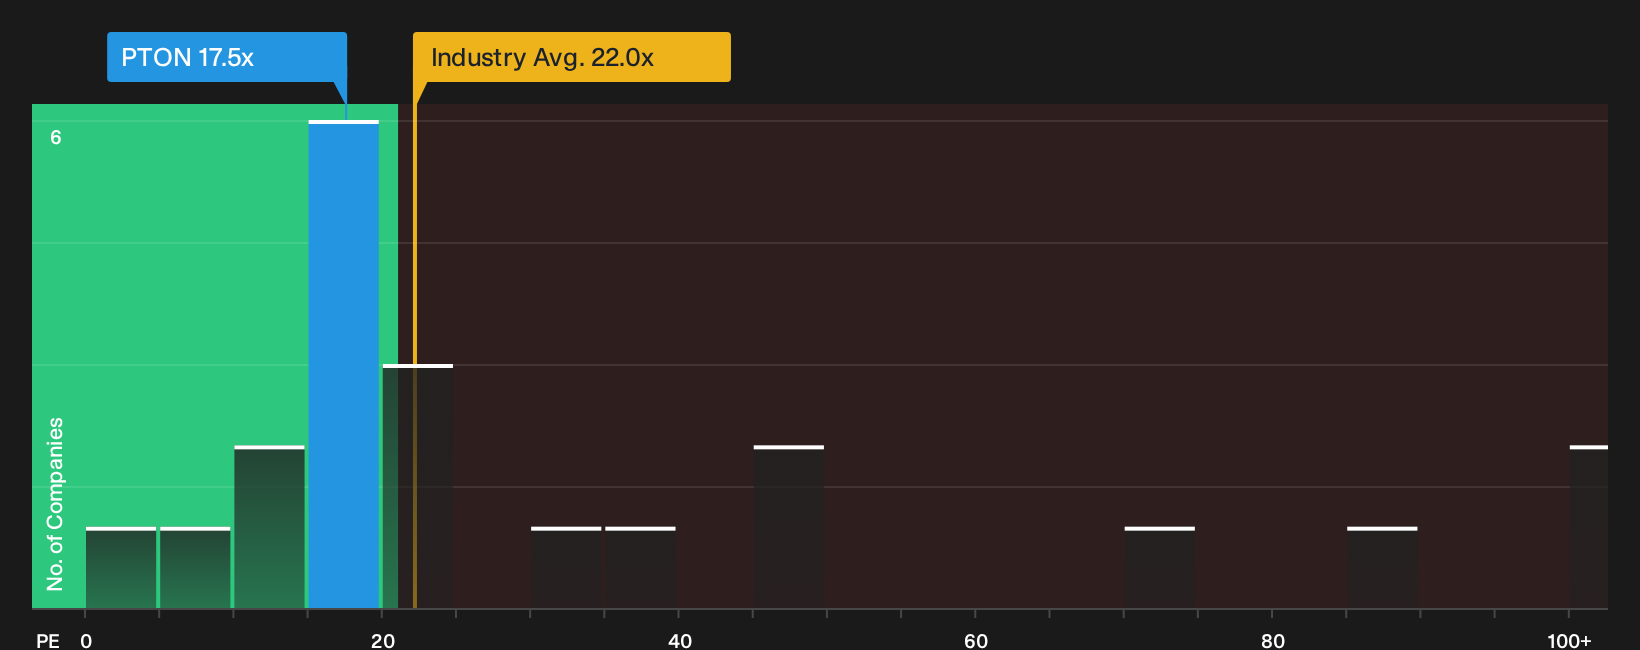
Peloton Interactive screens differently when shifting from the Narrative fair value to simple earnings ratios. The stock trades on a P/E of 17.5x, almost identical to its fair ratio of 17.4x and only slightly below the US Leisure average of 21.5x. That points to a far less dramatic discount and raises a basic question. Is the bigger opportunity in the growth story, or just in paying a fair price for what Peloton is today?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Peloton Interactive’s valuation and refinancing story can look messy at first glance, so move quickly to review the underlying data and pressure test your own view. To see both sides of the ledger in one place, start with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Peloton Interactive?
Do not stop with Peloton Interactive when there are other opportunities to compare. Use the Simply Wall St screener to line up fresh ideas against your watchlist.
- Hunt for potential bargains that pair quality with attractive entry prices by scanning the 32 high quality undervalued stocks.
- Strengthen your core holdings by focusing on resilient balance sheets and steady fundamentals with the list of solid balance sheet and fundamentals (24 results).
- Target income opportunities that combine higher yields with sturdier profiles by reviewing the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com