


EN
Did Earnings Beat Just Shift AAON's (AAON) Investment Narrative?
- AAON reported record third quarter 2026 sales of US$707.43 million and net income of US$68.96 million, raised full year net sales growth guidance to 72% to 75%, and arranged a significantly larger credit facility with extended maturities along with a US$100 million supply chain financing program.
- The combination of rapid data center cooling demand, a higher 2026 outlook and expanded borrowing capacity directly ties AAON's operating performance to its ability to fund large projects, manage working capital and support a larger manufacturing footprint.
- We will examine how AAON's upgraded full year sales outlook and expanded credit facility reshape the broader investment narrative.
Compare AAON's surge in data center demand and fresh funding capacity with other potential breakout infrastructure plays by scanning our hand-picked 53 AI infrastructure stocks.
AAON Investment Narrative Recap
To own AAON, you need to believe that the surge in data center cooling orders, broader commercial HVAC demand and the multi site manufacturing build out can translate into sustainable profitability and healthier cash generation. The analyst consensus Narrative on Simply Wall St leans on margin recovery and operating leverage, which still depends on the Memphis and BASX ramps settling in cleanly.
The near term catalyst remains execution on that data center backlog without further gross margin pressure or cash burn. The biggest risk is that high capex and working capital needs keep free cash flow weak, so even with strong reported earnings, returns on those investments may look stretched.
The refinancing and expansion of AAON's senior credit facility to as much as US$1.2b is the operational hinge for this story. Bigger committed capacity, a term loan and an accordion feature give the company room to fund the Memphis, Longview and BASX build outs while still absorbing supply chain and inventory swings.
That liquidity also ties directly into near term catalysts. If AAON converts its record Q3 order book into shipped systems while using the US$100m supply chain financing program to smooth payables and receivables, investors gain clearer line of sight on whether the current reinvestment heavy model can mature into stronger free cash flow rather than ongoing balance sheet strain.
AAON's narrative projects US$3.8b revenue and US$501.9 million earnings by 2029. This assumes revenue grows at 18.6% per year and earnings rise by about US$297.3 million from US$204.6 million today.
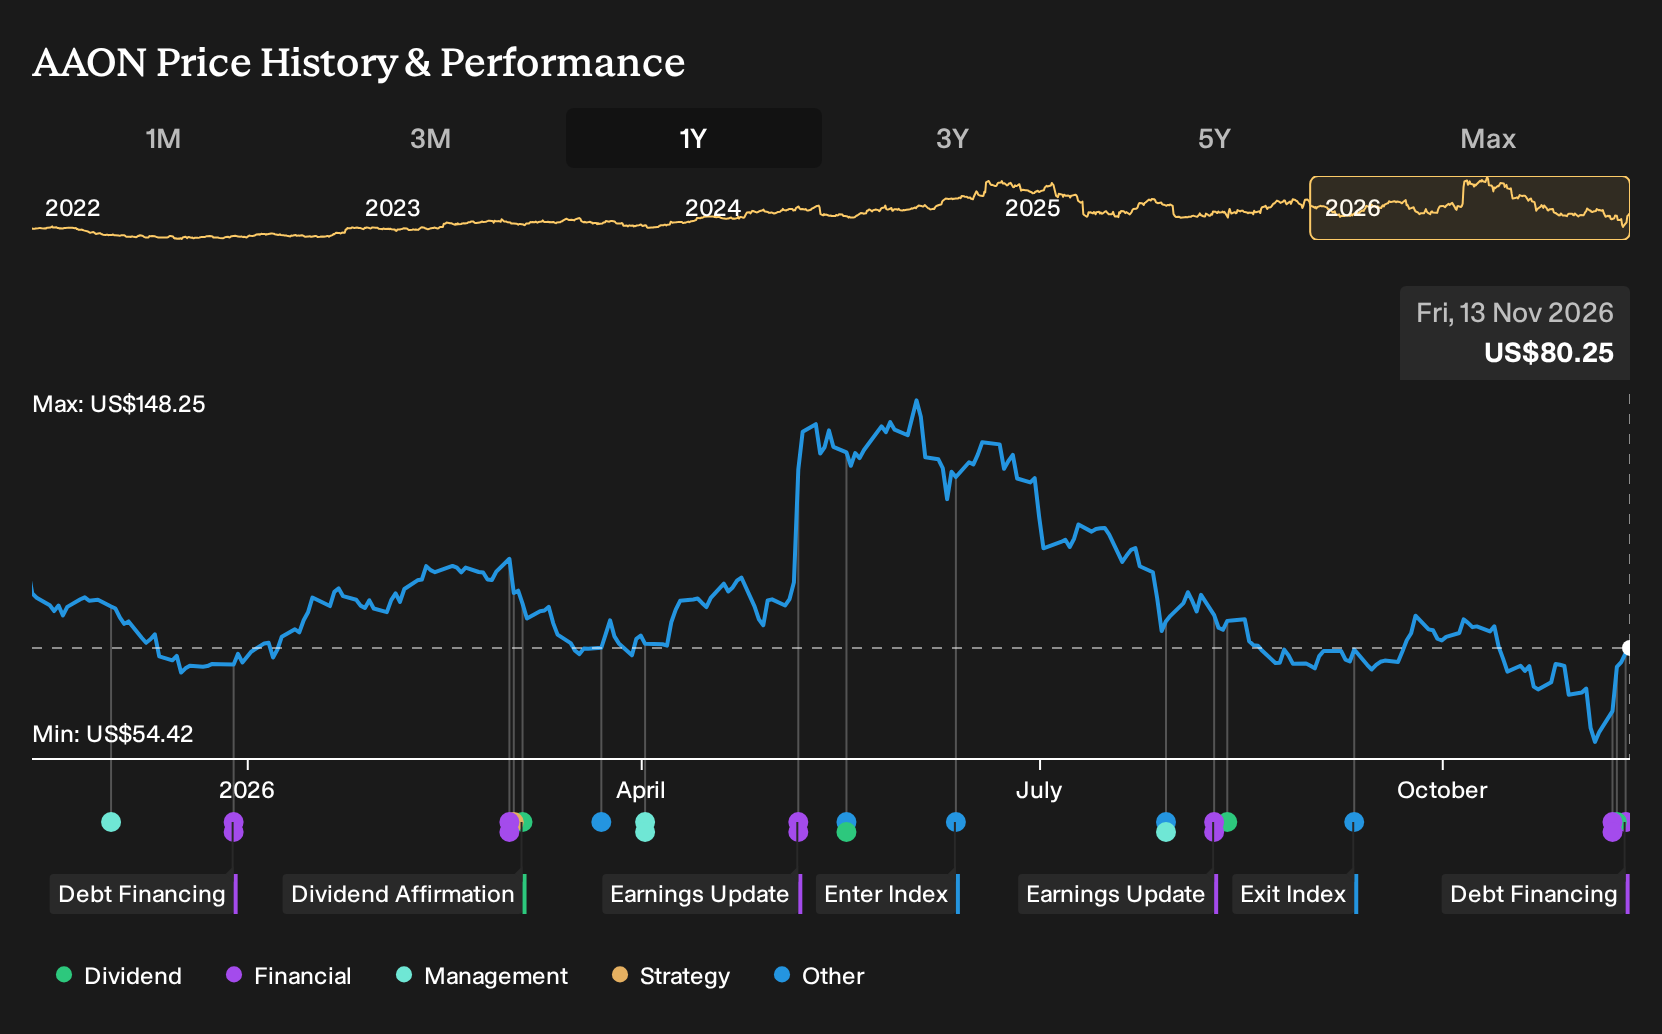
Discover why AAON's fair value points to a 46% potential upside to its current price before that gap closes.
Exploring Other Perspectives
One bearish twist on AAON focuses on the risk that this much larger credit facility simply feeds a long stretch of weak free cash flow. Before this news, the most cautious analysts were still modeling revenue of about US$3.8b and earnings near US$517.7 million by 2029, but they applied a lower P/E and a tighter valuation. That gap with consensus shows how far opinions can spread. Use it as a prompt to compare several narratives before deciding how these fresh financing moves might reshape your own view.
Explore 3 other AAON fair value estimates, including one that suggests it could be worth just $104.00!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your AAON research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AAON. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AAON's overall financial health at a glance.
Looking for more AAON sized investment ideas?
If AAON has sharpened your focus on where capital could work hardest over the next few years, it makes sense to widen the search to other companies with clear stories and measurable fundamentals. The Simply Wall St Screener lets you filter that universe quickly so you can concentrate on a short list that genuinely fits your style.
- If capital preservation sits high on your priority list, start with companies that pair resilience with measured risk through the 31 resilient stocks with low risk scores.
- For readers who want quality at a reasonable entry point, aim your research at businesses that screen well on valuation and fundamentals using the 32 high quality undervalued stocks.
- If you like the idea of finding future compounders early, focus your attention on lesser known businesses with solid numbers by scanning the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com