


EN
Earnings Growth Might Change The Case For Investing In United Internet (XTRA:UTDI)
- United Internet reported earnings for the nine months to 30 September 2026 with sales of €4,638.26 million and net income of €177.3 million, alongside basic earnings per share from continuing operations of €1.04.
- The breadth of improvement in United Internet's basic and diluted earnings per share, both at group level and from continuing operations, highlights how profitability across the business has shifted relative to the prior year period.
- We will now look at how United Internet's higher net income for the period could reshape the investment narrative that investors focus on.
Scan how United Internet's latest earnings stack up against peers by comparing it with the hand picked 199 high quality undervalued stocks that pair stronger balance sheets with disciplined profitability.
United Internet Investment Narrative Recap
To own United Internet, you need to be comfortable with a telecom and digital services group that is still in an investment heavy phase, while aiming for a cleaner earnings profile from owned infrastructure and higher margin IONOS and Mail & Media activities. The analyst consensus Narrative on Simply Wall St leans on that mix shift. The latest nine month results, with higher net income and earnings per share, support the idea that efficiencies and scale effects are already feeding into profitability.
The flip side is unchanged. Capital expenditure on fiber, mobile and data center projects remains a key swing factor for free cash flow and leverage, and that risk does not disappear because earnings improved this period. Wholesale costs under the Vodafone roaming deal and the pressure on 1&1 service revenue still matter for short term margin progress, so the most important near term catalyst is execution on network migration and cost control rather than headline revenue moves.
The fresh earnings release for the nine months to 30 September 2026 is the clearest operational update to plug into that story. Sales of €4,638.26 million and net income of €177.3 million put a concrete number on how the infrastructure build, IONOS expansion and Mail & Media transition are flowing through the income statement. Basic earnings per share from continuing operations of €1.04, compared with €0.76 a year ago, indicates that recent efficiency measures and mix trends are having an effect on the bottom line.
For you as a shareholder or prospective investor, this matters because the key catalysts highlighted in earlier commentary, such as lower cash capex guidance for 2026 and improving free cash flow after leases, already pointed to a potential easing of balance sheet pressure. The current results show higher earnings alongside that capex trajectory. This reinforces the view that United Internet can work through its heavy investment phase while managing debt and still focus on margins in IONOS and Mail & Media, provided telecom service revenue mix and roaming costs do not worsen from here.
What Analysts Are Building Into Their United Internet Models
Analyst models for United Internet lean heavily on gradual rather than explosive change. Revenue is assumed to rise by 2.6% per year over the next three years, helped by higher forecast profit margins that move from 5.1% today to 6.2% in that same period.
Earnings today are pegged at €317.4 million, with consensus forecasts pointing to €418.2 million by 2029. That is an earnings increase of about €100.8 million, which sits behind the forecast earnings per share of €2.09 and implies that the current capital and cost program needs to translate into a cleaner income line, not just higher sales.
On the revenue side, the analyst story aligns around United Internet reaching about €6.7b of sales in 2029 and converting that into €418.2 million of profit. To reconcile those figures with current price targets, models typically plug in a P/E of 18.0x on those 2029 earnings, compared with about 13.5x today. Many also use a discount rate in the region of 10.4% to 10.45% when pulling those future streams back to present value.
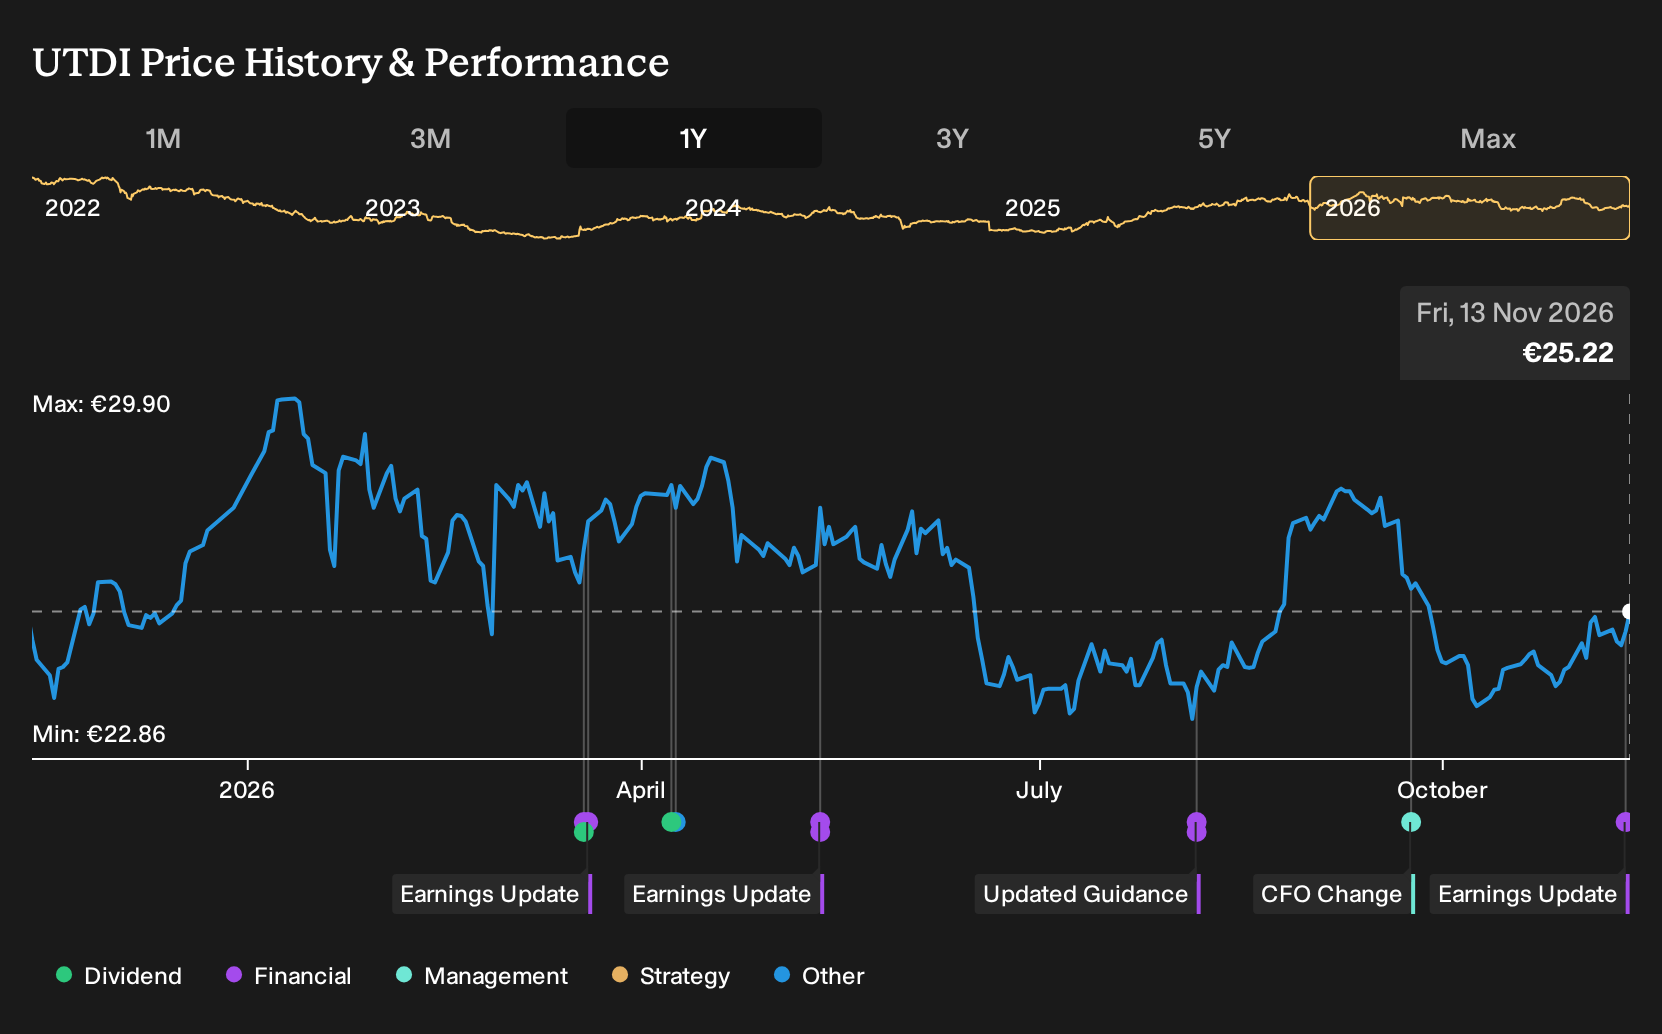
The range of opinions is wide. Some analysts pencil in 2029 earnings as high as €528.5 million, while the most cautious sit closer to €334.2 million. This leads to a cluster of price targets between €29.0 and €35.0 and a current consensus of €32.26 against a recent share price of €24.82.
United Internet's narrative projects forecast revenue of about €6.7b and consensus earnings of €418.2 million by 2029. This implies 2.6% yearly revenue growth and an earnings increase of roughly €100.8 million from current earnings of €317.4 million.
Uncover why United Internet's fair value indicates a 28% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle on United Internet focuses on free cash flow rather than earnings. Before this nine month update, the most optimistic analysts were pencilling in about €7.2b of revenue and €490.2 million of earnings by 2029. You might see this earnings beat and wonder if those already bullish models will shift even further, or if some forecasts were simply early. Opinions can spread widely, so treat this as an invitation to compare several viewpoints before deciding how you interpret today’s numbers.
Explore 2 other United Internet fair value estimates, including one that suggests as much as 28% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your United Internet research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for United Internet. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate United Internet's overall financial health at a glance.
Looking for more investment ideas beyond United Internet?
Once you have a view on United Internet, it can help to line it up against other opportunities that fit different goals, from resilient balance sheets to income or potential mispricing. The Simply Wall St Screener is built for that kind of side by side comparison so you can pressure test your thesis rather than rely on a single story.
- If capital preservation matters most to you, start with companies that emphasise stability and low risk by scanning through the 212 resilient stocks with low risk scores.
- For investors who want strong fundamentals and cleaner balance sheets, broaden your watchlist with the list of solid balance sheet and fundamentals (198 results).
- If you are hunting for lesser known opportunities with solid financial profiles, cast the net wider using the 568 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com