


EN
Raised 2027 Outlook Might Change The Case For Investing In Exchange Income Stock
- Exchange Income Corporation reported third quarter 2026 sales of C$719.68 million and net income of C$95.63 million, with higher basic earnings per share from continuing operations compared with the prior year, alongside stronger nine month figures on revenue and profit.
- The business coupled this earnings update with a higher adjusted EBITDA outlook for 2027, indicating management’s expectations for aviation demand and planned manufacturing contributions, while maintaining more than C$2 billion of available liquidity.
- We will now explore how Exchange Income's updated 2027 adjusted EBITDA target could influence the existing investment narrative built around essential air services and infrastructure-linked manufacturing.
Scan how Exchange Income's earnings story compares with other aviation and infrastructure driven plays by running the list of solid balance sheet and fundamentals (6 results).
Exchange Income Investment Narrative Recap
To own Exchange Income, you need to be comfortable with a thesis built on essential air services, defense related aviation work and infrastructure linked manufacturing, all feeding into consistent cash generation. The latest quarterly results, with higher sales and net income than a year ago, support that operating story rather than altering it.
The key short term catalyst remains execution on expanded aviation demand and the Air Canada flying ramp up that underpins the 2027 adjusted EBITDA target. The biggest near term risk is still heavier maintenance capital spending and depreciation, especially around Canadian North, which could squeeze free cash flow and reported earnings if activity or pricing softens.
The analyst consensus Narrative on Simply Wall St already framed the upside around more contracted flying in the Canadian North, medevac work and PAL Aerospace missions, alongside growth in Environmental Access Solutions and precision manufacturing. Exchange Income’s updated 2027 adjusted EBITDA target of C$1.0 to C$1.06b ties directly into those same operational levers and gives investors a clearer yardstick for execution.
This outlook also sits against a balance sheet that management reports as having more than C$2b of available liquidity and leverage previously cited around 2.82x. That capacity matters for funding maintenance and growth projects without over stretching, especially while Multi Storey Window solutions faces softer condo markets and U.S. tariff headwinds that can still weigh on consolidated margins.
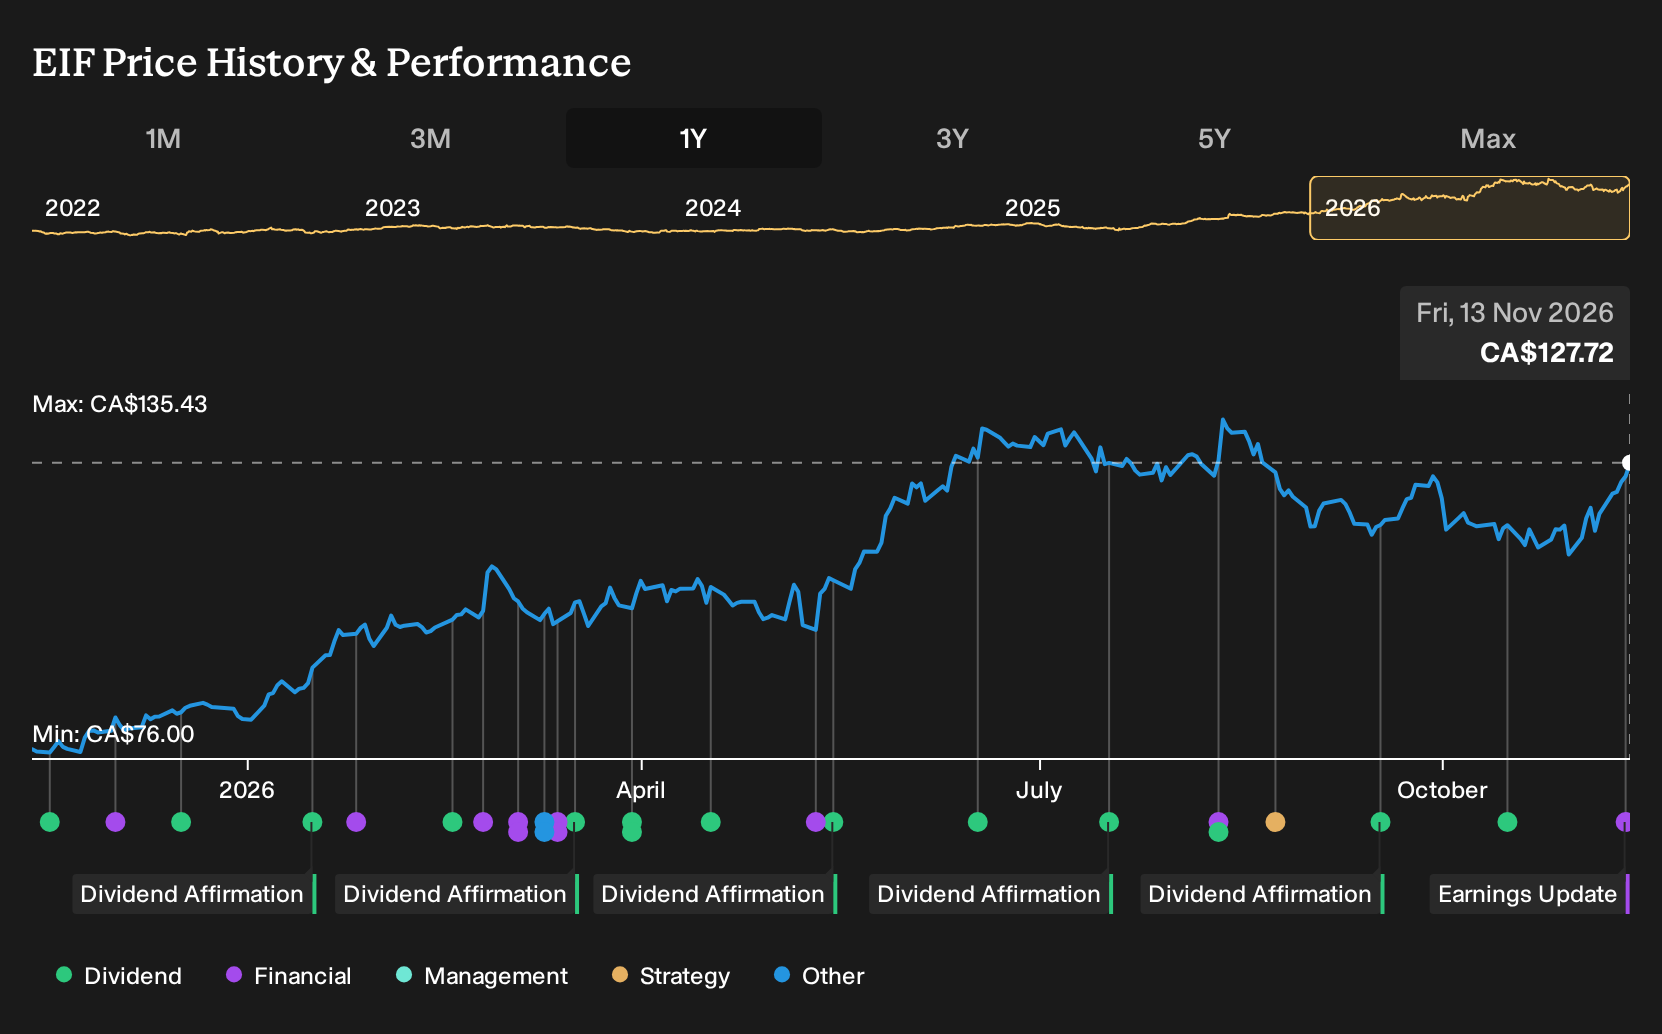
Exchange Income's current earnings are CA$205.1 million, with analysts forecasting earnings of CA$395.4 million by 2029, which implies an increase of about CA$190 million from today. Consensus assumptions also point to revenue of CA$4.7 billion by that same year on the back of 8.0% yearly revenue growth.
Uncover why Exchange Income's fair value indicates a 19% potential upside to its current price before that discount gap narrows.
Exploring Other Perspectives
Some analysts anchor their more optimistic narrative for Exchange Income on acquisition firepower rather than solely on the 2027 EBITDA target. Before this earnings release, the most bullish forecasts were already calling for revenue of about C$5.0b and earnings of roughly C$466.2 million by 2029. That is a much richer picture than consensus, and it may shift again as you weigh fresh results against those pre news assumptions.
Explore 3 other Exchange Income fair value estimates, including one that suggests as much as 48% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Exchange Income research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Exchange Income. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate Exchange Income's overall financial health at a glance.
Looking For More Investment Ideas Beyond Exchange Income?
If Exchange Income has helped clarify what you want from an aviation and infrastructure stock, it can be useful to pressure test that thinking against a wider watchlist. The Simply Wall St Screener lets you filter for other companies that line up with your preferred mix of quality, stability and upside potential.
- If you care most about balance sheet strength and fundamental resilience, start with this curated list of solid balance sheet and fundamentals (6 results) that share similar financial discipline.
- If the goal is to find opportunities where quality and price still look appealing, widen your search to companies in the 7 high quality undervalued stocks that fit your risk tolerance.
- If income is a priority and you want payouts backed by solid businesses, focus your next search on stocks in the 3 dividend fortresses that may suit a dividend focused portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com