


EN
PPL (PPL) Draws A New Valuation Debate After Q3 Results And A $25b Growth Plan
Third quarter earnings shift focus to PPL’s growth plans
PPL (PPL) moved back into the spotlight after third quarter 2026 results showed higher sales and net income, paired with a new $25b capital plan and updated long-term earnings targets.
Recent trading shows a mixed picture for PPL. The 3 year total shareholder return of 50.99% and 5 year total shareholder return of 49.35% point to solid long run gains, while shorter term share price moves have been more muted, even after the third quarter update and $25b capital plan put fresh attention on growth projects and perceived risk.
Scan how PPL’s capital plan compares with other regulated utilities that are gearing up for grid upgrades and data center demand using our curated list of 44 power grid technology and infrastructure stocks.
PPL now trades at a modest discount to the average analyst target, yet its internal value range appears far wider. Where does a fair anchor point really land before you price the new capital plan in?
Most Popular Narrative: 11% Undervalued
PPL closed at $35.67, while the analyst consensus Narrative on Simply Wall St points to a fair value of about $40.13 using a 7.24% discount rate. That gap frames the current debate over whether the new capital plan and data center exposure are fully reflected in the share price.
The accelerating growth in data center construction and new economic development, now supported by roughly 32 GW of advanced stage projects in Pennsylvania and a 13.7 GW pipeline in Kentucky, continues to point to sizable future load additions for PPL that are expected to require more infrastructure and support higher regulated revenue over time.
Major grid infrastructure upgrades and generation capacity expansions, updated to about US$5 to US$5.1b of planned capital investment in 2026 and roughly US$23b through 2029, are still set up to drive around 10% average annual rate base growth for PPL and to support the targeted 6% to 8% ongoing EPS growth through at least 2029.
See why 20 investors see PPL as 11% undervalued.
Result: Fair Value of $40.13 (UNDERVALUED)
Still, PPL’s story can be knocked off course if regulators take a tougher stance on cost recovery, or if large data center projects scale back or slip.
Find out about the key risks to this PPL narrative.
Another View on PPL’s Valuation
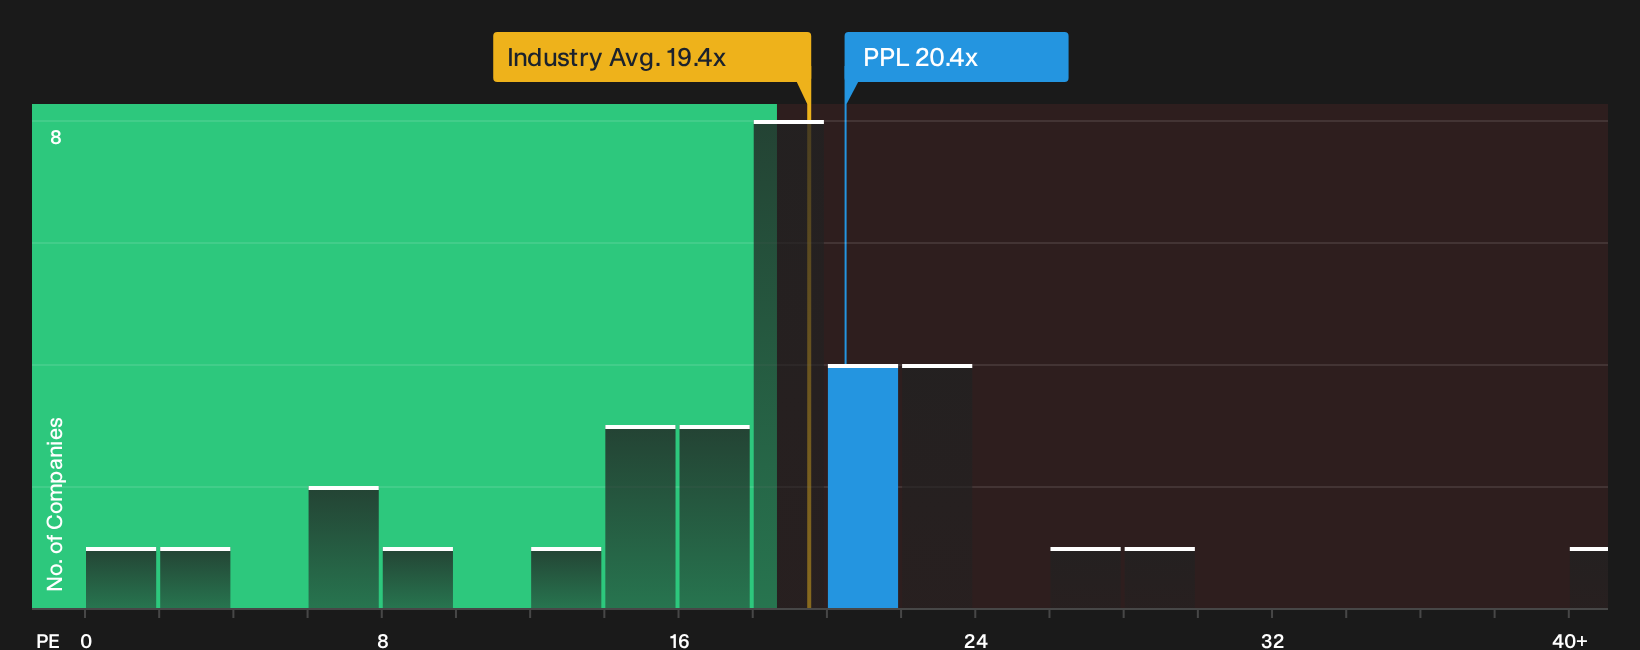
The first fair value anchor for PPL leans on analyst cash flow and earnings forecasts. A second lens uses today’s P/E of 20.4x against the US Electric Utilities industry on 19.3x and peers on 14.4x. A fair ratio of 22.5x hints at room for either compression or expansion. Which side of that gap feels more realistic to you?
To see how this pricing gap could close in either direction, and what the current ratio says about valuation risk, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on PPL’s valuation and growth plans can feel confusing. Review the underlying numbers, stress test your own thesis, then weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond PPL?
If PPL has sharpened your thinking, do not stop there. Use focused screens to spot opportunities that better fit your risk, income, or value goals.
- Target potential mispricing by scanning a curated set of companies that appear out of favor on fundamentals using the 32 high quality undervalued stocks.
- Boost your income focus by checking businesses that combine higher yields with resilient cash flows through the 6 dividend fortresses.
- Dial down portfolio stress by filtering for companies that carry lower risk scores and sturdier profiles inside the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com