


EN
Why Loblaw Companies (TSX:L) Is Getting Attention Today
Recent attention on Loblaw Companies (TSX:L) stems from its focus on grocery and pharmacy performance, tighter margin management, digital retail efforts, and capital discipline, as discount formats and private-label products attract value conscious shoppers.
Loblaw Companies has seen momentum build over recent months, with a 30 day share price return of 6.41% and a 90 day gain of 12.95%. This feeds into a 12.63% year to date share price return and a 1 year total shareholder return of 16.66%.
Scan how Loblaw Companies compares with other retailers leaning into value-focused shoppers by reviewing the hand-picked 7 high quality undervalued stocks in similar consumer sectors.
Bulls point to Loblaw Companies’ recent share price strength and value focused retail mix, while bears question how much is already reflected in CA$69.93. Which side does the current valuation support?
Most Popular Narrative: 1% Undervalued
Loblaw Companies closed at CA$69.93, set against an analyst consensus Narrative fair value of CA$70.91 that implies a small 1% gap and leans on a 6.46% discount rate in the model. The analyst consensus Narrative on Simply Wall St links that modest discount to specific growth projects and returns on capital rather than broad market optimism.
The Beyond businesses, including supply chain as a service contributing about $200m today with a target of $400m over time and a broader portfolio that generates roughly $400m of profit and is projected to reach about 20% of group earnings, offer Loblaw Companies additional profit pools outside core retail that can lift overall earnings and margin mix.
See why 49 investors see Loblaw Companies as 1% undervalued.
Result: Fair Value of CA$70.91 (ABOUT RIGHT)
Still, the Loblaw Companies story depends on regulators staying relatively hands off on pricing, and on newer profit pillars such as GLP 1 and Beyond businesses delivering as expected.
Find out about the key risks to this Loblaw Companies narrative.
Another View: Cash Flows Paint A Tougher Picture
Loblaw Companies may look almost fairly priced against analyst fair value of CA$70.91, but the Simply Wall St DCF model tells a different story. On that cash flow view, CA$69.93 trades well above an estimated value of CA$38.93, which raises the question of how much optimism is baked in.
For readers who want to see how that cash flow gap is built up line by line, Look into how the SWS DCF model arrives at its fair value..
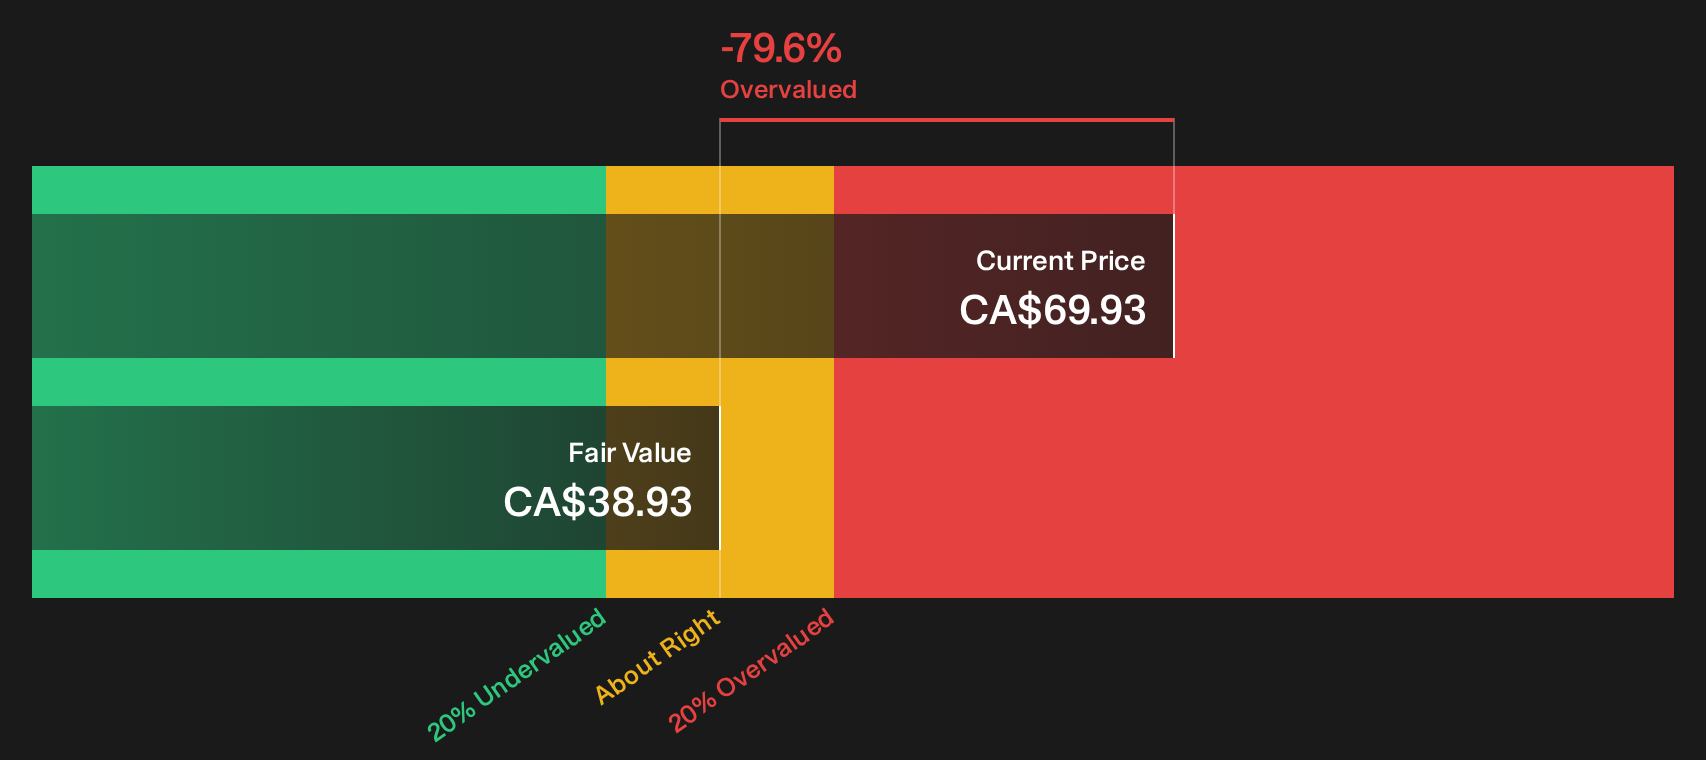
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Loblaw Companies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Loblaw Companies often create more questions than answers, so move quickly, review the data, and carefully weigh both the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Loblaw Companies?
If Loblaw Companies has your attention, do not stop your research here. Broaden your watchlist with a few focused screens that surface very different kinds of opportunities.
- Target resilient balance sheets and disciplined fundamentals by scanning a list of solid balance sheet and fundamentals (6 results) that can help you avoid fragile businesses before trouble shows up in the headlines.
- Hunt for mispriced potential by reviewing a curated 9 high quality undiscovered gems that many investors have not yet put on their radar.
- Stack your portfolio toward durability by studying a 9 resilient stocks with low risk scores that filters for companies with lower risk scores when conditions get choppy.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com