


EN
Quebecor (TSX:QBR.A) Posts Strong Q3 Results, Is The Stock Now Expensive?
Quebecor (TSX:QBR.A) has investors’ attention after third quarter 2026 results showed higher sales, net income, and earnings per share, along with an affirmed quarterly dividend of C$0.45 per share.
The latest earnings and dividend news has arrived alongside powerful share price momentum. Quebecor’s stock has posted a 30 day share price return of 27.17% and a year to date share price return of 51.80%, as investors respond to a three year total shareholder return of 179.13% and a five year total shareholder return of 228.59%. This suggests that enthusiasm has been building rather than fading.
Scan how Quebecor’s surge compares with other companies showing strong price action and fundamentals by checking the hand picked 7 high quality undervalued stocks right now.
Bulls point to Quebecor’s earnings strength and dividend commitment, while bears question how much of that story is now priced into the C$80 share price. Which side does the valuation actually favour next?
Price-to-Earnings of 17.8x: Is it justified?
Quebecor’s recent surge now comes with a P/E of 17.8x at a CA$80 share price, which screens as expensive relative to several valuation checks.
The P/E ratio compares the current share price to earnings per share, so it effectively shows how much investors are paying for each dollar of profit. For a telecom and media group like Quebecor, that figure often reflects how durable investors think its earnings base is and how confident they are in future cash flows.
On the current numbers, the market is assigning a richer multiple than both the estimated fair P/E of 11.8x and the peer and industry averages. That suggests investors are paying a premium for Quebecor’s earnings strength, even though the fair ratio points to a level the valuation could move toward if enthusiasm cools.
The P/E of 17.8x also sits above the Canadian telecom peer average of 16.9x and the global telecom industry at 14.8x, which is a clear valuation premium.
Explore the SWS fair ratio for Quebecor.
Result: Price-to-Earnings of 17.8x (OVERVALUED)
Still, Quebecor’s richer P/E and recent 52 week style surge leave little room for disappointment if competition tightens or telecom regulation turns less favourable.
Find out about the key risks to this Quebecor narrative.
Another View on Quebecor’s Valuation
The earlier P/E check paints Quebecor as expensive. Our DCF model points in the same direction. At CA$80, the stock trades above an estimated future cash flow value of CA$73.42, which suggests less margin for error if growth or profitability soften.
For investors who want to see how this cash flow view is built line by line, Look into how the SWS DCF model arrives at its fair value.
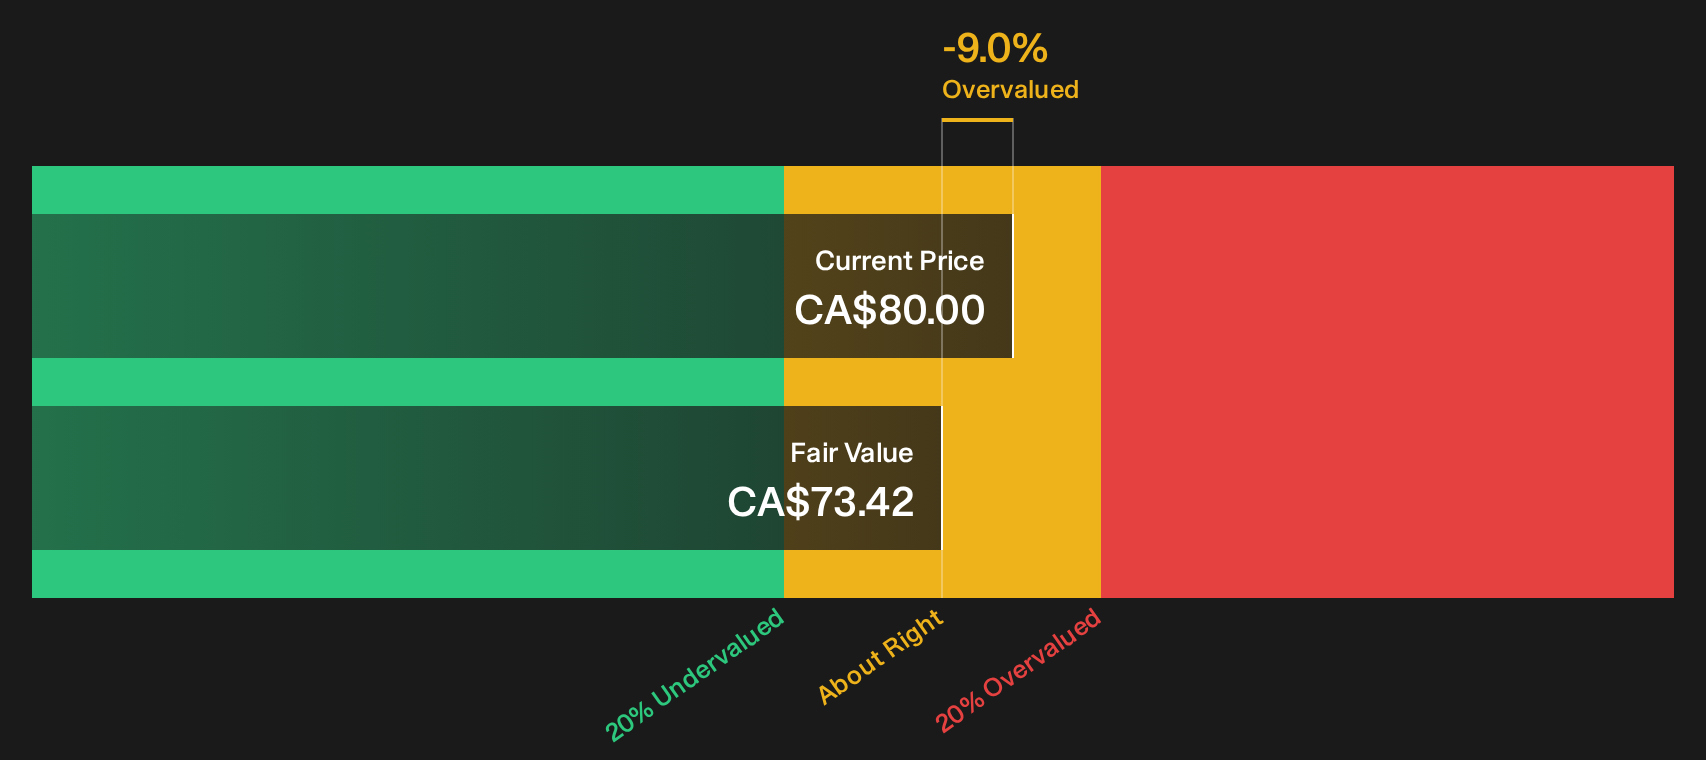
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Quebecor for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Quebecor so far. If you want to move past the headline metrics and act while sentiment is hot, weigh both sides of the story with the 3 key rewards and 1 important warning sign
Want more ideas beyond Quebecor?
Quebecor’s valuation debate is one piece of your portfolio puzzle, so cast the net wider and line up a few more potential candidates.
- Target resilient balance sheets and steady fundamentals by running your own screen through the list of solid balance sheet and fundamentals (6 results).
- Hunt for quality at a discount by checking companies that meet the criteria in the 7 high quality undervalued stocks.
- Lock in income focused opportunities by scanning high yielding candidates in the 3 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com