


EN
Learn Why The Bull Case For SSR Mining (TSX:SSRM) Could Change Following Steady Quarterly Results
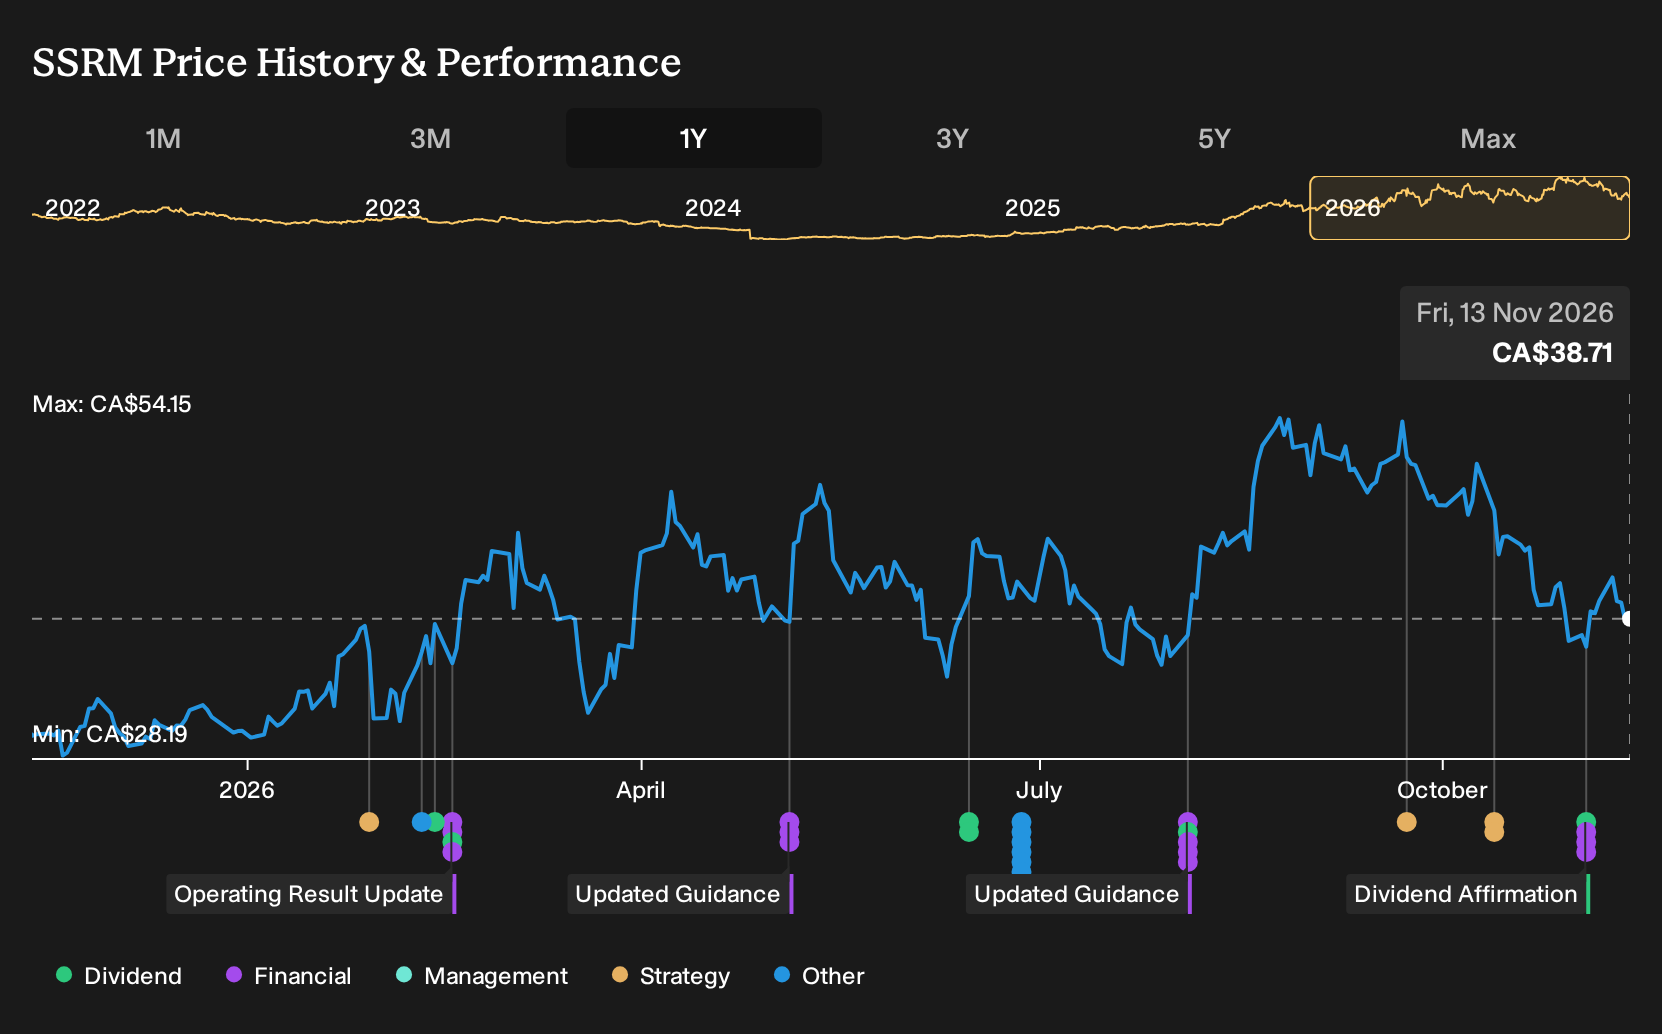
- SSR Mining reported third quarter 2026 output of 103,585 gold equivalent ounces with cost of sales of $1,755 per ounce and AISC of $2,527, alongside sales of $447.66 million and net income of $79.88 million, while confirming full-year production guidance and declaring a $0.03 per share dividend.
- The miner continued to return capital through both a quarterly dividend and a buyback that has already retired 7.81% of shares for $531.4 million. This reduces the share base as the Americas-focused portfolio absorbs higher sustaining costs.
- This article will examine how SSR Mining's investment narrative is influenced by steady production guidance alongside continued share repurchases under its capital return plan.
Scan how SSR Mining’s latest production, costs and buybacks compare to peers by reviewing our hand picked list of 33 elite gold producer stocks in one place.
SSR Mining Investment Narrative Recap
An investor in SSR Mining needs to be comfortable with an Americas focused precious metals portfolio that is carrying higher all in sustaining costs while still funding growth and capital returns. The third quarter update showed 103,585 gold equivalent ounces at AISC of US$2,527 per ounce, so the near term story hinges on keeping production steady while managing those elevated unit costs.
The analyst consensus Narrative on Simply Wall St leans heavily on SSR Mining converting reserves at sites like Marigold and Seabee into resilient output and cash flow. Higher sustaining and growth capital, together with the loss of Turkish volumes, leaves execution risk as the main short term concern, although the latest results do not appear to change that risk reward balance in a material way.
The most relevant announcement for that thesis is management reaffirming full year 2026 production guidance, with expected gold output of 355,000 to 420,000 ounces and 450,000 to 535,000 gold equivalent ounces. That confirmation matters because it anchors the idea that the refocused Americas portfolio can underpin volumes even as SSR Mining absorbs higher fuel and input costs.
Guidance also feeds directly into the longer term catalysts flagged in the analyst consensus Narrative on Simply Wall St, such as organic projects at Marigold and Seabee and the planned addition of Converse next to Marigold. If SSR Mining keeps hitting its production ranges while progressing those projects within the planned US$230 million to US$235 million sustaining capital envelope, the main question for investors becomes how much cost relief and mine life delivery the business can achieve over the next few years.
SSR Mining's outlook projects revenue of US$2.5b and earnings of US$776.8 million by 2029. This profile assumes 7.2% yearly revenue growth and an earnings increase of about US$209 million from current earnings of US$567.8 million.
Uncover why SSR Mining's fair value signals a 50% potential upside to its current price that could close faster than many investors expect.
Exploring Other Perspectives
One alternate view on SSR Mining leans heavily on cost pressure. The most cautious analysts were working off 8.2% expected yearly revenue growth and earnings of about US$711.9 million by 2029, yet still saw limited upside. These forecasts all predate the latest results, so you may want to compare how that cost focused story holds up now.
Explore 4 other SSR Mining fair value estimates, including one that suggests it could be worth just CA$52.04!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your SSR Mining research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for SSR Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SSR Mining's overall financial health at a glance.
Looking For More Investment Ideas Beyond SSR Mining?
If the SSR Mining story has sharpened your thinking but you want a wider watchlist, the Simply Wall St Screener can help you quickly surface other listed businesses that match the kind of risk and return profile you prefer.
- If you want potential mispriced opportunities with quality foundations, start with a curated set of 7 high quality undervalued stocks that already screen well on both balance sheet strength and cash generation.
- If capital preservation and a smoother ride matter most to you, narrow your hunt to 9 resilient stocks with low risk scores that score well on resilience and risk controls.
- If you prefer companies that can fund growth from their own resources, focus your search on a list of solid balance sheet and fundamentals (6 results) so you are not solely relying on generous credit markets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com