


EN
Mainstreet Equity (TSX:MEQ), Why Is Its Latest Update Drawing Attention?
Mainstreet Equity (TSX:MEQ) is back in acquisition mode after reporting higher occupancy, increased net operating income, stronger funds from operations, and lower vacancy. This combination is sharpening the market focus on future cash flow support for today’s valuation.
The share price at about CA$178.92 has moved up 5.35% on a 30 day share price return and 4.86% over 90 days, yet the year to date share price return is slightly down 2.19% and the 1 year total shareholder return has declined 3.12%. The 3 and 5 year total shareholder returns of 27.31% and 59.24% indicate that longer term holders have still been rewarded as Mainstreet Equity’s renewed acquisitions and stronger operations reset expectations for what cash flows might support in future.
Compare Mainstreet Equity's renewed acquisition story with other value-focused real estate operators by scanning our hand picked 7 high quality undervalued stocks, which pair cash generation with balance sheet strength.
Mainstreet Equity now trades at about CA$178.92, while analyst targets and intrinsic estimates sit noticeably higher. Is that gap a genuine margin of safety, or a signal that expectations have run ahead of reality?
Price-to-Earnings of 9.5x: Is it justified?
On simple numbers, Mainstreet Equity trades on a P/E of 9.5x, which lines up with a share price of CA$178.92 that screens as cheaper than many real estate peers and also below some intrinsic estimates tied to future cash flows.
The P/E multiple compares what investors currently pay for each dollar of earnings to what similar businesses command. For a mid market residential landlord that leans on acquisition, redevelopment and repositioning in Western Canada, earnings power is central because rent, occupancy and financing costs all filter through to that bottom line.
There is a twist, though. Earnings for Mainstreet Equity are shaped by large one off items and a CA$103.4m gain in the last twelve months. Analysts still forecast an average decline in profits of 13% a year over the next three years. In that context, a 9.5x P/E that sits below the North American real estate average of 12.1x but above the immediate peer group on 9.1x suggests the market is paying a premium to close peers yet a discount to the broader sector. The estimated fair P/E of 16.6x is materially higher again. This is the level the ratio could move toward if investors eventually price Mainstreet Equity more in line with that regression based fair value.
Explore the SWS fair ratio for Mainstreet Equity.
Result: Price-to-Earnings of 9.5x (UNDERVALUED)
Still, the narrative around Mainstreet Equity can crack if acquisition returns disappoint or if any profit softness makes that 9.5x P/E look less forgiving.
Find out about the key risks to this Mainstreet Equity narrative.
Another View: Mainstreet Equity Through Our DCF Lens
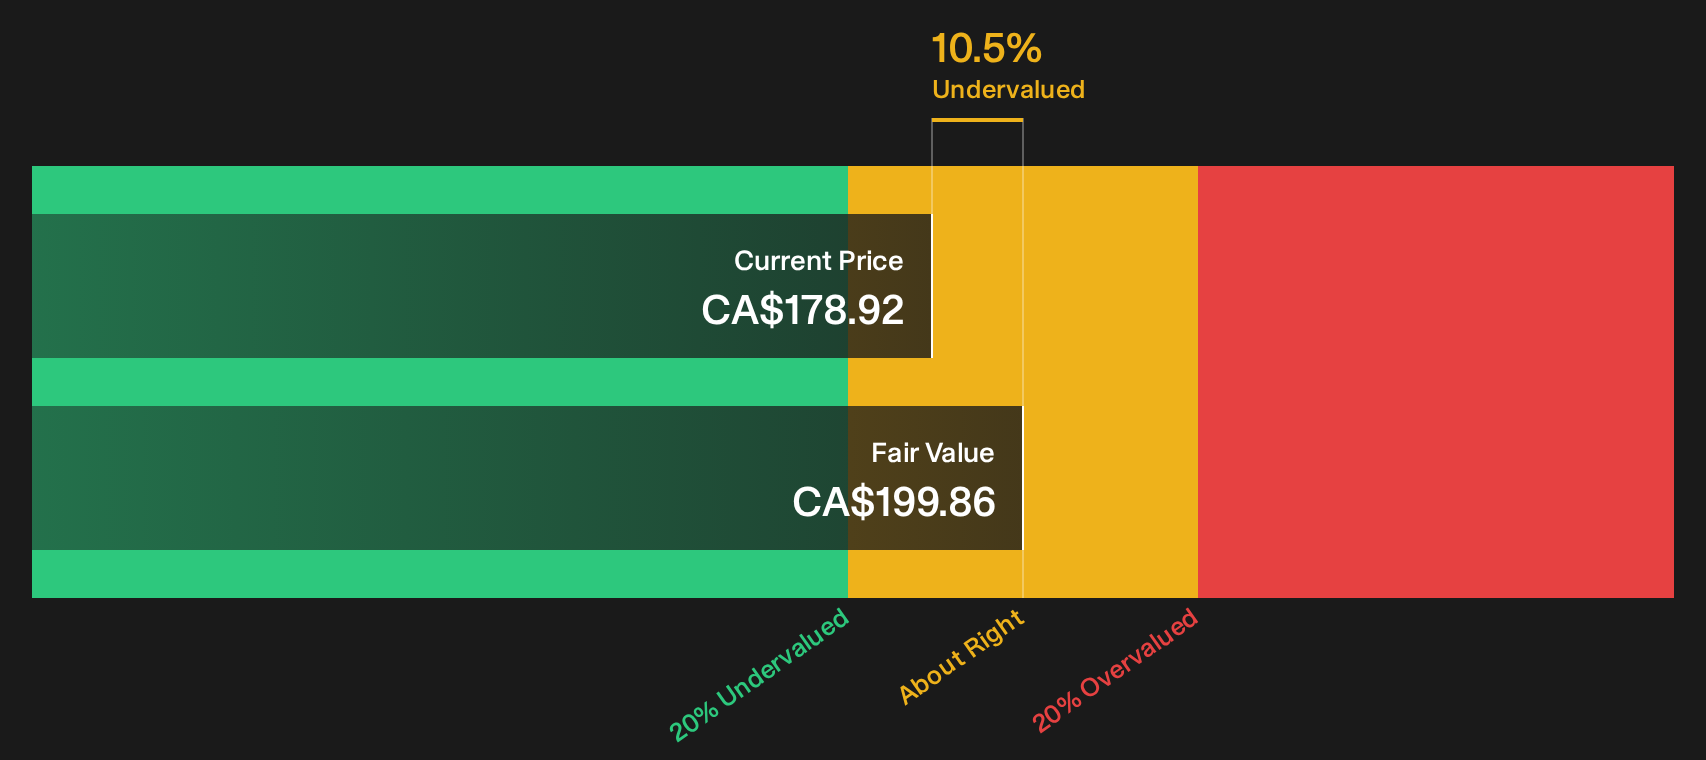
The picture shifts once you put Mainstreet Equity through the SWS DCF model. At about CA$178.92, the share price sits roughly 10.5% below an estimated future cash flow value of CA$199.86. This points to an undervalued result based on projected cash generation rather than reported earnings multiples.
That kind of discount can look like room for upside or simply compensation for risks around earnings forecasts, interest coverage and acquisition execution. The real question for you is whether those future cash flows appear resilient enough to close that gap.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mainstreet Equity for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution around Mainstreet Equity feels finely balanced, move quickly to review the underlying data and form your own stance, then round out your view by checking the 3 key rewards and 4 important warning signs
Looking for more investment ideas beyond Mainstreet Equity?
If Mainstreet Equity has sharpened your focus on value, do not stop here. Broaden your watchlist now so you are not late to the next opportunity.
- Target fresh potential by scanning a 9 high quality undiscovered gems that highlights under-the-radar businesses with strong fundamentals.
- Prioritise staying power by reviewing a list of solid balance sheet and fundamentals (6 results) that filters for companies with healthier financial footing.
- Reduce portfolio stress by studying a 9 resilient stocks with low risk scores that concentrates on resilient stocks with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com