


EN
3 Semiconductor Stocks Investors May Prefer Over Nvidia Right Now
Nvidia’s shock leadership shake up and fresh scrutiny on its AI empire has pushed investors to ask where the money might move next. When a giant stumbles or even just pauses, capital often hunts for other chip makers that could absorb spend, attention, or risk. This article walks through three large non Nvidia semiconductor stocks from our screener that appear positively exposed to this moment and explains what might make each worth a closer look.
The stocks covered below are just a starting sample, and the full screen surfaced 54 more large semiconductor manufacturers and foundries with equally compelling narratives that are not discussed here. To go broader and identify candidates that best fit your own thesis, head straight into the Non-Nvidia Global Semiconductor Manufacturers and Foundries screener.
Powerchip Semiconductor Manufacturing (TWSE:6770)
Overview: Powerchip Semiconductor Manufacturing runs pure-play foundry and manufacturing services for integrated circuits, producing advanced logic and AI related chips for global customers.
Operations: Powerchip Semiconductor Manufacturing generates NT$55.2b from semiconductors, with revenue concentrated in Taiwan (NT$27.5b), China (NT$11.0b), the United States (NT$11.8b) and other regions.
Market Cap: NT$268.6b
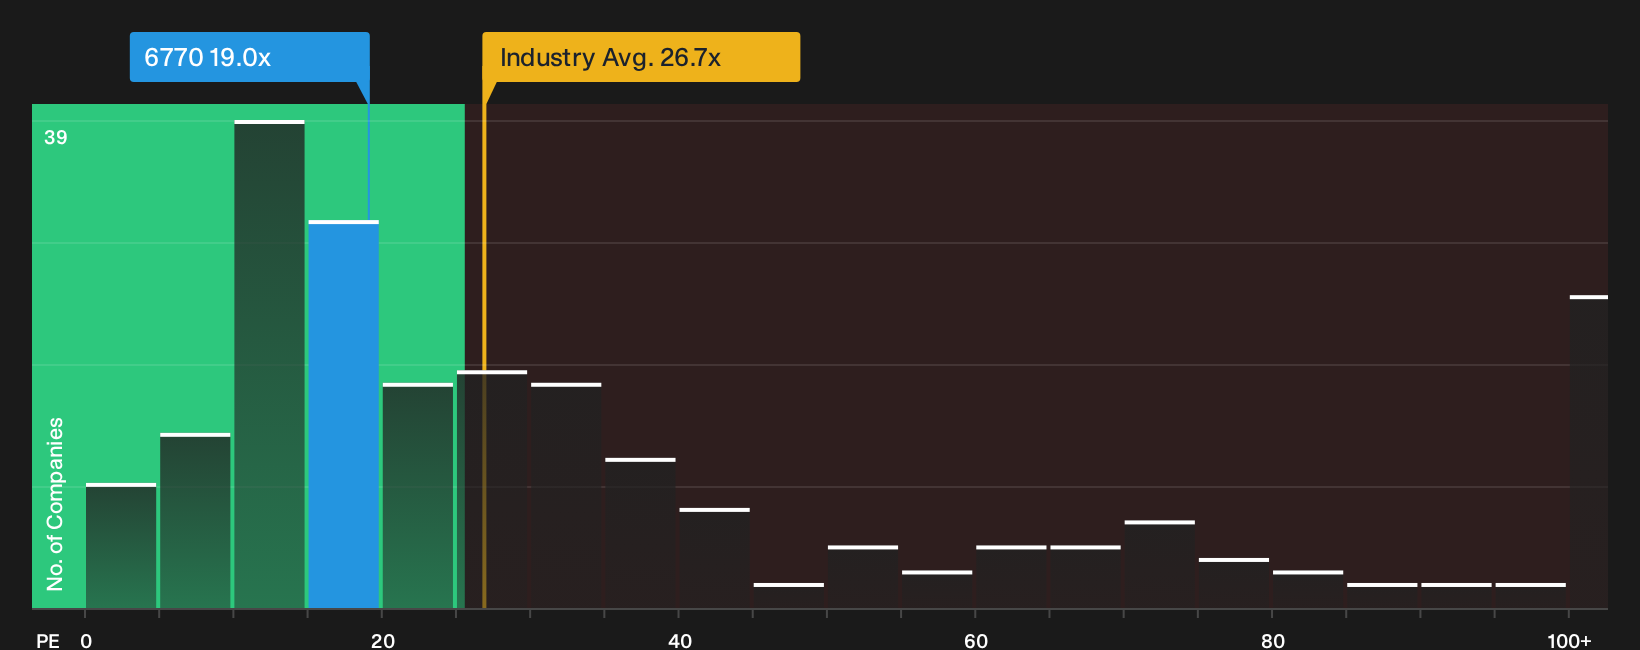
Powerchip Semiconductor Manufacturing provides pure-play foundry exposure at a time when Nvidia’s role in AI supply chains faces fresh questions. The group is profitable, carries a P/E below local peers, and reports year-on-year improvements in sales and earnings as customers broaden chip sourcing. A key issue is how capacity decisions interact with potential pressures on future AI and logic orders.
Those capacity choices and AI order risks are exactly why it is worth scanning the 4 key rewards and 2 important warning signs before this story moves on.
ACM Research (ACMR)
Overview: ACM Research supplies wet cleaning, plating, furnace and advanced packaging tools that chip manufacturers use to build logic and AI related semiconductors.
Operations: ACM Research generates about US$1.14b from semiconductor equipment and services, with essentially all revenue reported from Mainland China.
Market Cap: US$3.5b
ACM Research matters for this Non Nvidia semiconductor screen because it sells the tools that foundries and logic manufacturers need when they add capacity for AI chips and high bandwidth memory, and the analyst consensus Narrative on Simply Wall St highlights how that equipment focus ties directly into the current build out cycle.
"Advanced AI and high bandwidth memory demand is driving larger die sizes and more complex 2.5D and 3D integration, and ACM Research is already booking production and evaluation orders for panel-level electroplating and reporting triple digit advanced packaging revenue growth."
What really moves the needle for ACM Research now is how one unresolved pressure on future AI focused equipment demand filters through to margins.
That margin tension is exactly what the full narrative for ACM Research unpacks, highlighting where ACM Research could be decoupling equipment demand and profitability from Nvidia centered AI cycles.

MediaTek (TWSE:2454)
Overview: MediaTek designs and supplies multimedia and application processors that power smartphones, tablets, TVs and other connected devices worldwide.
Market Cap: NT$6,580.3b
MediaTek slots into this Non Nvidia semiconductor screen as a major designer of AI capable chips for edge devices. The bullish analyst Narrative on Simply Wall St argues that its data center and Smart Edge roadmap could matter far more if customers spread their AI bets beyond a single supplier.
"Cloud AI customers are increasing capital expenditure, and MediaTek is already executing its first AI accelerated ASIC, with updated guidance for data center revenue to exceed US$2b in 2026 and to scale further in 2027 as the initial project enters production in 4Q26, which targets higher data center revenue and operating income."
What really shapes the long term outcome is how one untested assumption about AI driven earnings scale collides with the cost of securing capacity.
That trade off is exactly what the full narrative for MediaTek unpacks, showing how MediaTek could turn capacity commitments into accelerating AI earnings power while framing the main risks clearly.

Seeking Alternatives Before Momentum Flies
Fresh ideas often move first, and markets often reward the early capital that spots a breakout while it is still under the radar. Do not get caught focusing on yesterday’s stories. Scan new themes before the crowd, then decide whether to get in early.
- Identify cash rich operators that may keep their footing when others wobble by running a quick pass over the list of solid balance sheet and fundamentals (200 results).
- Explore early AI momentum where profits already matter by scanning the curated group of 42 profitable AI stocks that aren't just burning cash before those stories attract wider attention.
- Review companies that could benefit from the next infrastructure buildout cycle by examining the under the radar names inside the 44 power grid technology and infrastructure stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com