


EN
How Strong Cresemba Sales Will Impact Basilea Pharmaceutica Stock (SWX:BSLN)
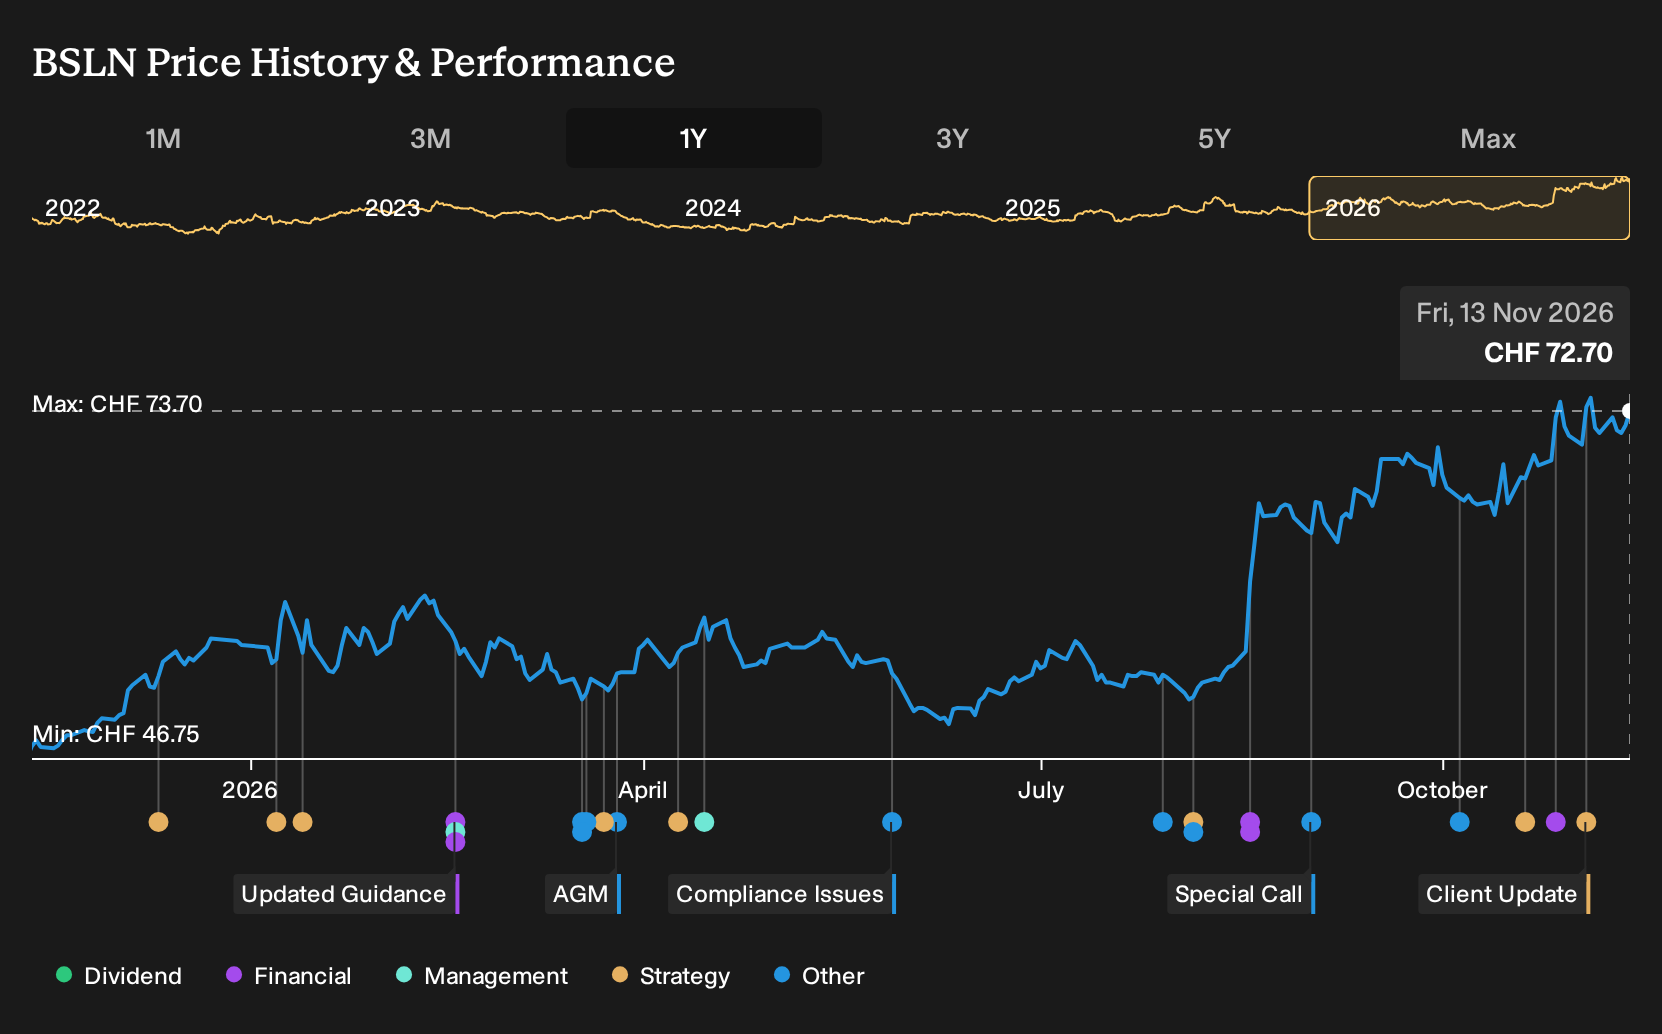
- Basilea Pharmaceutica reported that strong European sales of Cresemba by license partner Pfizer triggered a US$37.5 million milestone payment, with global in-market Cresemba sales reaching US$817 million for the 12 months to June 2026 and a 25% year-on-year growth rate.
- The fact that Cresemba has become the largest branded antifungal for invasive fungal infections worldwide highlights how a single successful asset can meaningfully influence Basilea Pharmaceutica’s revenue mix and negotiating leverage with partners.
- The focus now turns to how Basilea Pharmaceutica’s investment narrative is affected by Cresemba’s milestone-driven cash inflow and expanding commercial footprint.
Scan beyond Basilea Pharmaceutica and compare Cresemba-driven momentum with other specialty pharma players by reviewing the 566 high quality undiscovered gems that analysts may be overlooking.
What Is Basilea Pharmaceutica's Investment Narrative?
For Basilea Pharmaceutica, the core belief is simple. You need to think Cresemba and the emerging anti infective portfolio can support a durable, profitable mid sized biotech. The recent US$37.5 million milestone and US$817 million of global Cresemba sales feed directly into that story. Extra cash from Pfizer helps fund phase 3 work on assets like fosmanogepix and ceftibuten ledaborbactam etzadroxil without the same pressure on new financing, in a business that already carries 100% higher risk funding sources.
In the short term, the key swing factors are Cresemba demand and pricing, Zevtera execution, and how tightly Basilea Pharmaceutica manages costs after net income of CHF52.4 million on CHF247.4 million of revenue and a 21.2% margin that is lower than last year. The milestone strengthens the near term cushion, but it does not remove issues like volatile recent share moves, revenue that analysts expect to decline slightly over the next 3 years, or a P/E of 17.2x that screens as cheap versus the Swiss market yet not cheap versus European biotech peers.
Even so, there is one uncomfortable angle in the Cresemba centric story that deserves a closer look...
There's only one way to know the right time to buy, sell or hold Basilea Pharmaceutica. Head to Simply Wall St's company report for the latest analysis of Basilea Pharmaceutica's Fair Value.
Exploring Other Perspectives
Highest case analysts lean into one big catalyst. They expect Basilea Pharmaceutica to use drugs like fosmanogepix and ceftibuten ledaborbactam to reshape the story, even though their own models before this Cresemba milestone pointed to revenue of CHF214.4 million and earnings of CHF10.3 million by 2029. That more optimistic camp still shows how far opinions can stretch, so it makes sense to weigh several viewpoints and decide which story you find most convincing.
Explore 2 other Basilea Pharmaceutica fair value estimates, including one that suggests as much as 37% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Basilea Pharmaceutica research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Basilea Pharmaceutica. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Basilea Pharmaceutica's overall financial health at a glance.
Looking For More Investment Ideas Beyond Basilea Pharmaceutica?
Once you have formed a view on Basilea Pharmaceutica, it can help to cross check that thesis against other opportunities using the Simply Wall St Screener. That way you can compare risk, quality, and income potential across a wider watchlist instead of viewing Basilea Pharmaceutica in isolation.
- For investors who want income to play a bigger role in returns, start with reliable payers by reviewing 219 dividend fortresses that already meet your yield threshold.
- If capital preservation is front of mind, focus on steadier businesses by scanning a 211 resilient stocks with low risk scores that scores well on volatility and financial strength.
- When the goal is to back companies with cleaner finances, filter for sturdier balance sheets by using a list of solid balance sheet and fundamentals (200 results) as a base list for deeper research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com