


EN
The Bet Eurofins Scientific Holders Made
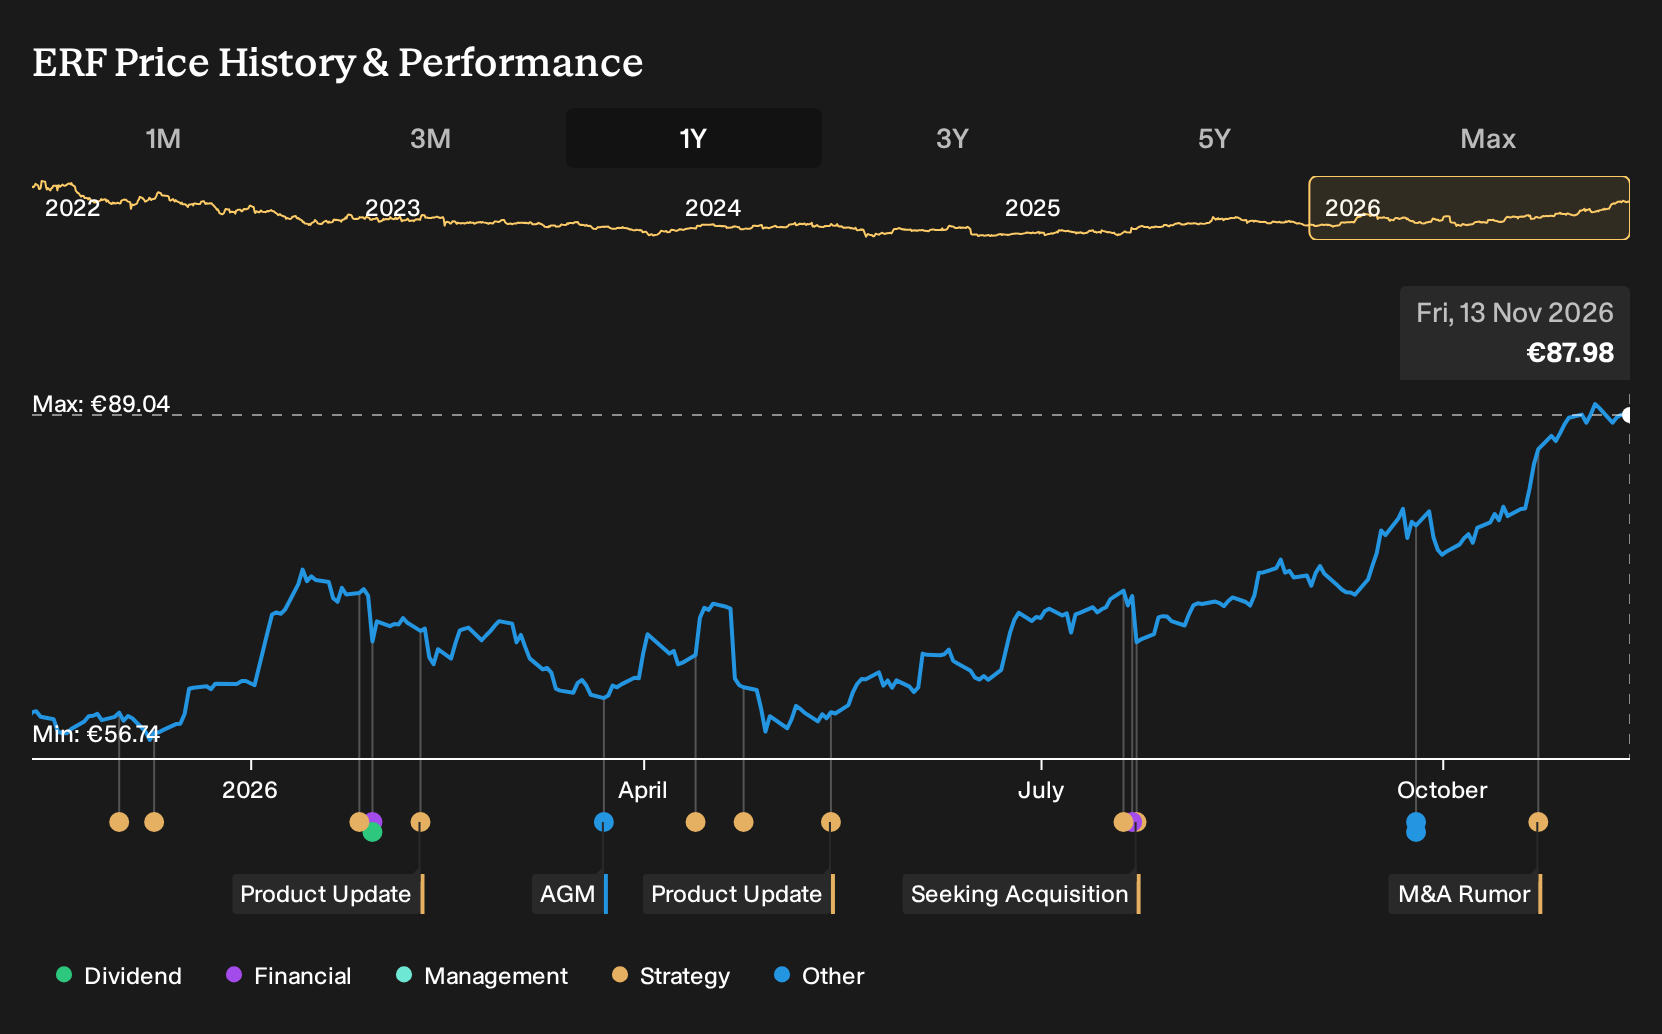
If you only glanced at Eurofins Scientific’s headlines, the story looked messy. Organic growth in 2026 started slowly, H1 revenue was close to flat year on year, and management kept spending heavily on laboratories, digital systems, and acquisitions. Holding Eurofins Scientific over the past year would have returned 51.0%, including dividends. If you had seen that outcome in advance, how would you have weighed those upfront execution risks against the payoff that followed?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Eurofins Scientific is not the only name tied to this theme. Zero in on 123 healthcare AI stocks and compare how each one is priced.
The Two Eurofins Scientific Stories Investors Were Arguing About
The shares cost €59.5 at the start of the period, and Eurofins Scientific sat between two very different stories about where the heavy investment might lead.
The bullish narrative saw fair value at €63.93, based on the idea that spending on automation, digitalization, and a hub and spoke lab network could improve efficiency and lift net margins, even while structural challenges and integration risks stayed firmly on the radar.
The bearish view set fair value at €46 and focused on pressure from automation, AI driven alternatives, insourcing, and rising regulatory costs that could weigh on traditional lab revenues and squeeze profitability over time.
What The Eurofins Scientific Results Put To The Test
The biggest development was Eurofins Scientific’s H1 2026 results. Revenue moved from €3,612m in H1 2025 to €3,701.4m, while net income rose from €219m to €272.8m and net margin went from 6.1% to 7.4%. That tilt toward higher profitability supported the bullish margin story, although the ongoing heavy capex and acquisition program meant the cautious camp on capital intensity still had evidence in its corner. Overall, the period cut both ways.
The useful takeaway is simple. When a thesis hangs on efficiency and digitalization, do not just watch headline growth. Track net margin and absolute profit in each set of results and see whether the improvement actually shows up in the numbers.
What Eurofins Scientific’s Price Now Asks You To Believe
Eurofins Scientific now trades at €87.98, after a 51.0% move over the past year. The analyst consensus Narrative on Simply Wall St currently places its Fair Value below that price, framing today’s level as already baking in a confident outcome.
That Narrative stresses cash generation and execution on lab consolidation and portfolio reshaping. Anyone paying today’s price is effectively assuming those projects support higher margins without BioPharma weakness or regulatory shifts undermining that story.
"The current valuation for Eurofins Scientific implies the share price already reflects a fairly valued bullish view that margin expansion, stronger free cash flow and steady BioPharma and regulated testing demand will be sustained over time. What Eurofins Scientific Does: Eurofins Scientific provides analytical testing and laboratory services for clients across life sciences, food and consumer products, environmental, forensic and clinical markets, primarily earning revenue from fee based testing and related services."
The price and this Narrative do not agree. → Uncover what this Narrative says Eurofins Scientific is actually worth
Which Company Could Surprise You Next?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 46% below our estimate - uses regional mine teams and AI tools to stabilise production and cash flows.
- Company 2 - 42% below our estimate - folds acquired factories into clusters that expand customers’ outsourced manufacturing capabilities and flexibility.
- Company 3 - 33% below our estimate - converts guided residential launches and industrial parks into contracted presales and recurring service revenues.
Three companies from the same screener. Open the full list of 199 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com