


EN
How Return To Profit Has Changed Its Investment Story At Power Integrations (POWI)
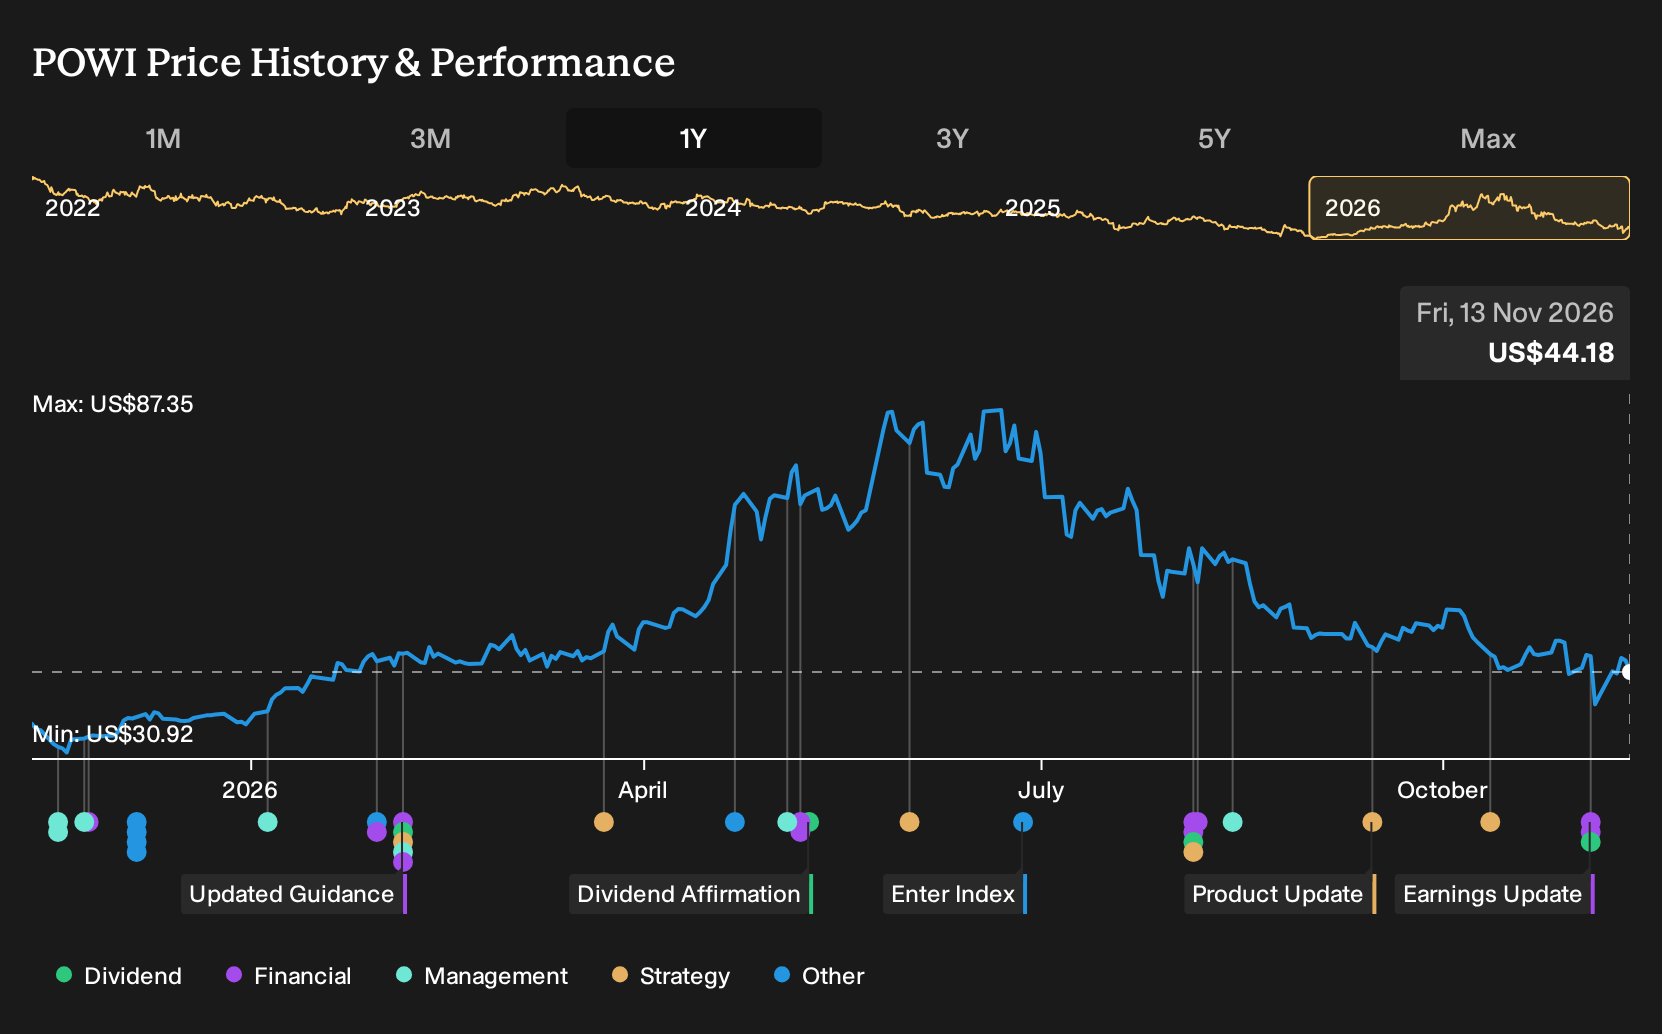
- Power Integrations reported third quarter 2026 sales of US$125.48 million and net income of US$18.32 million, then issued fourth quarter revenue guidance of US$118 million to US$126 million and affirmed a quarterly dividend of US$0.215 per share payable on December 31, 2026.
- The swing from a prior year quarterly net loss to earnings, combined with maintained cash returns through the dividend, highlights how Power Integrations is currently balancing profitability, capital discipline, and demand visibility across its power conversion portfolio.
- This raises the question of how Power Integrations' return to quarterly profitability could reshape the existing investment narrative around its growth ambitions.
Power Integrations Investment Narrative Recap
To own Power Integrations, you need to believe its power conversion products can keep winning sockets in areas like EVs, AI data centers, renewables, and industrial gear while it manages a still meaningful consumer appliance footprint. The analyst consensus Narrative on Simply Wall St leans on that shift toward higher value GaN and gate-driver content as the main earnings engine.
The latest quarter shows the business back to making money, with US$18.32 million of net income and US$0.32 in diluted EPS, and guidance that brackets recent sales levels. That supports near term confidence but does not remove the key risk that any earnings disappointment could bite hard given a high P/E and past multi year profit pressure.
The fourth quarter 2026 revenue outlook of US$118 million to US$126 million is the update that matters most right now. It sets a near term bar for how resilient demand is across consumer, industrial, EV, and data center customers after the return to profitability in the third quarter.
If the firm can stay within that range while continuing to push high voltage GaN and gate driver programs, it supports the earnings acceleration that analysts in the analyst consensus Narrative on Simply Wall St are looking for. Falling short would quickly refocus attention on valuation risk, softer appliance demand, and the longer run declines previously seen in revenue and EPS.
Power Integrations' narrative projects US$672.3 million revenue and US$136.2 million earnings by 2029. This is based on analysts assuming 13.8% yearly revenue growth and implies earnings rising by about US$91.5 million from US$44.7 million today.
Uncover why Power Integrations' fair value indicates a 37% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternative view focuses on valuation risk. The most bearish analysts already questioned whether Power Integrations could justify its high P/E, even while penciling in about US$748.7 million of revenue and US$175.9 million of earnings by 2029. Those forecasts were set before this quarter, so opinions may change as new data becomes available.
Explore 3 other Power Integrations fair value estimates, including one that suggests as much as 43% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Power Integrations research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Power Integrations. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Power Integrations' overall financial health at a glance.
Looking for more investment ideas beyond Power Integrations?
Once you have formed a view on Power Integrations, it can help to line it up against a wider watchlist so you can see where risk, income potential, and valuation appeal look more attractive elsewhere.
- If capital preservation is near the top of your list, start with companies that currently screen well on balance sheet strength using our list of solid balance sheet and fundamentals (24 results).
- For investors hunting for mispriced quality, compare Power Integrations with companies that look attractively valued on key metrics through the 32 high quality undervalued stocks.
- If reliable income matters to your plan, build a shortlist of higher yielding stocks with resilient payouts using the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com