


EN
What Investors Got Wrong About Daqo New Energy Before A 67% Slide
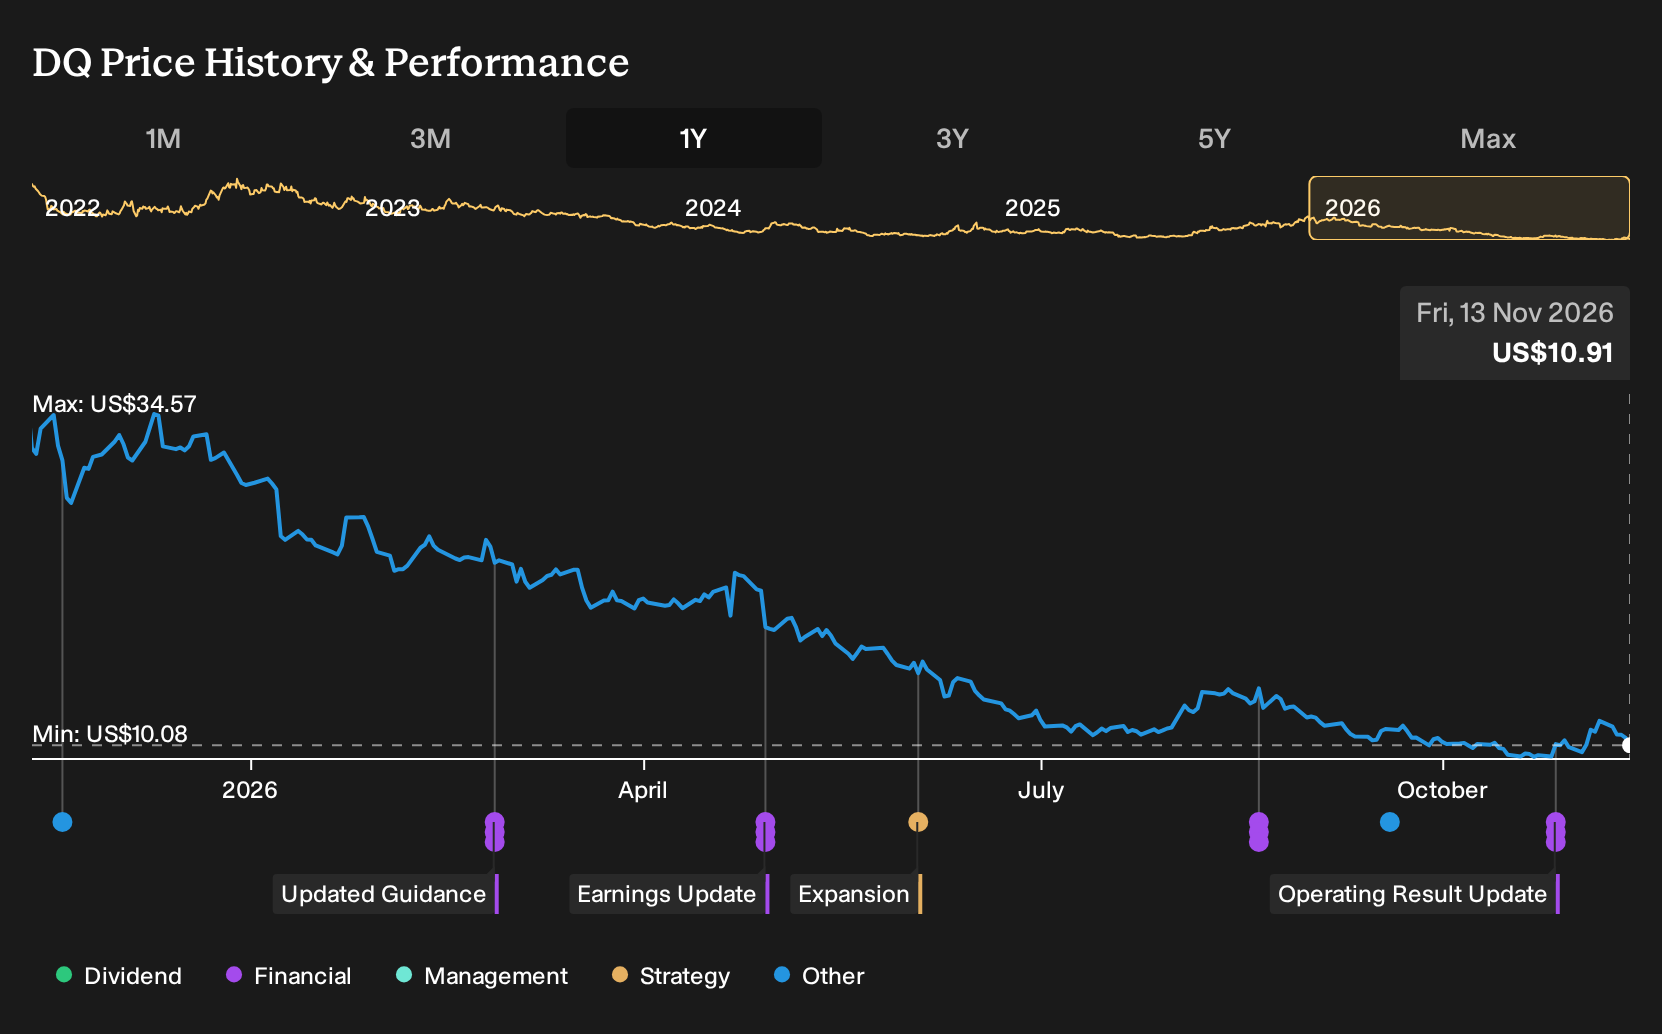
If Daqo New Energy looked like a pure solar recovery story at the outset, the actual payoff for patient holders told a very different story. Investors who held Daqo New Energy over the past year are down 67.5%, including dividends. At the same time, reported revenue and profit both declined year on year, and losses widened. If you were weighing that investment a year ago, which warning signs around pricing power and cash burn were already on the table?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The move put Daqo New Energy in the middle of this trade. Scan 44 power grid technology and infrastructure stocks for other companies exposed to it.
The Argument You Would Have Been Weighing Up On Daqo New Energy
The shares cost US$31.72 at the start of the period. Anyone considering Daqo New Energy then had to choose between two very different explanations for that quote on the screen.
On the bullish side, one Narrative put Fair Value at US$37, or 17% above the start price, based on revenue growing 76.9% a year and profit margins swinging from heavy losses to 13.6%.
The more cautious Narrative pointed to a Fair Value of US$26.58, 16% below the start price, assuming 57.5% annual revenue growth but warning that reliance on policy support could still leave Daqo with fragile pricing power.
What The Evidence Did To The Daqo New Energy Story
Daqo New Energy committed about RMB 6b to an AI data center energy hardware base and kept talking about diversification, which backed the bullish focus on new end markets. Reported results told a harsher story. Q3 2026 revenue of US$194.2m was lower than Q3 2025, and the net loss deepened, with net margin moving from -6.1% to -27.2%. Overall, the evidence leaned toward the cautious case.
The live issue for readers is not the project headlines. It is whether high growth and future margin repair were assumed or earned. For a different stock, track how quickly heavy investment shows up in revenue, profit and especially net margin, then judge if the original payout story still matches the cash coming through the door.
What Daqo New Energy's Lower Price Asks You To Believe
Daqo New Energy now trades at US$10.91, far below where investors started one year ago. The analyst consensus Narrative on Simply Wall St places Fair Value above that level, built on the idea that pricing discipline and a cash rich balance sheet can still support the business.
That Narrative leans on tighter enforcement against below cost selling and a future AI data center power business. A buyer today would need to believe those regulatory shifts and the new power infrastructure arm can offset industry oversupply and current cash burn over time.
"Recent regulatory focus on enforcing price law and eliminating below cost polysilicon sales, including industry initiatives co signed by Daqo New Energy, points to a shift toward more disciplined pricing that can support future revenue and net margins."
One Narrative disagrees with today's price. → See where this Narrative says Daqo New Energy should trade
One Step Beyond Daqo New Energy
Daqo New Energy points you toward power hungry computing. The next question is what quietly keeps that digital traffic moving.
Every AI cluster, trading system and streaming platform leans on reliable connectivity. When data volumes rise, pressure lands on the plumbing.
One large specialist designs chips and software that help data move quickly, stay secure and remain manageable across complex networks.
Its gear supports everything from cloud backbones to on premises systems, linking storage, servers and security into a single digital infrastructure.
If demand for computing keeps broadening, that connective tissue could matter as much as the headline chips everyone talks about.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 88% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com