


EN
What Grupo Cibest Holders Bought Into
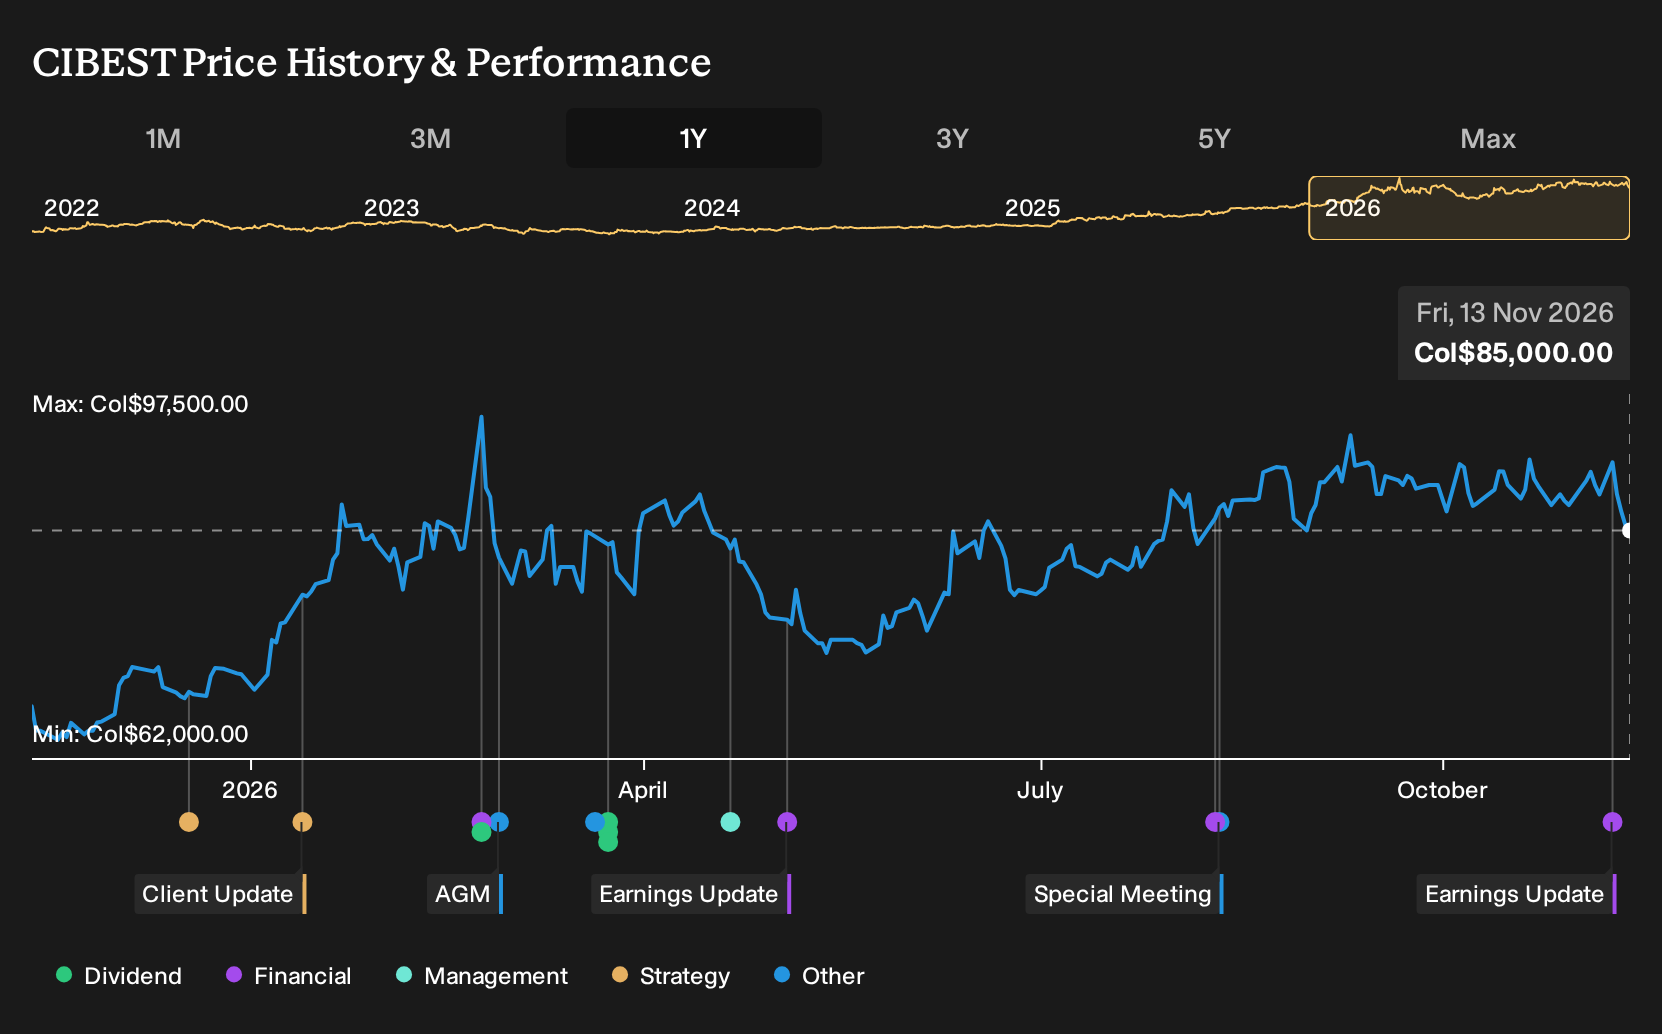
Holding Grupo Cibest over the past year would have returned 42.4%, including dividends. If you had bought on 13 November 2025, you would have been choosing between a bullish camp arguing Nequi and digital banking could justify a fair value 161% above the start price and a more cautious view that sat 12% below it. With Q3 2026 showing higher revenue but a lower net income margin, which thesis really fit the evidence on day one?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
If the move has made Grupo Cibest harder to judge, start where the gap is still open and scan 199 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On Grupo Cibest
The shares cost COP64,520 at the start of the period, and anyone looking at Grupo Cibest then had two very different but plausible stories to consider.
On the bullish side, one narrative saw Nequi and wider digital banking as the growth engine. This view tied that to a Fair Value of COP168,638 and assumed revenue growth of 15.1% a year.
The more cautious view pointed to a Fair Value of COP57,045 and stressed risks from rising digital competition, paired with an assumed future P/E of 12.5x.
What The Results Changed For Grupo Cibest
The key fact was simple. Grupo Cibest reported Q3 2026 revenue of COP6,653,127m alongside net income of COP2,080,353m, which left the net margin at 31.3% compared with 32.5% a year earlier. That combination of higher sales and a thinner margin cut both ways for the original bullish and cautious cases built around Nequi and digital banking.
The hinge assumption here was margin resilience. When you test a growth story elsewhere, do not just track top line. Compare the shift in net margin directly with any forecast that leans on future profitability.
What Today's Price Already Assumes For Grupo Cibest
Grupo Cibest now trades at COP85,000, up 42.4% over the past year. The bearish analyst Narrative on Simply Wall St places its Fair Value below that level, arguing the current tag already prices in demanding profitability and return assumptions.
The crux is digital banking. For today’s price to hold up, a buyer must believe Nequi, Wompi and Wenia can grow without pushing funding costs, credit losses or operating expenses beyond recent guidance ranges.
"The numbers imply the share price already bakes in continued high teens to low 20s ROE, with recent guidance ranges around 18% to 22% leaving limited room for upside if loan growth, NIM or credit quality soften."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Find Your Own Contrarian Opportunity
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 29% below our estimate - uses fast payback new boutiques and rising digital traffic to widen merchandising influence.
- Company 2 - 33% below our estimate - adds maintenance-focused sales staff to convert more equipment owners into recurring service relationships.
- Company 3 - 36% below our estimate - runs large gold reserves with higher-cost operations and sensitivity to regional political conditions.
Three companies from the same screener. Open the full list of 200 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com