


EN
Learn Why The Bull Case For Trimble (TRMB) Could Change Following AI Construction Rollout
- Trimble has rolled out a broad set of Trimble Connect AI features across design, build and operate phases, tying together project data, field hardware, machine telemetry and financial systems, while partners like Outbuild are linking Trimble software into their own planning tools.
- The focus on agent based workflows like Trimble Assist and Agent Studio, plus AI driven scheduling and procurement tools, points to Trimble leaning harder into recurring, workflow embedded software rather than one off hardware sales.
- This article will examine how Trimble's AI infused Trimble Connect platform may influence its positioning around recurring, software driven workflows for investors.
Trimble Investment Narrative Recap
For Trimble, the big belief is that AI driven, connected construction workflows can offset pressure in weaker areas and turn today’s platform into a higher quality stream of subscription style cash flows. The analyst consensus Narrative on Simply Wall St leans heavily on recurring revenue and margin expansion. Recent Trimble Connect AI launches feed directly into that story, tying software, field devices and financial systems into one workflow.
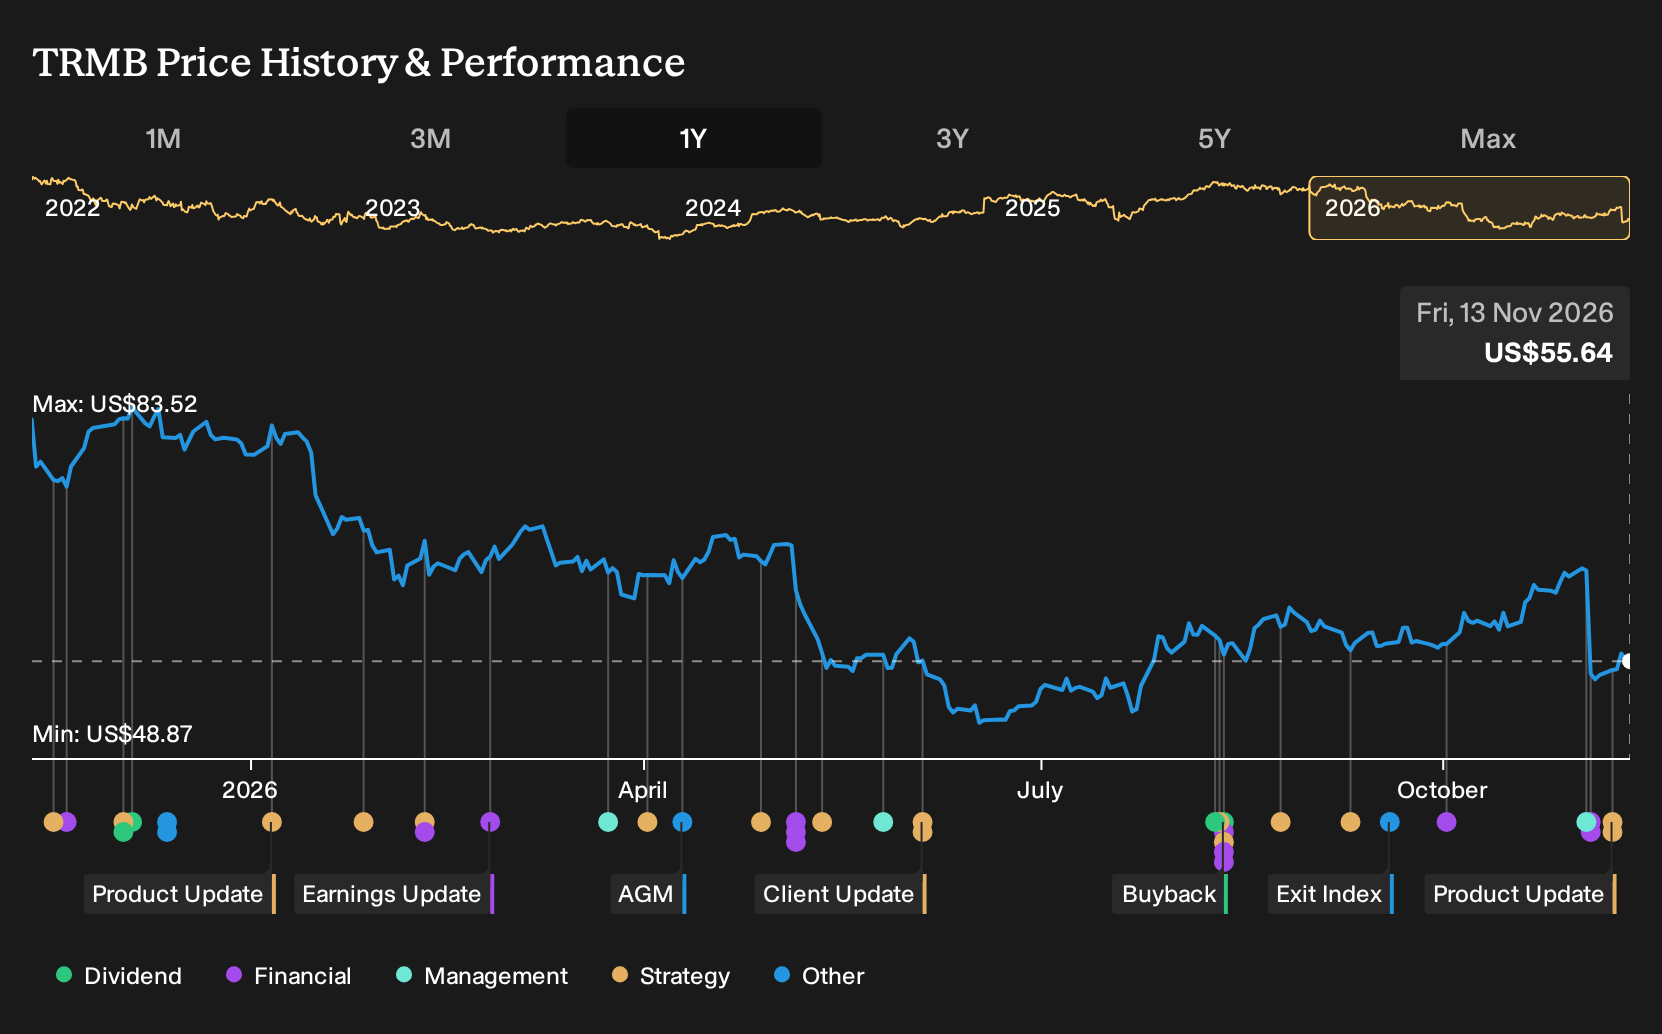
The near term swing factor is execution. Trimble is still working through a Field Systems product transition, acknowledged control weaknesses and a share price that has fallen roughly 29% year to date. The new AI capabilities do not change those issues overnight, but they do give management more levers inside construction to support adoption, stickier usage and, over time, reported profitability.
The Outbuild integration with Trimble ProjectSight is the clearest operational proof point around the current AI and workflow push. It pulls submittals, RFIs and drawings directly into Outbuild’s scheduling tools so schedule, risk and documentation move together instead of being reconciled in spreadsheets. For a shareholder, that matters because it links Trimble’s project data more tightly to how contractors actually plan work.
This connection also lines up with the catalysts in the analyst consensus Narrative on Simply Wall St around connected workflows and ARR quality. By making procurement and design issues appear instantly as schedule risk inside Outbuild, Trimble increases the practical value of its software to general contractors. That can support usage depth across AECO clients, while still leaving the familiar risks around governance fixes and Field Systems transition timing squarely on the table.
Trimble's narrative projects revenues of US$4.9b and earnings of US$1.6b by 2029, which reflects analysts assuming revenue expands at 8.2% a year and earnings rise by roughly US$1.76b from a loss of US$157.1m today.
Uncover how Trimble's fair value indicates a 33% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic Trimble analysts frame the real catalyst as faster subscription conversion rather than just AI tools. Before this news, the bullish cohort was already assuming revenue growth of about 9% a year and earnings of roughly US$1.6b by 2029. You can read this AI launch as a fresh reason to compare those upbeat expectations with more cautious views.
Explore 2 other Trimble fair value estimates, including one that suggests as much as 86% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Trimble research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Trimble. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Trimble's overall financial health at a glance.
Looking for more Trimble style investment ideas?
If Trimble's push into AI guided, recurring software workflows has your attention, it can be useful to compare it with other companies that combine resilient balance sheets, income potential and mispriced quality. The Simply Wall St Screener offers several starting points that you can tailor to your own risk tolerance and time horizon.
- If capital preservation sits high on your list, start with a curated set of companies that aim for stability and low downside risk through the 31 resilient stocks with low risk scores.
- For investors hunting for mispriced quality, a targeted collection of stocks trading below internal estimates of value can be a useful hunting ground through the 32 high quality undervalued stocks.
- If you want income plus fundamentals rather than yield at any price, focus on businesses screened for higher dividend payouts and financial strength by using the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com