


EN
Half Year Earnings Could Be A Key Test For TBS HoldingsInc Stock (TSE:9401)
- TBS Holdings, Inc. reported half year results for the period ended September 30, 2026, with sales of ¥215,073 million, net income of ¥17,666 million, and basic earnings per share from continuing operations of ¥114.18.
- The fresh half year figures show how TBS Holdings, Inc. is converting its broadcast and content operations into earnings per share, while operating with lower profit margins than in the previous year.
- We will now look at how TBS Holdings, Inc.'s half year earnings per share performance could influence the broader investment narrative for the group.
What Is TBS HoldingsInc's Investment Narrative?
The big picture for owning TBS HoldingsInc is simple. You need to believe the group can keep turning its mix of media, lifestyle and real estate activities into reliable cash generation while tightening profitability. The latest half year print, with ¥215,073 million in sales and ¥114.18 in basic EPS, reinforces that the core broadcast and content engine is still producing earnings, even as margins sit below last year. For the near term, the key swing factors stay operational, such as content monetisation, advertising demand and cost control rather than any single quarter.
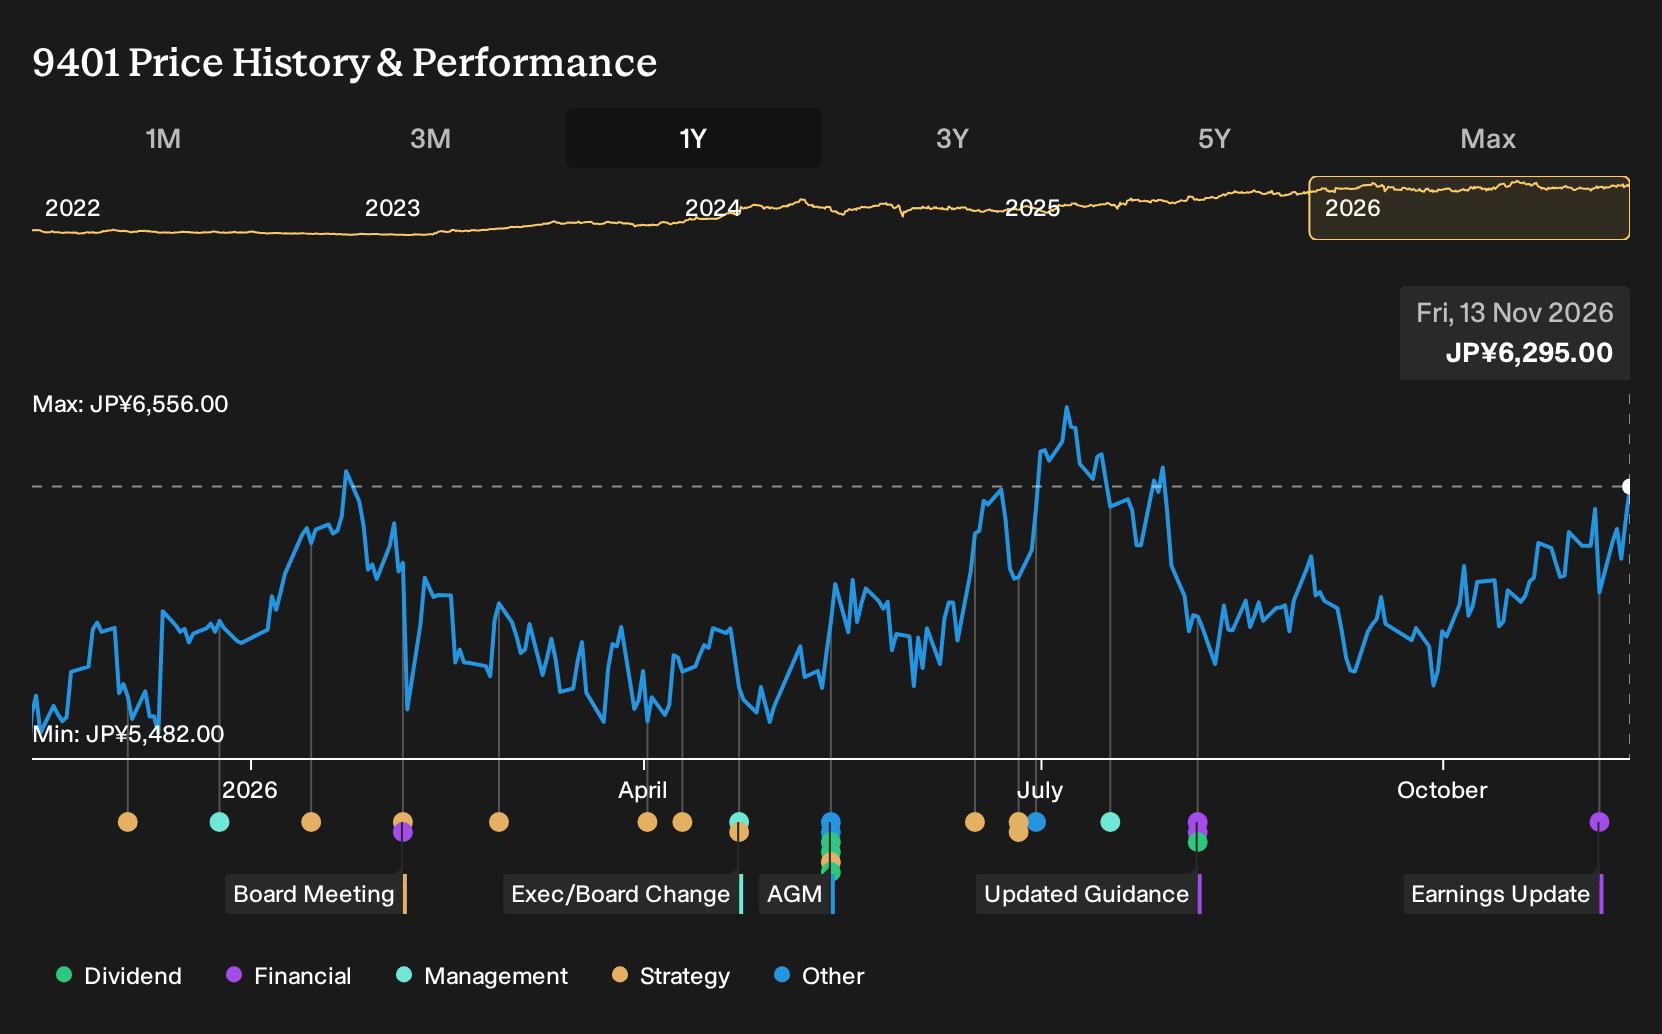
In the short term, the step down in net profit margin to 5.7% from 13.3% keeps execution risk front and center. TBS HoldingsInc is being priced on a rich 39.1x P/E, above both its own fair P/E estimate of 25.7x and the JP Media industry average of 13.8x, so the bar on delivery remains high. Forecast earnings growth of 15.8% a year and a share price that sits below one estimate of future cash flow value help the longer term story, but they do not change the basic near term task, which is rebuilding profitability from this latest base.
That said, there is a single operational pressure point in this set of numbers that could unsettle that investment case if ...
There's only one way to know the right time to buy, sell or hold TBS HoldingsInc. Head to Simply Wall St's company report for the latest analysis of TBS HoldingsInc's Fair Value.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so trust your own judgment and analysis.
- A great starting point for your TBS HoldingsInc research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for TBS HoldingsInc. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TBS HoldingsInc's overall financial health at a glance.
Looking For More Ideas Beyond TBS HoldingsInc?
If TBS HoldingsInc has put the media sector on your radar, it can help to line it up against other potential opportunities that match your risk profile and income needs. The Simply Wall St Screener lets you filter for very specific traits so you can build a watchlist that actually fits how you invest.
- If you want potential growth with tighter downside checks, start with a group of companies that score well on resilience and financial risk using the 19 resilient stocks with low risk scores.
- If income is a priority and you care about consistency, focus on businesses with stronger yield profiles and payout histories through the 29 dividend fortresses.
- If you are hunting for quality that the crowd may have overlooked, aim for fundamentally solid stocks with less attention on them via the 73 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com