


EN
Supplier Emissions Push Might Change The Case For Investing In Tesco (LSE:TSCO)
- Tesco has asked around 400 suppliers across the UK and Ireland to report emissions through the OpenClimat platform, aiming to standardise carbon data and support its 2050 net zero goal across the full value chain.
- The move shifts more of Tesco's decarbonisation effort into the supply chain, where improved emissions data can influence sourcing decisions, supplier relationships and long term cost management.
- The next area of focus is how Tesco's supplier emissions data initiative might shape the investment narrative built around efficiency, cash generation and growth.
Scan other retailers that could benefit from tighter supply chain emissions reporting by reviewing our curated list of list of solid balance sheet and fundamentals (9 results) in addition to Tesco's latest move.
Tesco Investment Narrative Recap
To own Tesco, you need to believe the core food and online grocery engine can keep doing the heavy lifting while cost control absorbs pressure in weaker areas like clothing and UK convenience. The analyst consensus narrative on Simply Wall St focuses on steady revenue, modest earnings growth and continued free cash flow generation rather than a dramatic acceleration story.
The current emissions data push fits that steady thesis more than it reshapes it. The more immediate swing factor still appears to be UK food volumes and the balance between price investment and margins. The key operational risk remains intense competition that could force deeper promotions and dilute profitability.
The OpenClimat rollout matters most where it touches Tesco’s Save to Invest program and long term cost base. Cleaner supplier emissions data can make it easier to link sourcing choices with energy, transport and packaging costs over time, which aligns with the goal of offsetting operating cost inflation through efficiencies.
No fresh trading update is tied to this move, so the near term catalysts cited in existing commentary remain unchanged. Investors are still watching for further delivery on the £500m of targeted savings in 2026/27, progress in online grocery and Whoosh, and how UK convenience trends evolve, with the emissions initiative sitting in the background as an enabler rather than a primary driver.
Tesco's current analyst narrative points to forecast revenues of £79.7b and expected earnings of £2.4b by 2029, based on an assumed 2.0% yearly revenue growth rate and an earnings increase of £0.5b from earnings today of £1.9b.
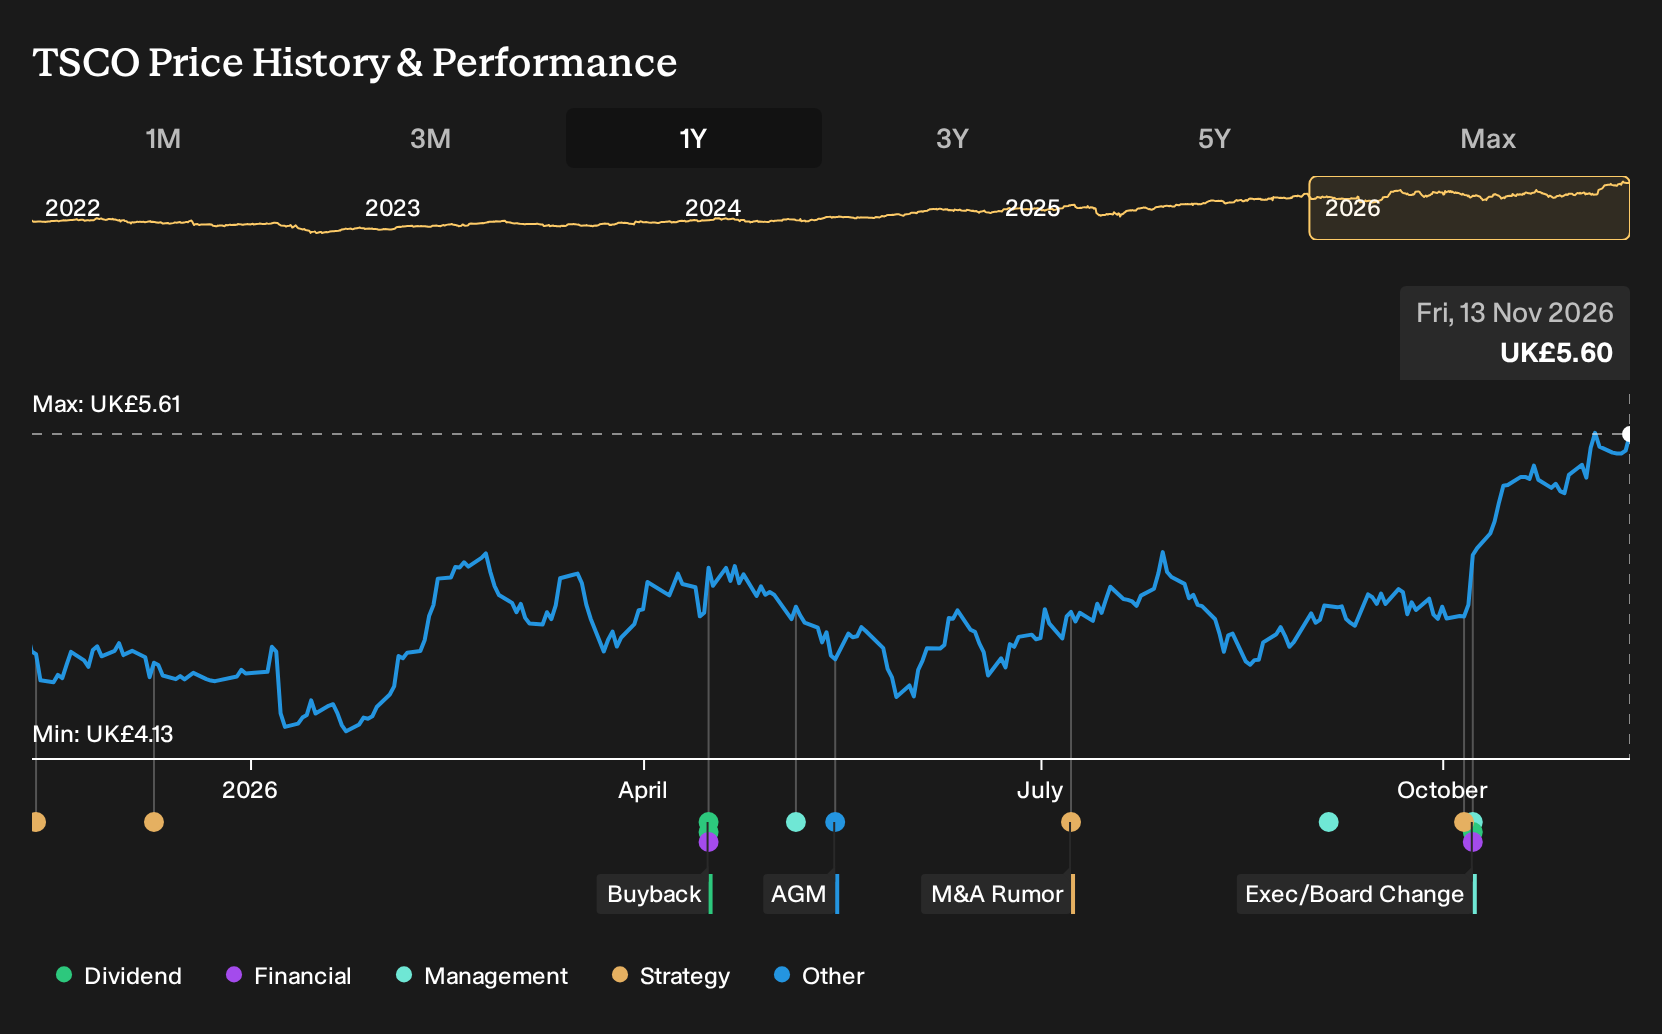
Uncover why Tesco's fair value indicates a 5% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between £5.35 and £7.59, so retail opinions on Tesco’s worth already show a wide span. When these views are set against risks around intense UK grocery competition and weak industry volumes, it becomes clear why exploring several alternative viewpoints matters.
Explore 2 other Tesco fair value estimates, including one that suggests as much as 35% potential upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Tesco research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Tesco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tesco's overall financial health at a glance.
Looking For More Investment Ideas Beyond Tesco?
If Tesco is on your radar, it can help to set it alongside other potential opportunities that share similar financial traits. The Simply Wall St Screener lets you scan the market quickly, then focus your time on a shortlist that actually matches your risk tolerance and return goals.
- If you want resilient balance sheets that can absorb shocks, start with our curated 5 resilient stocks with low risk scores list that already clear a tough risk filter.
- For investors hunting value with quality in mind, review a targeted set of 15 high quality undervalued stocks options that pair solid fundamentals with more modest pricing.
- Income focused readers who care about reliability can check out a focused group of 4 dividend fortresses ideas that combine higher yields with an emphasis on stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com