


EN
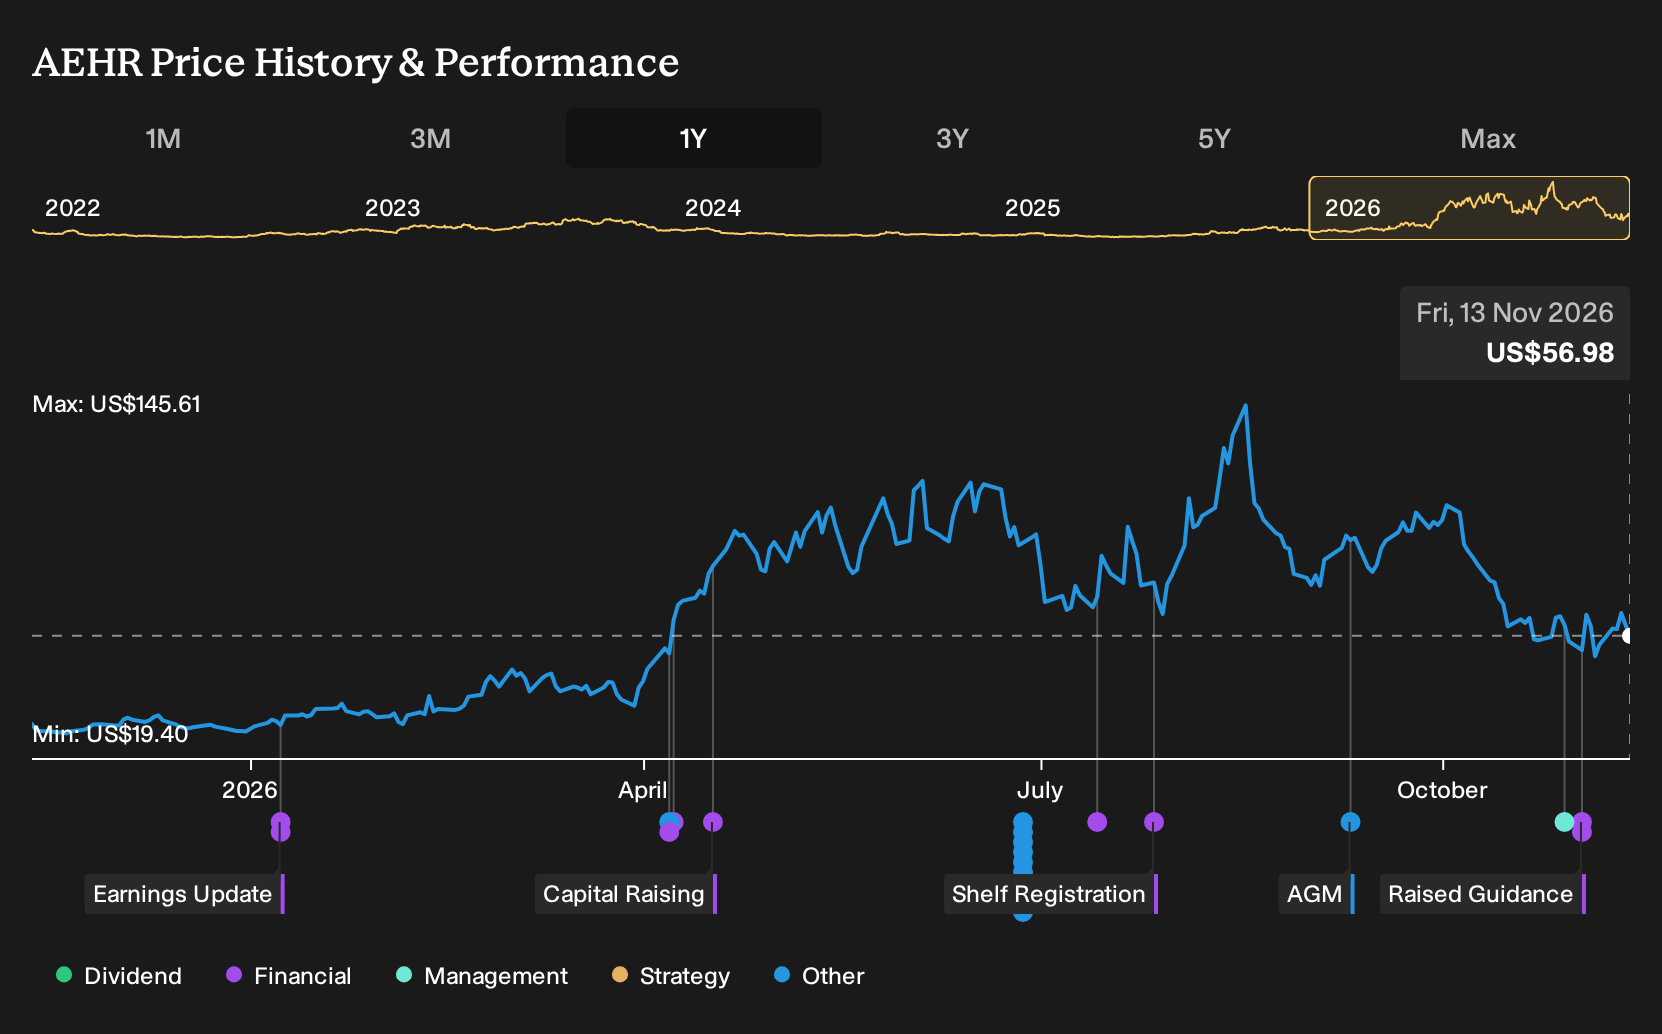
Aehr Test Systems Stock In Focus After Raised Revenue Outlook
- Aehr Test Systems reported first quarter fiscal 2027 sales of US$33.01 million and net income of US$7.18 million, and management raised full year revenue guidance to US$150 million from a prior range of US$130 million to US$150 million.
- The swing from a prior quarterly loss to earnings per share of US$0.22 basic and US$0.21 diluted highlights how Aehr Test Systems is converting demand for its semiconductor test platforms into profitability at the start of the fiscal year.
- We will now see how Aehr Test Systems' raised full year revenue outlook could reshape the existing investment narrative around demand durability.
Scan beyond Aehr Test Systems by reviewing a curated group of fast moving semiconductor and AI infrastructure players in the 53 AI infrastructure stocks that could be reacting to similar guidance shifts.
Aehr Test Systems Investment Narrative Recap
An investor in Aehr Test Systems needs to believe that wafer level burn in stays integral to AI processors, silicon photonics and power devices, and that customers keep qualifying on FOX and Sonoma platforms instead of shifting to alternatives. The raised US$150 million revenue outlook points to management confidence in demand conversion, which supports this thesis but does not remove execution risk.
The near term catalyst is management showing that the existing backlog and capacity investments in Fremont, Southeast Asia and Taiwan translate into consistent quarterly system and consumable shipments. The biggest current risk remains customer concentration and potential pauses in AI and data center capex that could leave that extra capacity underutilized.
The analyst consensus Narrative on Simply Wall St already framed a fiscal 2027 revenue outlook of US$130 million to US$150 million as a key driver for higher revenue and operating income. The move to a single US$150 million target now lines up with the top of that range, so attention shifts to how quickly Aehr Test Systems converts its roughly US$100.6 million backlog into recognized sales.
First quarter fiscal 2027 results bring that question into sharper focus. Sales of US$33.01 million and net income of US$7.18 million show what the model can look like when AI processors, silicon photonics and new GaN or silicon carbide uses are all feeding the installed base. The operational test from here is whether those levels can be supported as customers adjust ordering patterns and as memory or GaN contributions develop from a low starting point.
Aehr Test Systems' current narrative points to forecast revenues of US$242.3 million and earnings of US$97.8 million by 2029, built on analysts assuming about 69.2% yearly revenue growth and an earnings shift of roughly US$104.9 million from today’s earnings loss of US$7.1 million.
Uncover why Aehr Test Systems' fair value indicates a 112% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One optimistic twist in the alternate Aehr Test Systems story is how bullish analysts treated share concentration as a strength rather than a vulnerability. Before this guidance raise, they were already modeling about US$265.0 million of revenue and US$124.8 million of earnings by 2029. That is a far more upbeat script. Use it as a prompt to compare several viewpoints and decide which assumptions feel realistic to you, especially now that fresh numbers are on the table and those older forecasts may evolve.
Explore 4 other Aehr Test Systems fair value estimates, including one that suggests as much as 112% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Aehr Test Systems research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Aehr Test Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aehr Test Systems' overall financial health at a glance.
Looking for more investment ideas beyond Aehr Test Systems?
If the Aehr Test Systems story has sharpened your thinking, use that momentum to scan a wider field of opportunities where the numbers and business quality line up with your own risk profile.
- For readers who care most about financial resilience and clean balance sheets, start with a list of solid balance sheet and fundamentals (24 results) that prioritizes strength over hype.
- If you are hunting for misunderstood quality where price and fundamentals seem misaligned, filter the market using a 32 high quality undervalued stocks that may surface stocks worth a closer look.
- Those who prefer to keep risk in check while still staying invested can focus on stability first by working through a 31 resilient stocks with low risk scores tailored to steadier profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com