


EN
Paradox Interactive (OM:PDX) Has Fresh News, But What Is Drawing Attention Now?
Paradox Interactive (OM:PDX) just launched The Silver Seas expansion for Age of Wonders 4, tying fresh paid content, a broader expansion pass, and a free weekend on Steam and Xbox into one push.
Recent trading has picked up, with a 12.20% 30 day share price return and a 10.06% 90 day share price return taking Paradox Interactive to SEK149.9. However, the year to date share price return is still down 4.58% and the 3 year total shareholder return has fallen 28.01%.
Scan other gaming and media stocks that show similar momentum and content-driven catalysts by checking the hand picked 566 high quality undiscovered gems alongside Paradox Interactive.
Paradox Interactive has caught a bid on fresh content and a free weekend, yet a 3 year return that fell 28.01% still hangs over the chart. Does that recent pop leave enough upside in the valuation?
Most Popular Narrative: 4.8% Undervalued
Paradox Interactive last closed at SEK149.9, which sits modestly below the analyst consensus Narrative fair value of SEK157.4 that uses a 7.2% discount rate and links that gap to long lived franchises and capital returns in the analyst consensus Narrative on Simply Wall St.
Paradox Interactive is allocating over SEK 700m to dividends and share buybacks in 2026 while still holding around SEK 1b of cash. The company has also secured a board mandate for continued repurchases, which can lift earnings per share even if operating profit is stable.
See why 24 investors see Paradox Interactive as 5% undervalued.
The company level data lines up with that viewpoint. Paradox Interactive is valued by the SWS DCF model at SEK151.89 per share, which is only 1.3% above the current SEK149.9 price and close to the SEK157.4 analyst fair value, suggesting limited room for error around those cash flow assumptions.
Analysts in that Narrative are tying the investment case to earnings growth, with forecast annual profit expansion of 40.41% and expected revenue growth of 7.4% per year from a base of SEK2,285.918m of sales and SEK160.456m of net income. That helps explain why the stock carries a high current P/E of 97.5x and a value score of 1 even while the DCF view points to only a small discount.
For context, the Storyteller behind this Narrative also flags that analysts expect Paradox Interactive to reach a future P/E of 18.1x on 2029 earnings, compared to the current European Entertainment industry P/E of 19.5x. The discount rate of 7.2% is used consistently across those projections when translating future earnings and cash flows back into today’s fair value range.
Result: Fair Value of SEK157.4 (UNDERVALUED)
Still, that bullish Paradox Interactive story depends on DLC spending from 6 million monthly players holding up, and on avoiding further Europa Universalis 5 style execution missteps.
Find out about the key risks to this Paradox Interactive narrative.
Another View: Paradox Interactive Through The P/E Lens
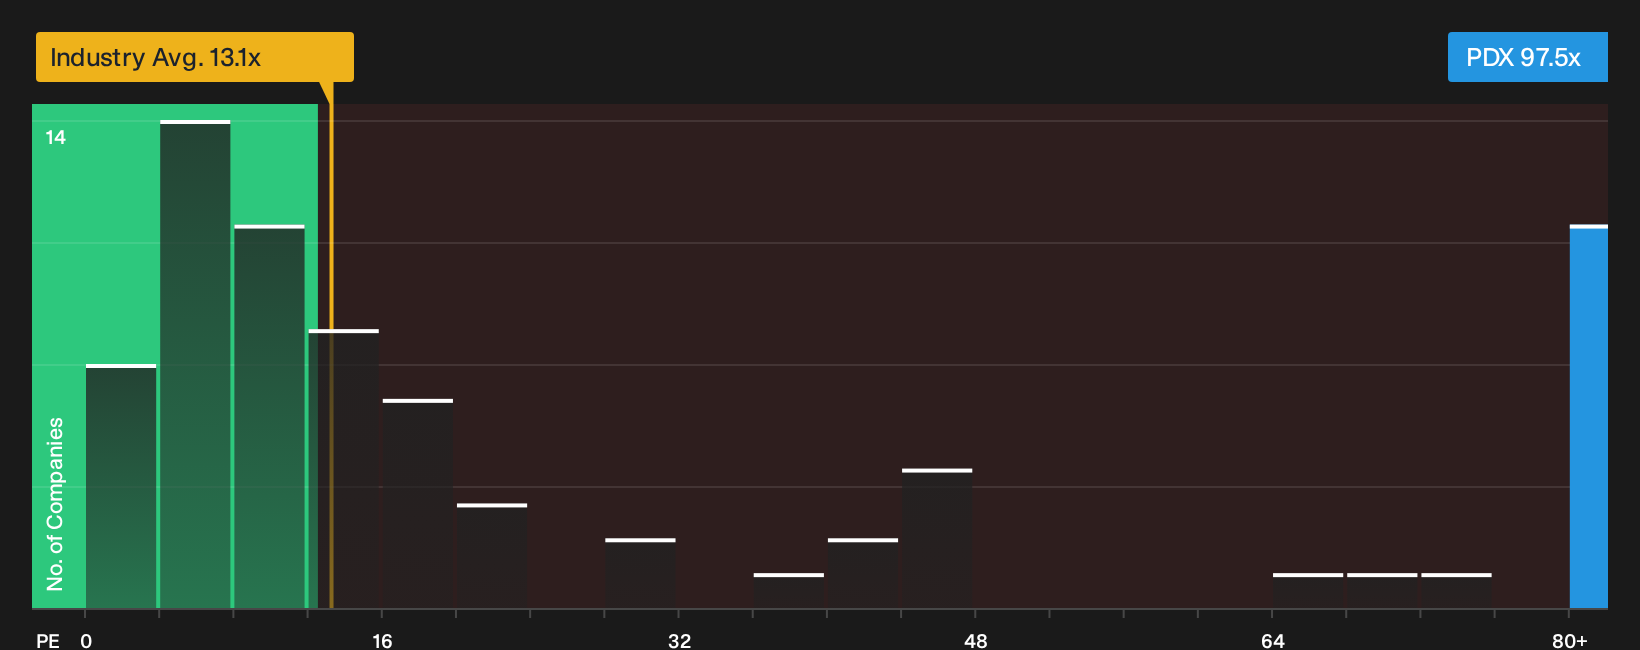
Paradox Interactive looks quite different when you swap the SWS DCF model for a simple earnings multiple. The stock trades on a P/E of 97.5x, which is far above the European Entertainment average of 13.3x and also above its own fair ratio of 42.8x. That gap points to meaningful valuation risk if sentiment cools, even with upbeat earnings forecasts on the table.
Our DCF based view leans on detailed cash flow assumptions. In contrast, the P/E snapshot highlights how much optimism is already embedded in today’s SEK149.9 price. For a fuller picture of how those approaches compare, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Paradox Interactive is mixed, with momentum on one side and past drawdowns on the other. Act quickly and test the data yourself, then weigh up the 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Paradox Interactive?
If you like how Paradox Interactive mixes content catalysts with hard numbers, you should scan other opportunities that line up with your own risk and income preferences.
- Target resilient balance sheets and steady fundamentals by running the list of solid balance sheet and fundamentals (200 results) before capital flows into the next big theme without you.
- Hunt for mispriced quality by scanning the 199 high quality undervalued stocks so potential bargains do not move without landing on your radar first.
- Prioritise stability and staying power by reviewing the 211 resilient stocks with low risk scores while prices still reflect today's risk assessments rather than tomorrow's surprises.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com