


EN
Drilling Contract Win At SLB (SLB) Has Changed Its Investment Story
- Vår Energi has awarded SLB the role of main integrated drilling services supplier for two harsh environment rigs on the Norwegian Continental Shelf, under a four year contract with four optional one year extensions that could run through 2034.
- The deal deepens SLB’s role in Vår Energi’s offshore operations by linking integrated drilling with existing digital planning and subsea production work under the OneSubsea partnership.
- We will look at how SLB’s investment narrative around higher margin integrated and digital services aligns with this long term Vår Energi award.
Scan other contractors riding similar offshore momentum by checking the hand picked 44 power grid technology and infrastructure stocks, which could sit alongside SLB in an energy infrastructure watchlist.
SLB Investment Narrative Recap
To own SLB, you need to be comfortable with a business that leans on long cycle oil and gas work while trying to grow higher margin digital and data center operations. The analyst consensus Narrative on Simply Wall St leans on earnings that are forecast to grow 16.41% per year and improving margins, which still depends heavily on smooth project execution.
The fresh Vår Energi win supports the idea that large integrated contracts remain available, although it does not change the biggest near term swing factors. Key catalysts still sit in data center solutions, ChampionX and Kelvion integration, while major risks include weaker global upstream spending and any prolonged revenue drag from the Middle East.
The Aker BP Lyra award for subsea production systems and umbilicals fits directly beside the Vår Energi contract. Together they underline that SLB keeps winning work tied to standardized subsea kit and integrated delivery, which matters for the narrative that more activity shifts toward production systems and recurring service style work.
For catalysts, Lyra reinforces how subsea projects can feed into SLB’s Production Systems division, where EBITDA margins were above 20% according to the analyst consensus Narrative on Simply Wall St. Execution missteps or delays on contracts like Lyra would be a practical risk for that margin story, while consistent delivery would support the push toward steadier, OPEX linked revenue streams.
SLB's narrative projects US$43.0b revenue and US$5.5b earnings by 2029. This aligns with analyst expectations of 5.7% yearly revenue growth and an earnings increase of about US$2.4b from current earnings of US$3.1b.
Uncover how SLB's fair value indicates a 21% potential upside to its current price before that discount closes.
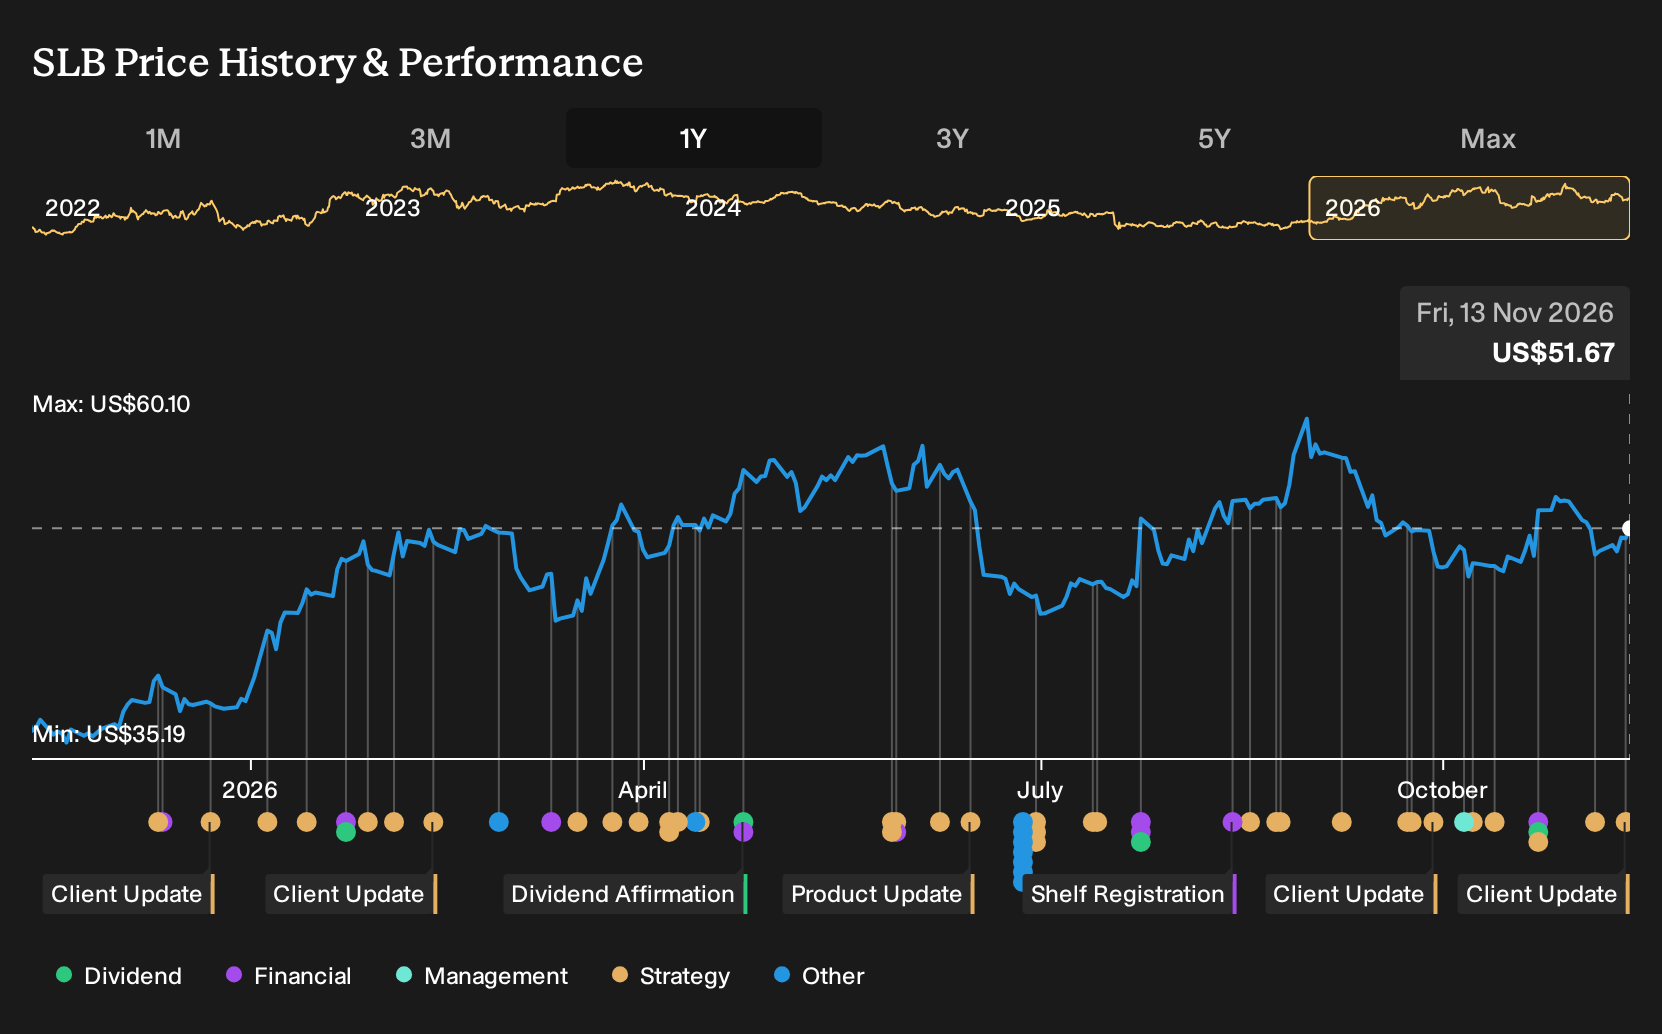
Exploring Other Perspectives
One bullish twist on SLB focuses on offshore awards like this Vår Energi deal as the real earnings swing factor, rather than data center growth. The most optimistic analysts were already sketching out about US$51.2b of revenue and US$7.3b of earnings by 2029. You can treat this contract as a fresh test of that more aggressive storyline and explore how expectations might shift from here.
Explore 5 other SLB fair value estimates, including one that suggests as much as 65% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your SLB research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for SLB. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SLB's overall financial health at a glance.
Looking for more SLB style investment ideas?
If the SLB story has sharpened your thinking, use that momentum to widen your watchlist with a few focused stock shortlists built in the Simply Wall St Screener. Each one targets a different angle so you can match ideas to your own risk, income, or quality preferences.
- For investors who want potential growth at a lower share price, scan the 13 elite penny stocks with strong financials and see which smaller companies still show solid financial traits.
- If the priority is quality at a sensible entry point, work through the 32 high quality undervalued stocks and compare those candidates with the kind of profile you see in SLB.
- When capital preservation and balance sheet strength come first, focus on the list of solid balance sheet and fundamentals (24 results) and build a shortlist of sturdier businesses to research next.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com