


EN
Is Global Retirement Launch Altering The Investment Case For Marsh McLennan (MRSH)?
- Marsh & McLennan Companies introduced Marsh BrightPath, a globally coordinated defined contribution retirement solution spanning six markets and US$116b in assets under management, giving multinational employers a single framework that still adapts to local regulation and workforce needs.
- The consolidation of US$116b of retirement assets into Marsh BrightPath concentrates fee based activity around the Marsh & McLennan Companies platform, which could reshape how the firm aligns its advisory, governance and digital tools across pensions, wealth and broader consulting mandates.
- We will now explore how the Marsh BrightPath defined contribution platform from Marsh & McLennan Companies might influence the broader investment narrative for the business.
Scan how Marsh & McLennan Companies reshapes retirement and risk, then compare it with other complex-finance plays using the hand picked 20 high quality undiscovered gems.
Marsh & McLennan Companies Investment Narrative Recap
To own Marsh & McLennan Companies, you need to believe the firm can keep turning complex risk and retirement needs into growing fee income while holding margins together as pricing pressure and legal costs bite. The analyst consensus Narrative on Simply Wall St leans on expectations for earnings growth near 10.8% a year and efficiency gains from AI and process reengineering.
The near-term swing factor still sits in execution on cost programs like Thrive and on stabilising reinsurance broking after recent revenue pressure. The biggest risk remains softer pricing in property and reinsurance, which could combine with high debt and litigation costs to squeeze net income if productivity gains disappoint.
Among the recent developments, Marsh BrightPath looks most relevant for you as a shareholder to track. It pools US$116b of defined contribution assets across six markets into a coordinated setup, which ties directly into Mercer’s wealth ambitions and the push toward higher fee-based and retirement-related revenues.
Execution here links tightly to the catalysts analysts are watching. If Marsh & McLennan Companies can integrate BrightPath with its AI tools, governance services and AWS-backed efficiency work, the retirement platform could support the broader margin story. Weak uptake or operational missteps would instead add complexity without easing the existing pricing and legal headwinds.
Marsh & McLennan Companies' narrative projects US$31.5b revenue and US$5.4b earnings by 2029. This assumes 4.1% yearly revenue growth and an earnings increase of about US$1.4b from US$4.0b today.
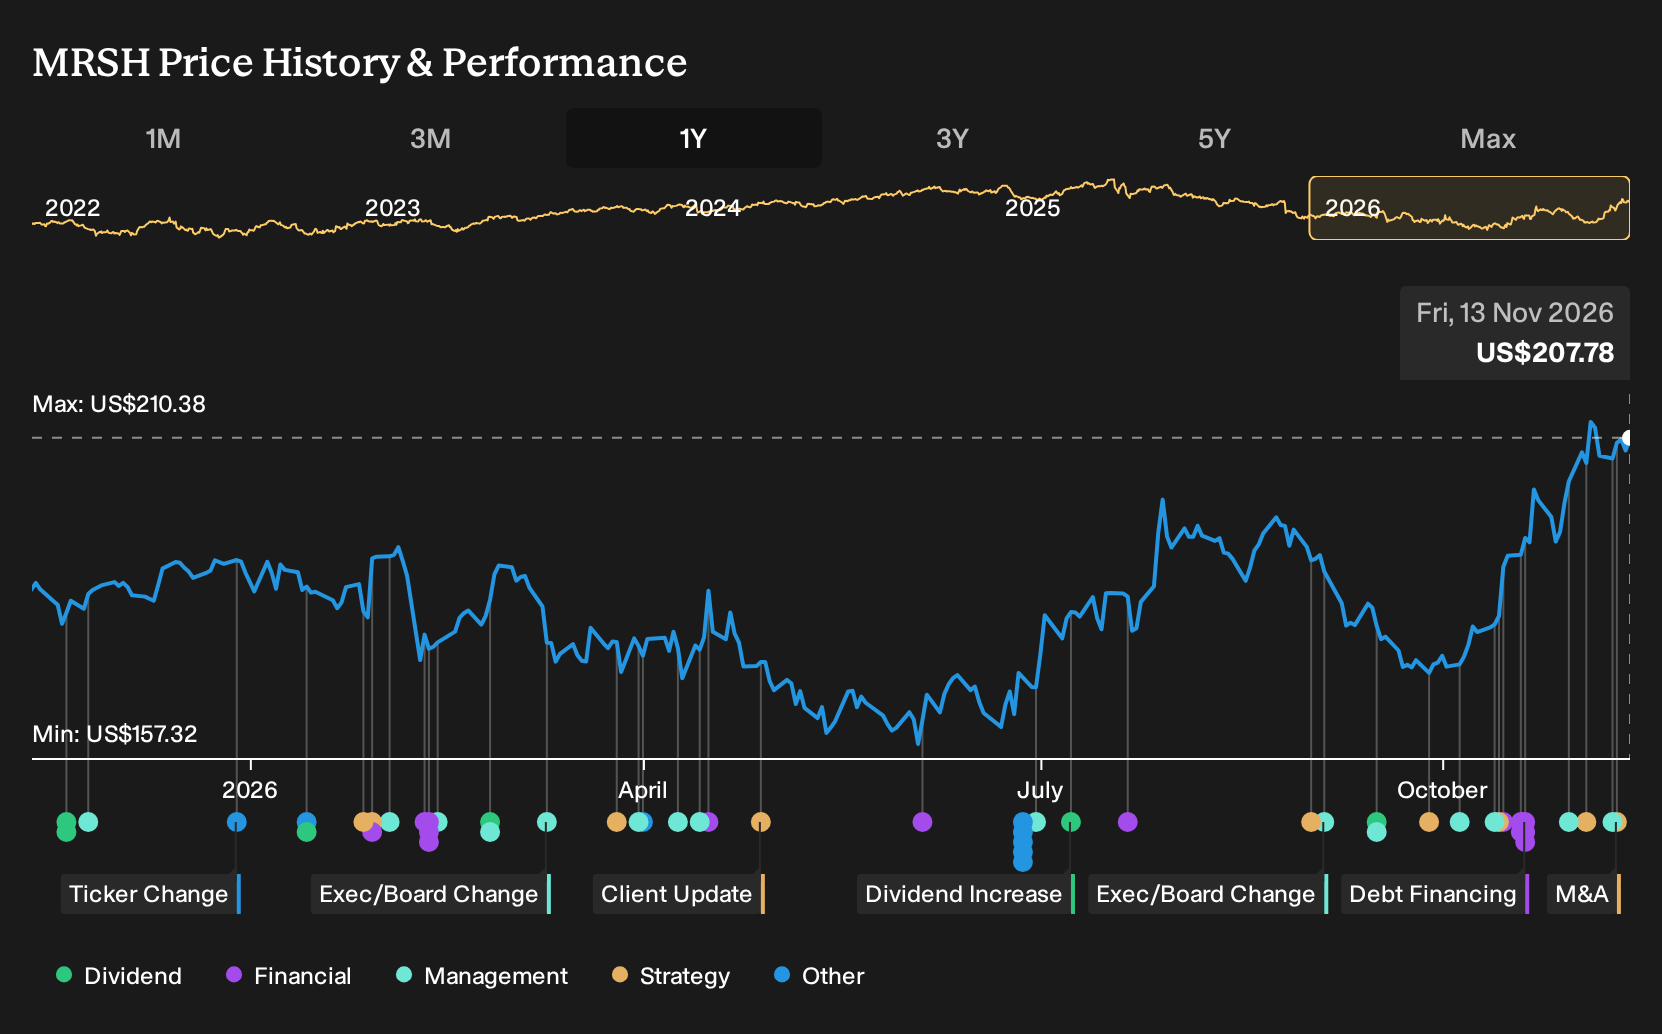
Uncover why Marsh & McLennan Companies' fair value is essentially in line with its current price.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly US$203 to US$289 per share, showing how far opinions on Marsh & McLennan Companies can spread. These views predate Marsh BrightPath and the incoming Marine leadership changes, so you may want to weigh them against pricing pressure, litigation risk, and the AI plus cost efficiency programs now underway.
Explore 3 other Marsh & McLennan Companies fair value estimates, including one that suggests potential upside of up to 39% from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Marsh & McLennan Companies research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Marsh & McLennan Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Marsh & McLennan Companies' overall financial health at a glance.
Looking for more investment ideas beyond Marsh & McLennan Companies?
Once you have a view on Marsh & McLennan Companies, it can help to line that thesis up against a few very different types of opportunities using the Simply Wall St Screener.
- If you want potential value combined with quality fundamentals, scan the 32 high quality undervalued stocks to see which businesses meet both tests.
- For steadier profiles that may suit a more cautious approach, check out the 31 resilient stocks with low risk scores and focus on companies with lower risk scores.
- If balance sheet strength is a priority, use the list of solid balance sheet and fundamentals (24 results) to filter for stocks with robust finances and underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com