


EN
Earnings Beat Could Be A Big Moment For Royal Gold Stock (RGLD)
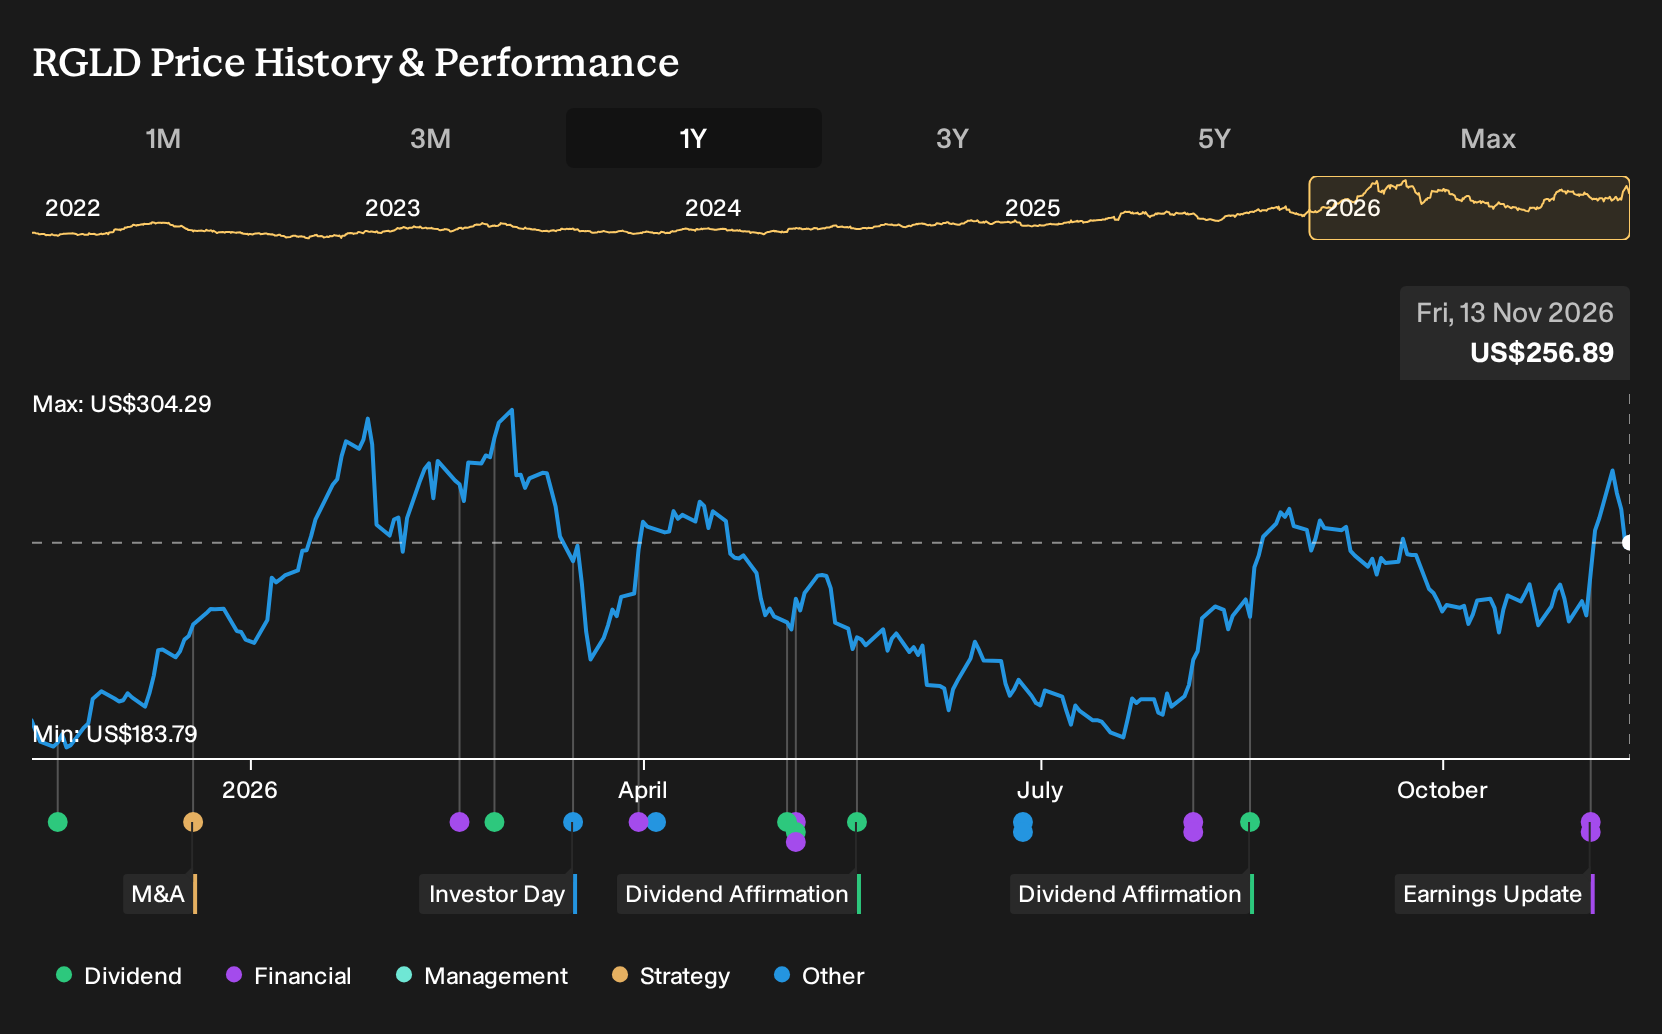
- Royal Gold reported third quarter 2026 sales of US$461.27 million and net income of US$227.42 million, with basic and diluted earnings per share from continuing operations of US$2.68, alongside nine month sales of US$1.3742 billion and net income of US$744.94 million.
- The unchanged full year volume guidance for gold, silver and copper, together with much higher reported sales and earnings, indicates that pricing and mix effects are playing a key role in Royal Gold’s recent performance.
- This raises the question of how Royal Gold’s investment narrative is influenced by this sharp jump in quarterly earnings and profit.
Scan beyond Royal Gold and line up other precious metals producers showing strong reported earnings momentum with the curated 33 elite gold producer stocks in one place.
Royal Gold Investment Narrative Recap
To be comfortable owning Royal Gold, you need to believe in its royalty and streaming model continuing to convert a long life portfolio and option rich project pipeline into steady metal volumes with high margins. The analyst consensus narrative on Simply Wall St focuses on execution on that pipeline and disciplined capital allocation. The latest earnings jump shows that pricing and mix can move reported profit quickly, but the unchanged volume outlook means the core thesis around asset life and diversification is intact.
The most immediate catalyst is whether management can keep translating this stronger pricing mix and broad asset base into consistent earnings without further estimate cuts after earlier forecast reductions. The near term risk remains a return to earnings misses versus expectations and any renewed downgrade cycle, especially with Royal Gold trading on a relatively full P/E multiple compared with peers and the wider US metals and mining industry.
The key announcement tied to this story is the third quarter and nine month 2026 result, where Royal Gold reported US$461.27 million of quarterly sales and US$227.42 million of net income, and US$1.3742 billion of revenue with US$744.94 million of profit for the nine month period. Volume guidance for gold, silver and copper is unchanged, so the headline acceleration in earnings mainly reflects realised prices and portfolio mix rather than a reset in production expectations.
That matters for catalysts. If volumes stay broadly in line with guidance, investor attention is likely to stay on how quickly the development pipeline converts into new streams and how resilient margins remain if metal prices move around. The earlier pattern of estimate cuts and insider selling sits in the background as a risk that confidence could soften again if future quarters do not resemble this strong pricing led print.
Royal Gold Forecasts and What Needs To Happen
Royal Gold's narrative projects US$2.1b revenue and US$1.2b earnings by 2029. This is based on analysts using an 11.8% yearly revenue growth rate and expecting an earnings increase of about US$462m from current earnings of US$738.0m to the US$1.2b consensus level in 2029.
Uncover how Royal Gold's fair value indicates a 21% potential upside to its current price before this discount closes.
Exploring Other Perspectives
Royal Gold’s latest earnings surprise lands against a much harsher alternate story. The lowest analysts were working off roughly US$2.2b of 2029 revenue and about US$1.3b of earnings, yet still saw limited upside because of DD&A pressure and deal risks. That gap in expectations shows how widely views can differ. Explore both narratives and decide which assumptions feel closer to your own.
Explore 4 other Royal Gold fair value estimates, including one that suggests it could be worth just $263.58.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Royal Gold research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Royal Gold. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Royal Gold's overall financial health at a glance.
Looking For More Ideas Beyond Royal Gold?
Once you have a handle on Royal Gold, it can help to widen the lens and compare it with other opportunities that match your risk appetite and income goals. The Simply Wall St Screener gives you a way to filter the market using fundamentals first so you are not just chasing headlines or short term moves.
- If you want growth potential at lower share prices, start by reviewing 13 elite penny stocks with strong financials that already show stronger financial traits than the typical microcap.
- For investors who care most about quality and price discipline, focus on our 32 high quality undervalued stocks that combine healthier balance sheets with stronger cash generation.
- If a smoother ride matters more to you than maximum upside, consider the 31 resilient stocks with low risk scores that screen for resilience using Simply Wall St's risk scoring framework.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com