


EN
Missed Out On Five Below's Run? Here's The Bet Holders Made
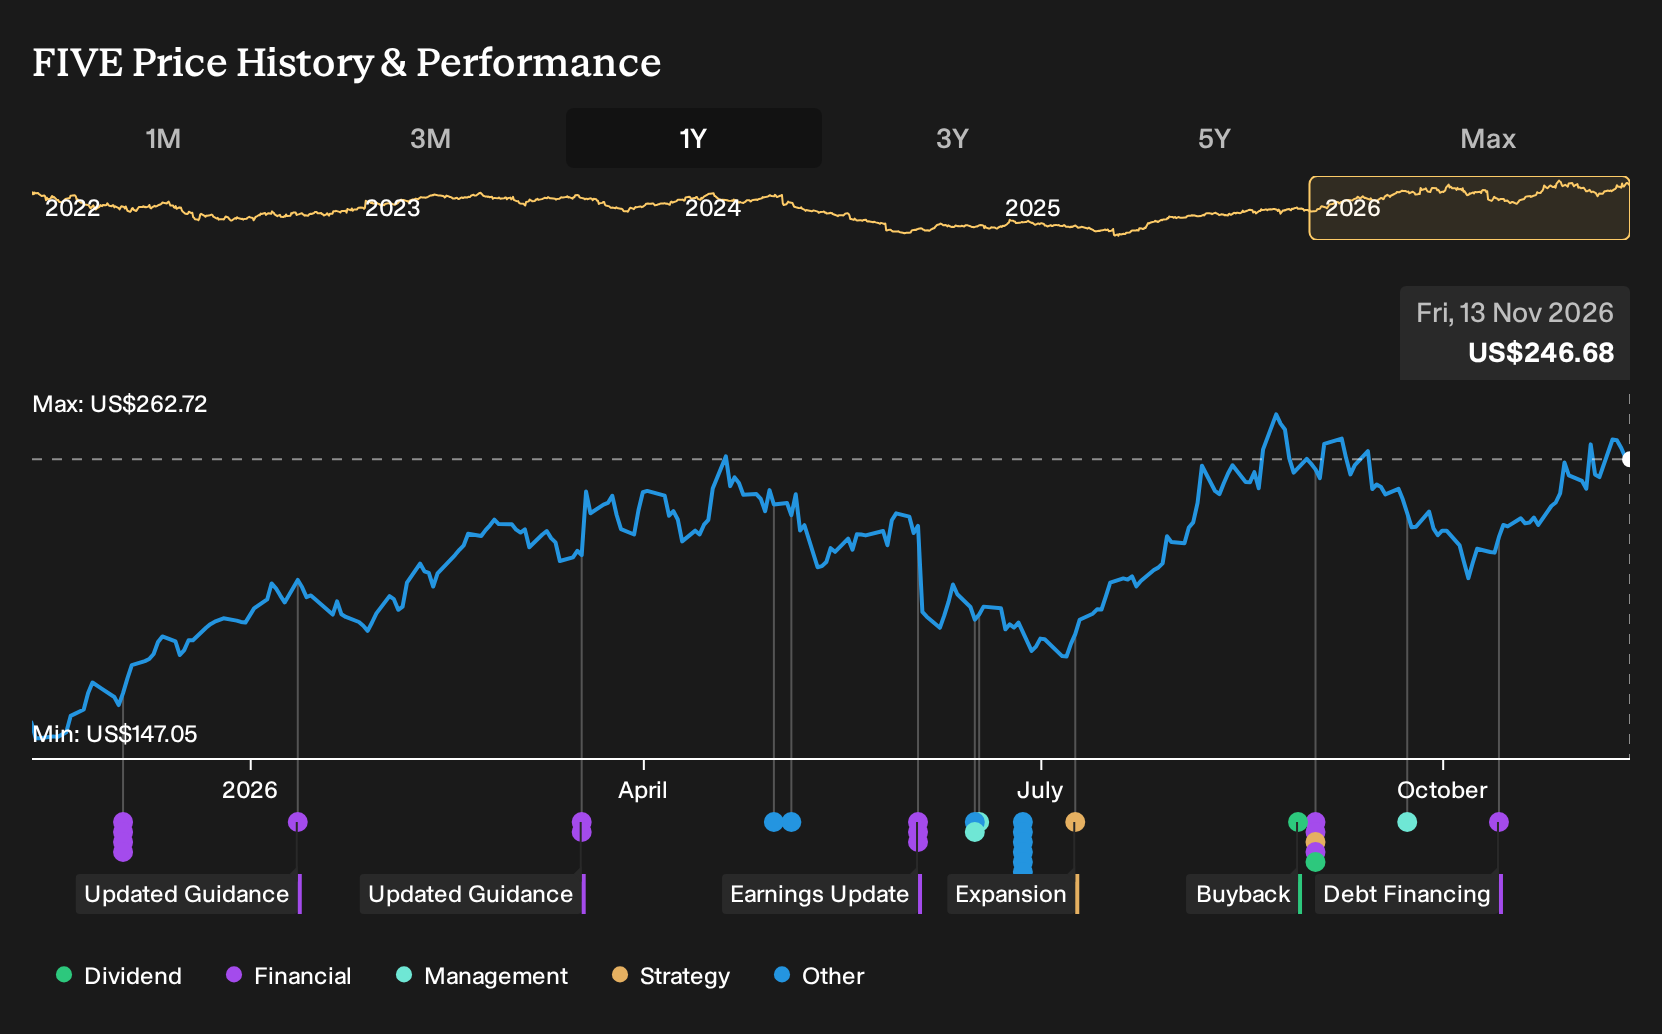
If you only skimmed the recent headlines about class actions, tariff disputes and questions over squishy toy demand, you might not expect the payoff that actually arrived. Investors who held Five Below over the past year are up 67.8%, including dividends. If you had been deciding on 13 November 2025 whether to buy into an aggressive store rollout with tariff and labor risks on the record, what did that early information really signal about today’s much stronger outcome?
The easy part of this move is behind Five Below. Zero in on 32 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Had To Choose Between On Five Below
The shares cost US$147 at the start of the period, and you had to decide which story about Five Below felt more realistic.
The bullish narrative saw a Fair Value of US$157, a rough guide to what the price could be if revenue grew 10.6% a year and margins settled near 6.2% on a future P/E of 31.6x.
The bearish view pointed to a Fair Value of US$90, with concern that heavy focus on physical stores and limited e-commerce kept margin pressure front and center.
What The Results Changed For The Five Below Debate
Five Below’s Q2 2027 report showed revenue of US$1.26b and net income of US$221.4m, with net margin moving from 4.2% in Q2 2026 to 17.6%. That improvement backed the bullish view that store expansion and simplification could support higher profitability, although ongoing class actions and tariff refund disputes kept some pressure on the cautious case. Overall, the evidence cut both ways.
The real hinge here was margin resilience. When you assess another retailer built on aggressive store growth, track whether net margin and absolute profit move in the same direction as new openings and guidance changes over several reports.
What Five Below’s Price Already Bakes In
Five Below now trades at US$247 after a 67.8% gain over the past year, so buyers today are paying well above where the bearish analyst Narrative on Simply Wall St places its Fair Value.
That Narrative focuses on legal, freight and compliance costs potentially capping how much store refreshes and higher price points can support earnings. Anyone paying today’s price is effectively assuming merchandising strength and traffic can keep offsetting those pressures, so how does that assumption stack up against the risks described in this Narrative?
"The main thing that has to go right is that Five Below keeps turning its customer focused merchandising, store experience refresh and higher price point assortment into healthy comparable sales and margin performance while absorbing ongoing cost and legal headwinds. The numbers imply that Five Below’s shares are pricing in a fairly valued outcome where double digit sales and earnings guidance, margin expansion targets and long term unit growth to more than 3,500 stores are largely reflected in today’s valuation."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Looking One Step Beyond Five Below
Five Below thrives on busy aisles, buzzing checkout lines and quick impulse buys.
It is easy to focus only on store traffic and basket size.
Step back and another shopper expectation appears alongside bargain bins and displays.
Customers also want fast delivery, broad selection and dependable digital experiences.
A larger retailer has invested heavily in logistics, data centers and seller tools, creating a commerce backbone that could rival the pull of any single chain.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 69% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com