


EN
Is Maplebear (CART) A Bargain As Its Provi Tie Up Reaches Restaurants Nationwide?
Maplebear (CART), better known as Instacart, is back on investor watch after a new tie up with Provi that plugs its grocery delivery network directly into bar and restaurant ordering systems nationwide.
Maplebear’s tie up with Provi lands at a time when momentum has been building, with a 30 day share price return of 19.17% and a year to date share price gain of 34.07%. The 1 year total shareholder return of 43.41% points to strong recent engagement from the market.
Scan other delivery and consumer platforms showing similar momentum with our curated list of 20 high quality undiscovered gems that have strong fundamentals but still fly under most investors’ radar.
After a near 20% move in 30 days and a share price of $58.87 sitting close to the average analyst target of $61.59, the bigger gap for Maplebear is to intrinsic value. The key question is which reference point matters most now.
Most Popular Narrative: 4% Undervalued
Maplebear’s analyst consensus Narrative on Simply Wall St assigns a fair value of $61.59, a touch above the last close at $58.87. This frames the new Provi deal against expectations for ads, enterprise software and AI tools to carry more of the load.
Deepening enterprise partnerships and omnichannel retailer integrations remain in focus, with Instacart’s technology now powering more than 380 grocery e commerce sites and Storefront Pro upgrades linked to over a 10 percentage point lift in online sales and over a 5 percentage point lift in 90 day new user retention, which can benefit transaction revenue and earnings quality.
See why 23 investors see Maplebear as 4% undervalued.
Result: Fair Value of $61.59 (UNDERVALUED)
Still, rising labor and compliance costs, especially around gig worker rules and recent regulatory settlements, could pressure the Maplebear margin story that underpins this valuation.
Find out about the key risks to this Maplebear narrative.
Another View: Maplebear On Traditional Valuation Marks
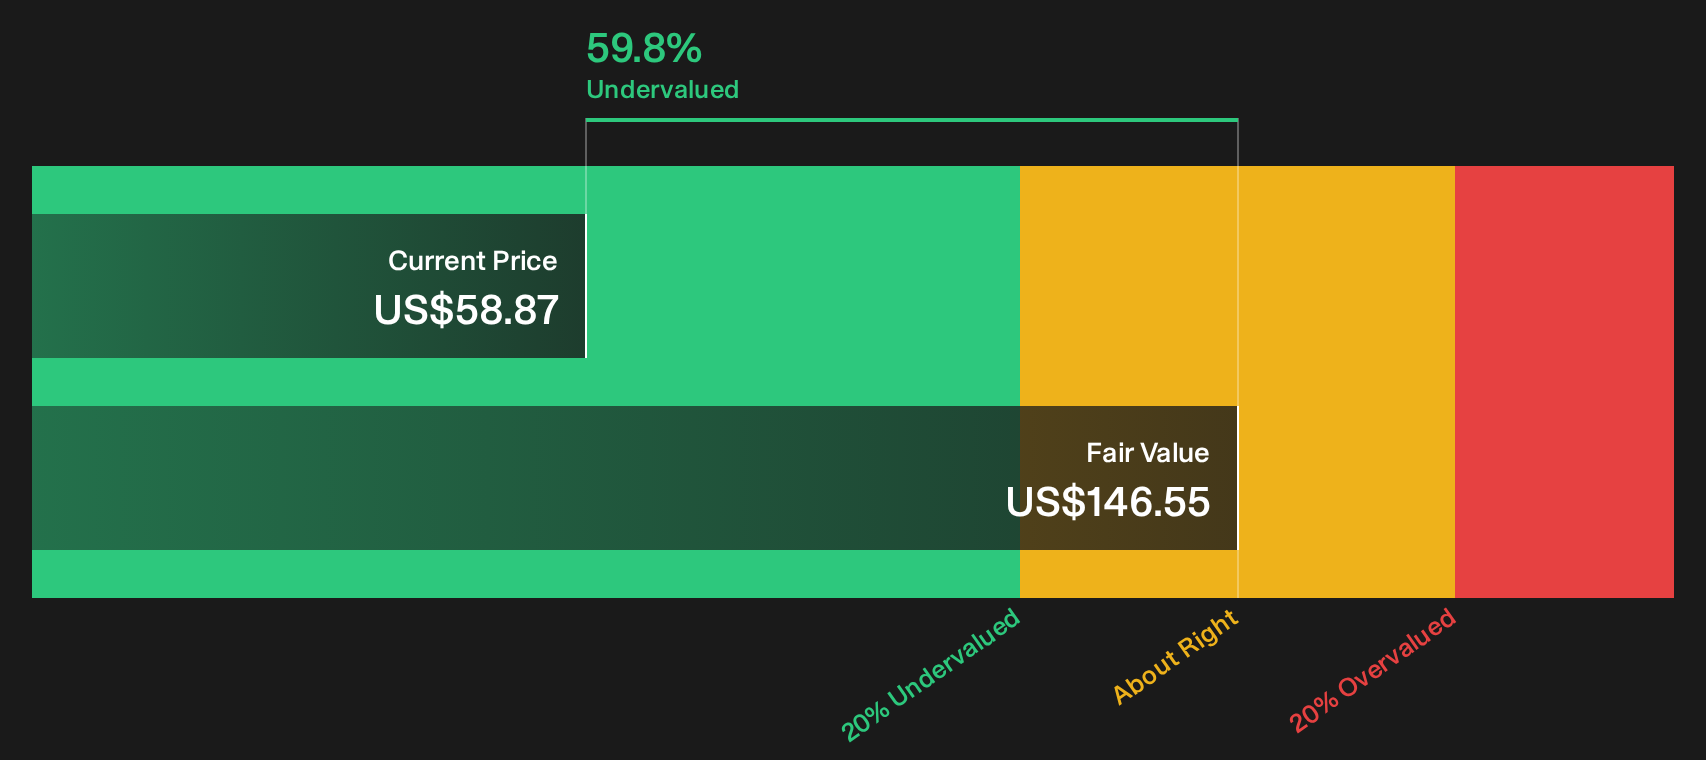
On one side, Maplebear screens as 59.8% below an estimate of future cash flow value at $146.55 using the SWS DCF model, which labels the stock undervalued. On the other, the same shares trade on a 29.3x P/E, above the US Consumer Retailing average of 18x and above the 26.5x fair ratio, which points to a richer price tag. Which signal do you treat as the anchor?
For a closer look at how that cash flow based figure is built, and what would need to hold for it to matter more than today’s earnings multiple, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Maplebear’s valuation and business momentum can pull you in either direction. Move quickly, review the data set for yourself, and weigh both the 2 key rewards and 1 important warning sign.
Looking for more Maplebear investment ideas beyond Instacart?
If Maplebear has your attention, do not stop at a single ticker. Broaden your watchlist now so you are not late to the next move.
- Consider steadier compounding by scanning a curated set of companies with healthy balance sheets through the list of solid balance sheet and fundamentals (24 results).
- Look for potential mispricing by reviewing the 32 high quality undervalued stocks that combines quality fundamentals with compressed valuations.
- Prioritize capital protection by filtering for 31 resilient stocks with low risk scores that aims to keep volatility in check while you stay invested.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com