


EN
3 British Undervalued Stocks Trading Up To 38% Below Cash Flow Value
Rising UK interest rates, flagged by the Bank of England for 2027, are putting pressure on highly leveraged businesses and stretching household budgets. Cash rich companies with solid inflows can look increasingly appealing when borrowing costs climb. This article walks through three London listed stocks that appear to trade below the cash flows implied by our valuation work, helping you focus on value opportunities the broader market may be overlooking.
The three stocks covered below are just a small sample of the opportunities flagged by this cash flow lens, with a further 20 companies on the full screen that carry similarly interesting stories not unpacked here. To sort through those ideas in detail, identify potential mispricings, and analyze which ones fit your own criteria, head straight to the Undervalued Stocks Based On Cash Flows screener.
Atalaya Mining Copper (LSE:ATYM)
Atalaya Mining Copper is a €1.28b miner focused on Spain’s Proyecto Riotinto open pit operation, where copper concentrates plus silver and gold by products underpin the cash flows that feed into this screener’s DCF work.
Atalaya Mining Copper sits near the front of this cash flow focused list because its main asset, Proyecto Riotinto, directly generates the operating inflows that underpin the screener’s DCF estimate. The bearish analyst Narrative on Simply Wall St sets a deliberately cautious bar for what those future streams might be worth.
"Although Atalaya Mining Copper has positive sectoral opinions for Proyecto Touro and EU Strategic Project status, the repeated administrative delays in final approval increase the risk that copper volumes and related revenue arrive later than many investors expect."
What happens if one key assumption about how quickly new tonnes are converted into low cost production and cash really breaks?
If that risk is on your mind, read the full narrative for Atalaya Mining Copper to see how Atalaya Mining Copper’s approval delays, cash engine and optionality could be decoupling from sentiment.
BAE Systems (LSE:BA.)
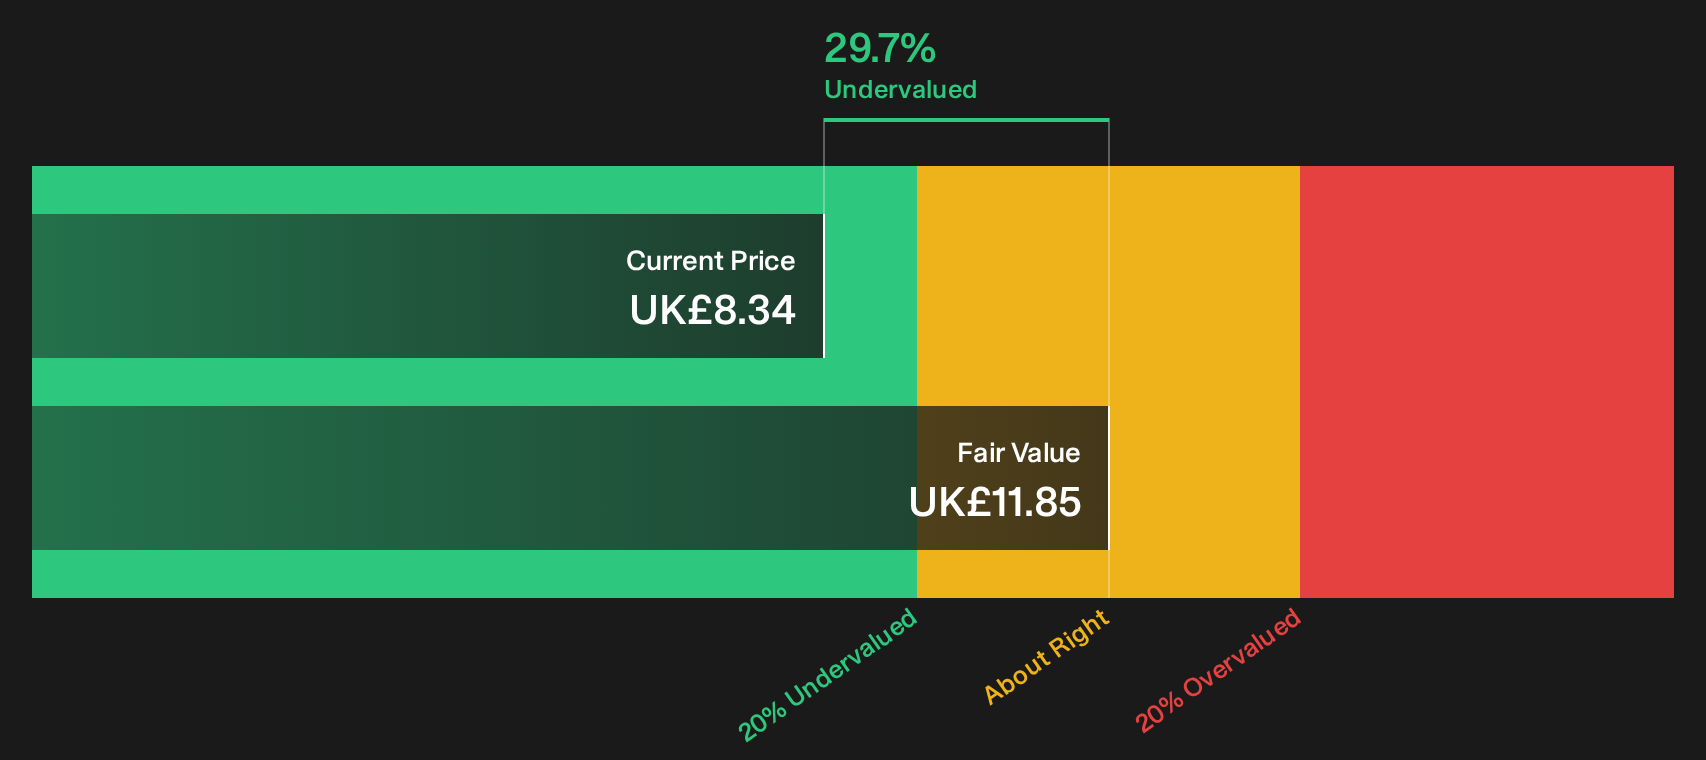
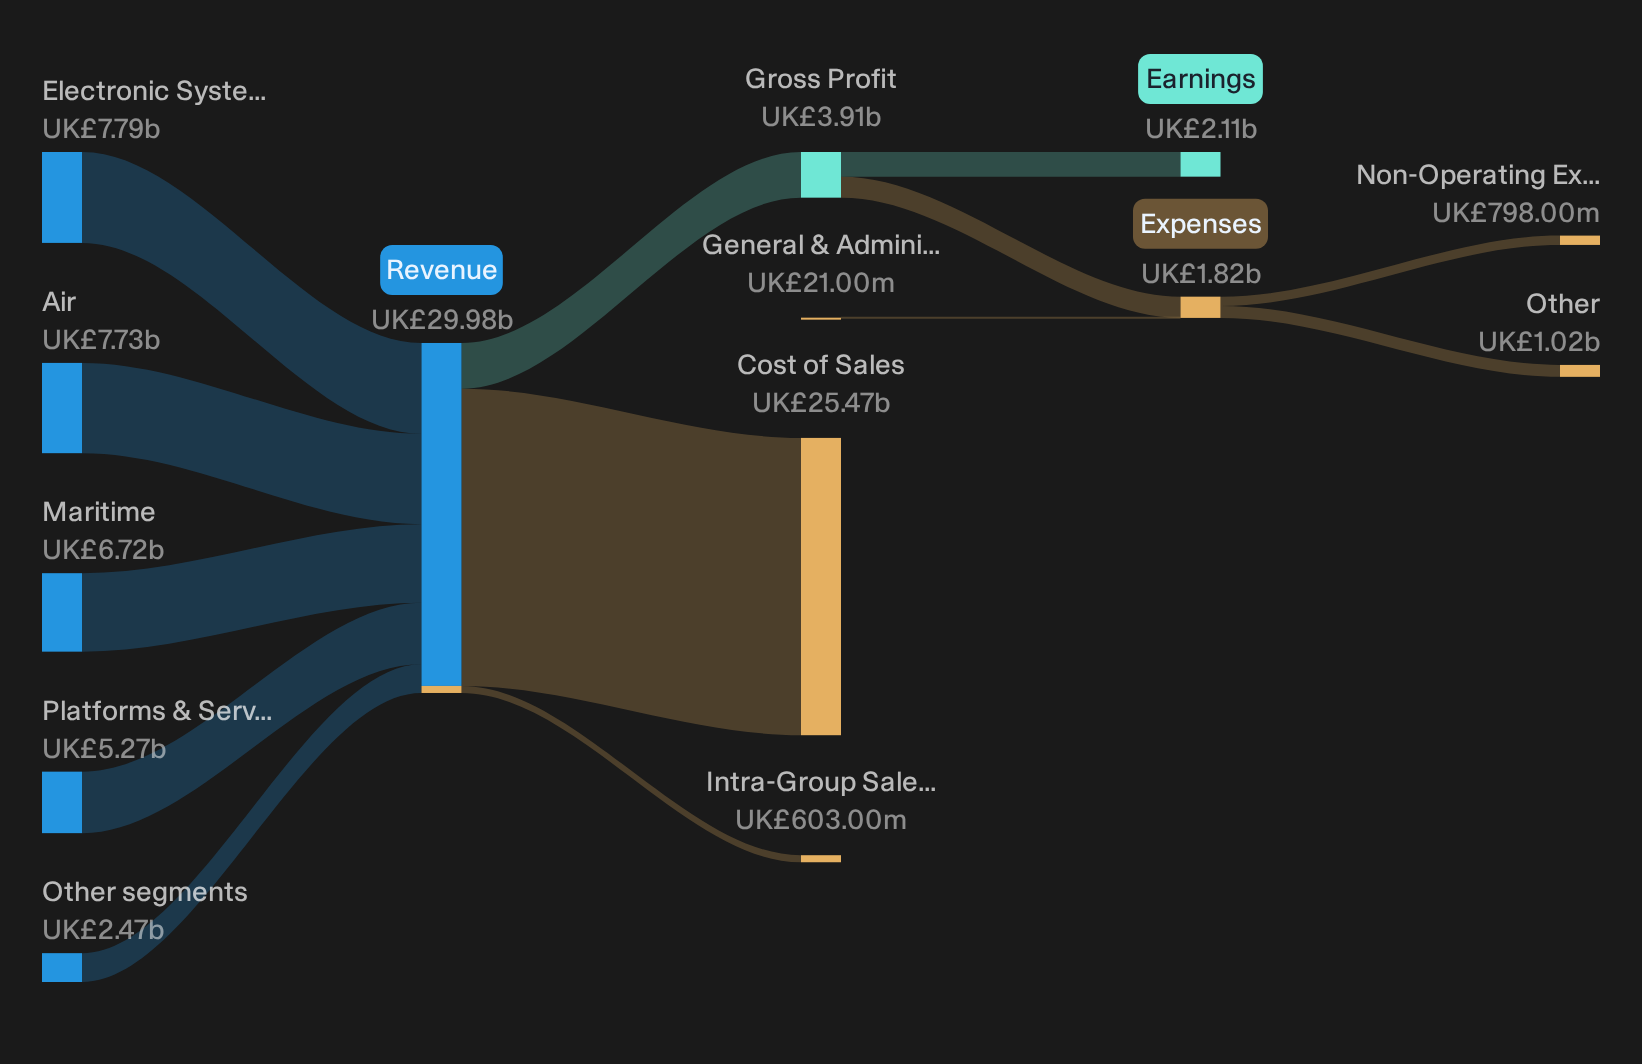
BAE Systems is a £53.35b defence and aerospace group that designs and supports military platforms, advanced electronics and cyber services. Around £7.8b comes from Electronic Systems, £7.7b from Air and £5.3b from the cash-flow-focused Platforms & Services arm among its largest revenue streams.
Where Atalaya taps commodity demand, BAE Systems leans on contract-backed defence programs, and the analyst consensus Narrative on Simply Wall St argues that a long pipeline of committed work is central to why its cash flows screen as undervalued.
"The company's order backlog reached £84b with total backlog plus incumbent program positions of around £260b, which equals about 8x annual sales and points to multi year support for revenue and earnings."
The real swing factor is how efficiently BAE Systems converts that backlog into higher-margin work without letting one stubborn cost line erode the cash story.
That efficiency question sits at the center of the full narrative for BAE Systems, where you can see how backlog, pricing power and capital discipline interact in the cash story.
Smith & Nephew (LSE:SN.)
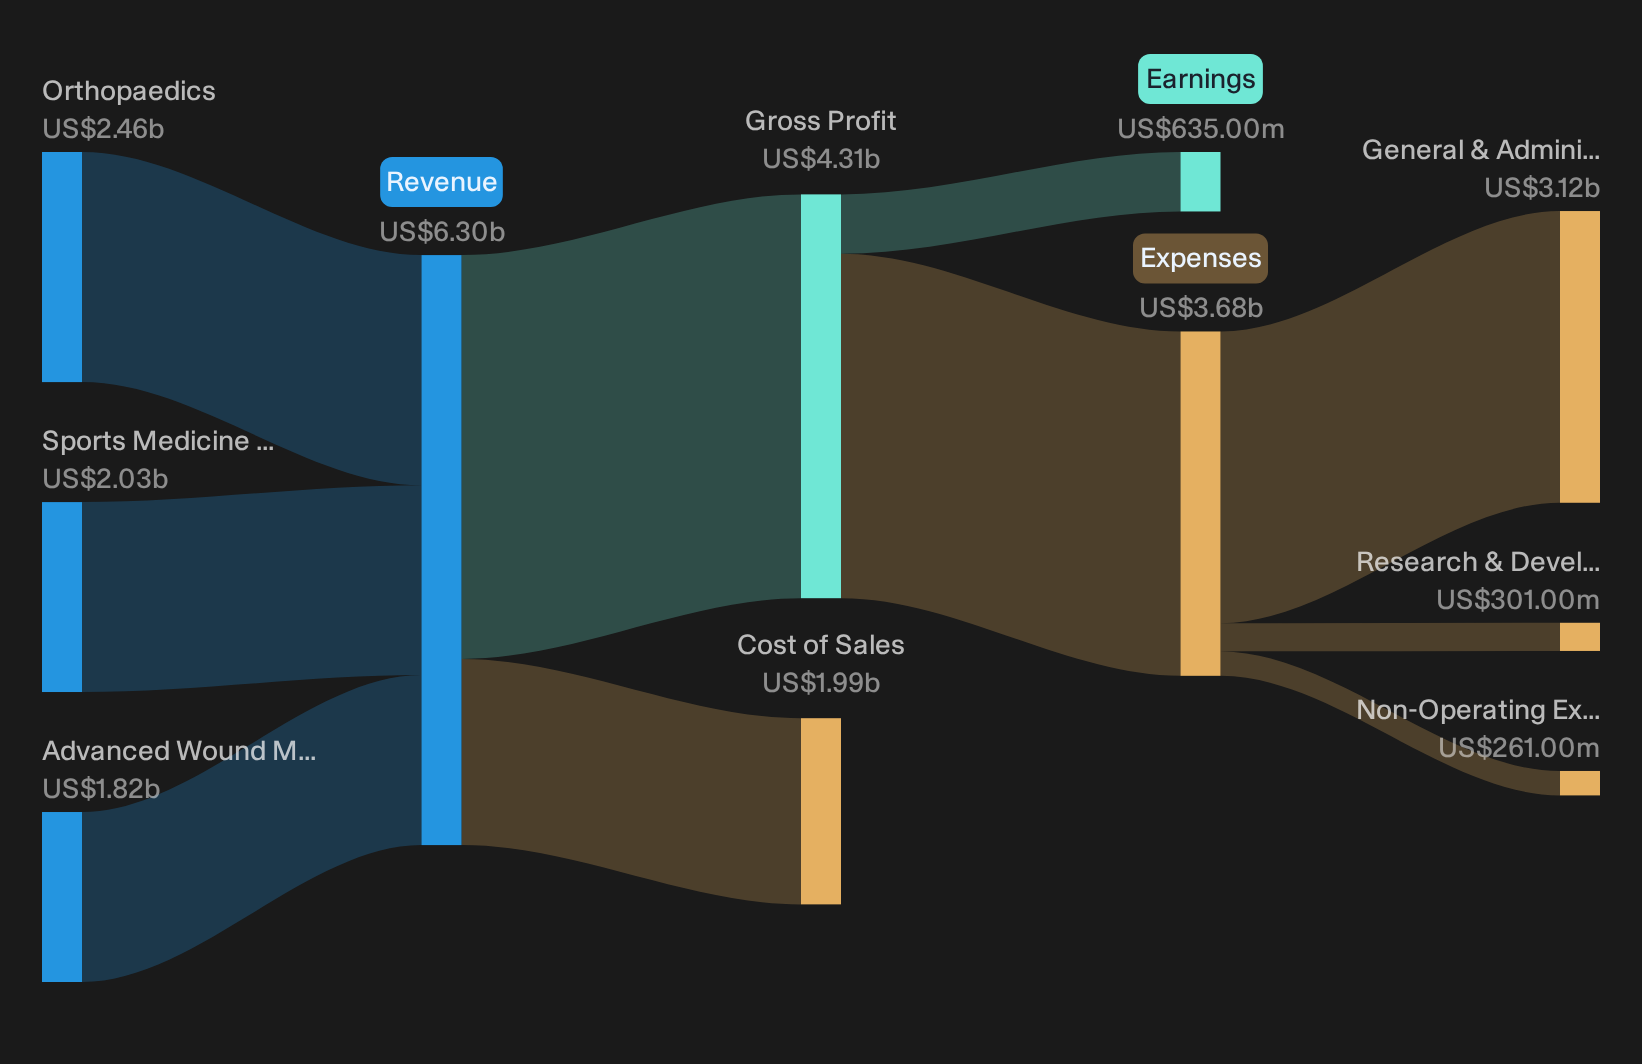
Smith & Nephew is a medical devices group focused on joint replacement, sports injury repair and wound treatments, with Orthopaedics implants providing the clearest link to durable cash flows. It generated US$2.46b from Orthopaedics, US$2.03b from Sports Medicine & ENT and US$1.82b from Advanced Wound Management, and is valued at about £9.85b.
For this cash flow focused screen, Smith & Nephew matters because its knee and hip implant franchise links repeat joint surgeries to recurring income, and the analyst consensus Narrative on Simply Wall St argues that newer robotics and enabling technologies could deepen that link.
"Growing penetration of CORI handheld robotics, with double digit growth in placements, higher utilization and greater ASC adoption, sets Smith & Nephew up to earn more recurring software, service and implant revenue per site as robotics and enabling technologies become a larger share of global joint replacement and shoulder surgery."
The real test comes if one unresolved question around how quickly these robotics driven procedures translate into higher margins moves the cash story sharply either way.
If that margin swing is what you care about, head into the full narrative for Smith & Nephew to see how robotics adoption, pricing and execution risk interact.
Seeking Alternatives Before The Crowd
Fresh ideas move first. By the time momentum is obvious, the easy part of the breakout can be gone. Scan these under the radar lists now and look at them before they become widely followed.
- Track cash rich compounders before they start moving by reviewing a curated mix of 15 high quality undervalued stocks while it still feels under the radar for now.
- Spot income workhorses that keep paying even when prices drop by lining up potential candidates from a focused pool of 4 dividend fortresses before the crowd chases yield.
- Review infrastructure players involved in AI-related activity by scanning a filtered universe of 53 AI infrastructure stocks while the market is still focused on headlines instead of underlying systems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com