


EN
How Weaker Earnings At Tootsie Roll Industries (TR) Has Changed Its Investment Story
- Tootsie Roll Industries reported third quarter 2026 results with revenue of US$229.05 million and net income of US$23.22 million, both lower than the same period a year earlier, and basic earnings per share from continuing operations of US$0.31 versus US$0.48 previously.
- Over the first nine months of 2026, Tootsie Roll Industries showed relatively steady revenue of US$534.81 million compared with US$536.25 million a year earlier, while profit and earnings per share declined more sharply, indicating pressure on profitability rather than on top line demand.
- The focus now turns to how Tootsie Roll Industries' weaker earnings and compressed profitability may influence the broader investment narrative for the business.
Broaden your watchlist beyond Tootsie Roll Industries by reviewing our hand picked 32 high quality undervalued stocks that currently pair solid fundamentals with more resilient profitability profiles.
What Is Tootsie Roll Industries' Investment Narrative?
To own Tootsie Roll Industries, you have to believe in a fairly simple story. This is a branded confectioner that relies on execution, efficient manufacturing and disciplined pricing rather than big acquisitions or heavy capital projects. The latest quarter fits that pattern on the revenue side, with third quarter and nine month sales and revenue figures staying close to last year, while profit and basic EPS from continuing operations declined. The near term question is whether management can protect earnings quality in a cost heavy environment when top line demand is only inching forward.
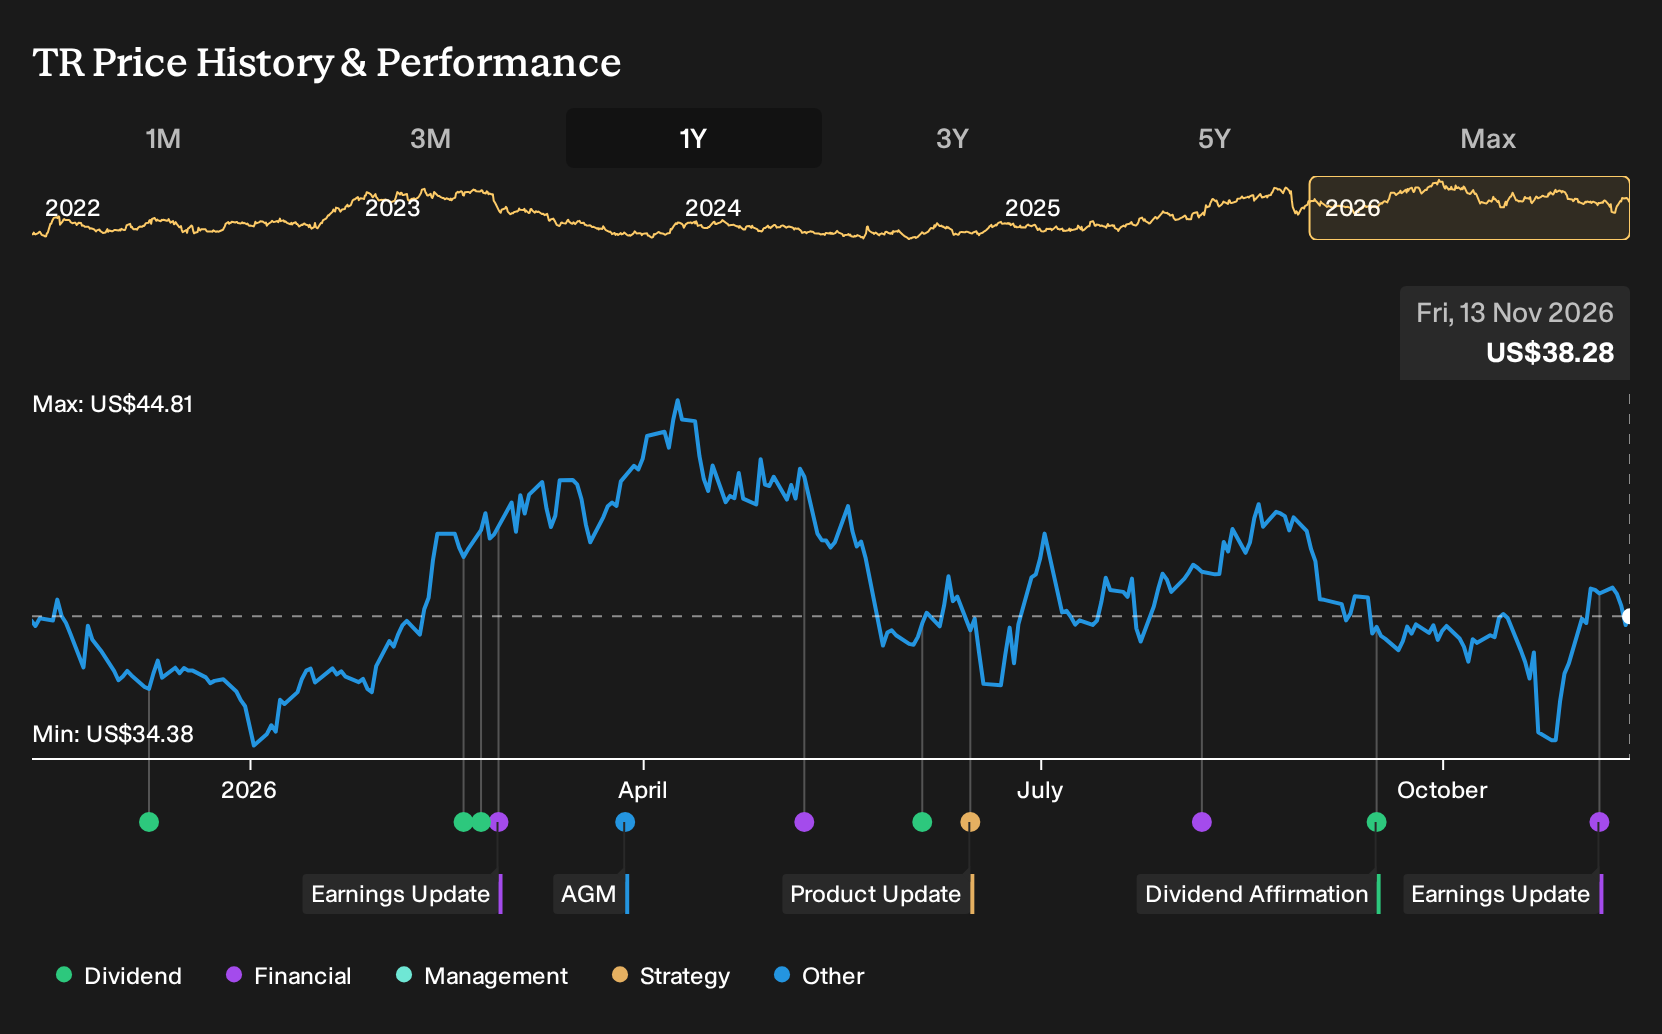
In the short term, the key catalysts are operational. That includes how effectively Tootsie Roll Industries manages input costs, runs its plants and uses its broad distribution network across supermarkets, dollar stores and online channels. The reported drop in net income and lower net profit margins compared with last year point to pressure on profitability rather than demand. That is important when the stock already trades on a P/E of 34.4x, above both peer and industry averages, because any further hit to returns on equity or earnings quality would make that valuation harder to justify.
Even so, there is a quieter issue in the background that could matter more for long term shareholders if ...
There's only one way to know the right time to buy, sell or hold Tootsie Roll Industries. Head to Simply Wall St's company report for the latest analysis of Tootsie Roll Industries's Fair Value.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- See our latest analysis for Tootsie Roll Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tootsie Roll Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Tootsie Roll Industries?
If the latest Tootsie Roll Industries earnings have you rethinking where capital is working hardest, it can help to scan a wider field of opportunities using structured filters rather than gut feel alone.
- For investors who want quality at a discount, start with a curated set of companies trading below assessed value through the 32 high quality undervalued stocks.
- If capital preservation and smoother return profiles matter most to you, focus on businesses with steadier fundamentals using our 31 resilient stocks with low risk scores.
- For those hunting for resilient balance sheets and cleaner fundamentals, cut through the noise with a list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com