


EN
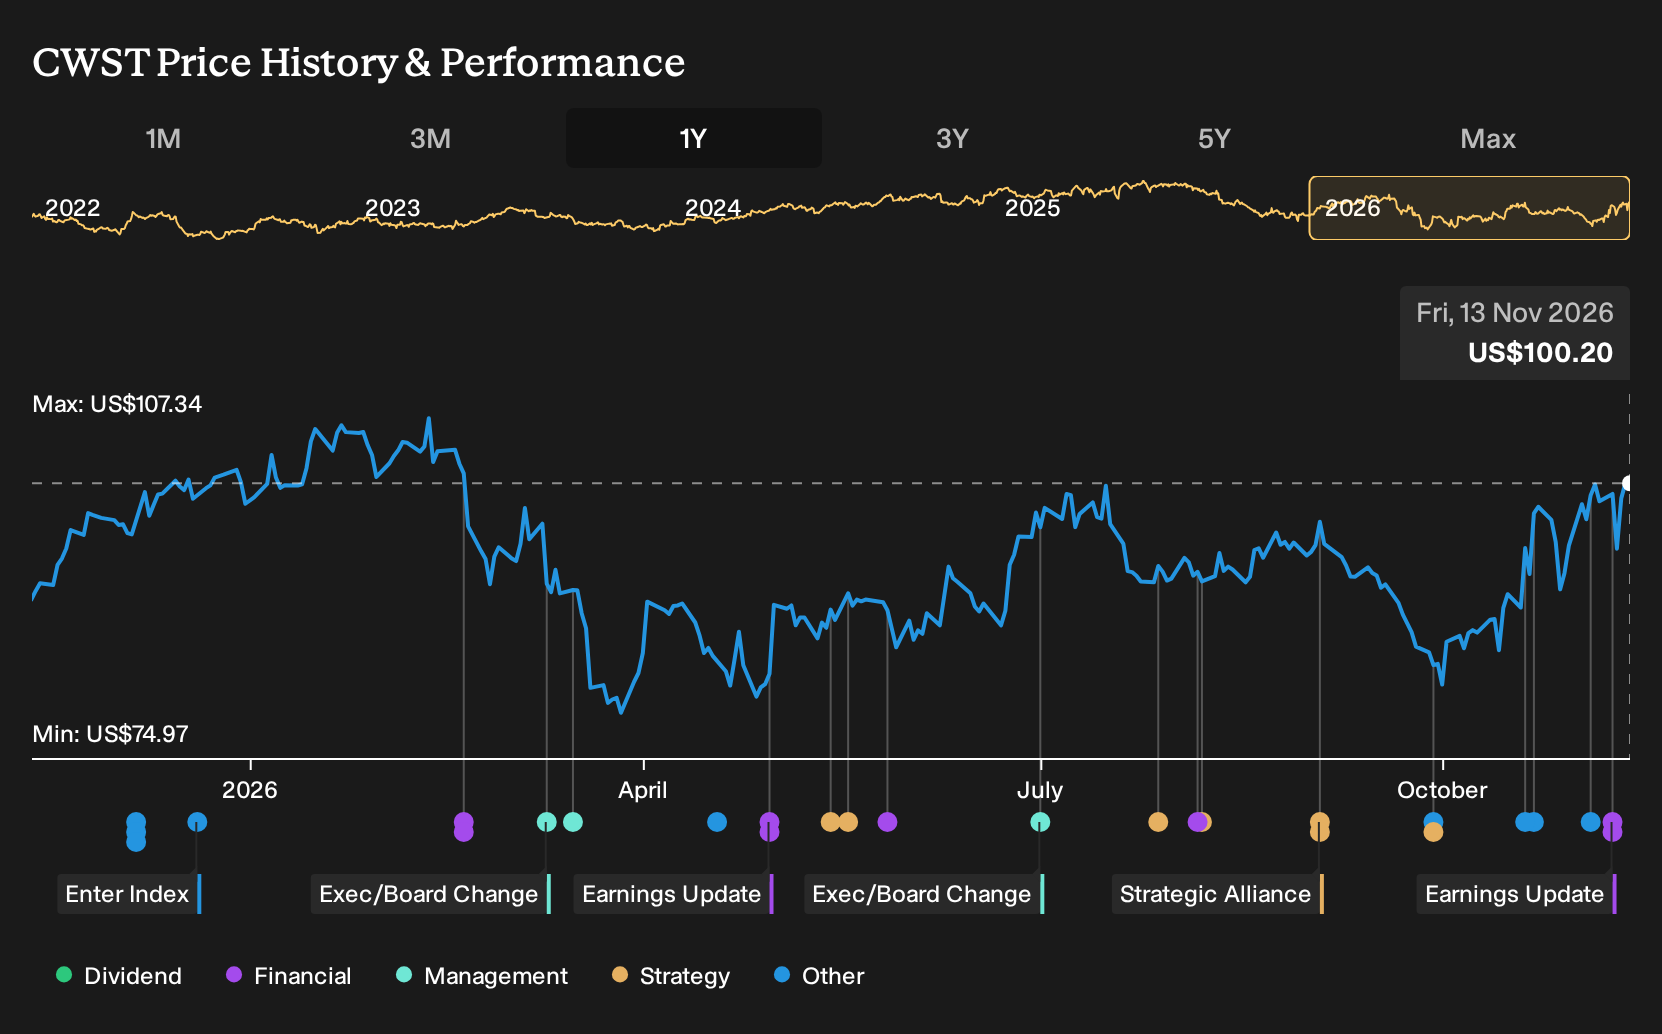
How Investors Are Reacting To Casella Waste Systems (CWST) Full Year Loss Forecast
- Casella Waste Systems reported third quarter 2026 revenue of US$559.23 million but moved from a prior profit to a net loss of US$7.02 million, and now expects a full year loss of between US$10 million and US$4 million.
- The shift to losses despite higher revenue, together with guidance that now points to a loss for 2026, highlights pressure on costs, integration, and returns on recent investments.
- Investors will now see how this swing to a guided full year loss reshapes Casella Waste Systems' existing investment narrative around margin recovery.
Scan how Casella Waste Systems compares on profitability, balance sheet strength, and valuation, alongside a curated list of solid balance sheet and fundamentals (24 results) that investors are watching closely after this guidance shift.
Casella Waste Systems Investment Narrative Recap
To stay invested in Casella Waste Systems, you need to be comfortable with a story where heavier capex, acquisitions, and landfill build outs weigh on earnings while management works to pull margins back up. The shift to a guided full year loss puts near term focus squarely on cost control, integration of Mid Atlantic assets, and returns on past spending.
The analyst consensus narrative on Simply Wall St leans on efficiency projects, automation, and higher internalization to rebuild profitability. That makes the biggest short term catalyst actual margin progress in upcoming quarters. The main risk is that cost pressures and integration expenses linger, which could keep interest coverage tight and delay any earnings recovery.
The updated 2026 guidance is the key announcement to pay attention to here. Casella Waste Systems now pairs slightly higher expected revenue of US$2.100b to US$2.110b with an anticipated net loss of US$10 million to US$4 million. That combination points to a period where volume growth and pricing are not yet flowing through to the bottom line.
This revised outlook feeds directly into the existing catalysts around automation savings, landfill internalization, and tuck in acquisition synergies. Execution now needs to show up in cleaner conversion of revenue into cash flow, especially given interest payments that are not well covered by current earnings. Any progress on operating efficiency will be weighed against that earnings guidance in upcoming updates.
Casella Waste Systems' current earnings are about US$5.7 million, and analysts expect profit to reach US$70.5 million by 2029. This would be an increase of roughly 12 times from earnings today, supported by an assumed 8.4% annual revenue growth rate and a forecast for revenues to reach US$2.5 billion in the same year.
Discover why Casella Waste Systems' fair value signals a 6% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Fair value estimates for Casella Waste Systems from 2 Simply Wall St Community members stretch from US$106.50 to about US$173.80, so retail views are far from aligned. Some lean on landfill expansion, automation projects, and consolidation as long term supports, while others flag integration risk and margin pressure. Use these disagreements to test your own thesis.
Explore another Casella Waste Systems fair value estimate, including one that suggests it could be worth just $106.50.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Casella Waste Systems research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Casella Waste Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Casella Waste Systems' overall financial health at a glance.
Looking for more Casella Waste Systems style investment ideas?
If you want to put Casella Waste Systems in context, compare it with a wider field of businesses and build a watchlist that truly fits your risk and income preferences, the Simply Wall St Screener can help you quickly surface stocks that match your criteria instead of scrolling through tickers one by one.
- If capital preservation sits high on your list, focus on companies that our models view as more resilient by starting with 31 resilient stocks with low risk scores.
- For investors hunting for strong fundamentals and balance sheets that look sturdier on basic checks, filter for companies in the list of solid balance sheet and fundamentals (24 results).
- If you are willing to research under followed ideas where fundamentals still look robust, scan through the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com