


EN
How Investors Are Reacting To Radian Group Stock (RDN) Stronger Quarterly Earnings
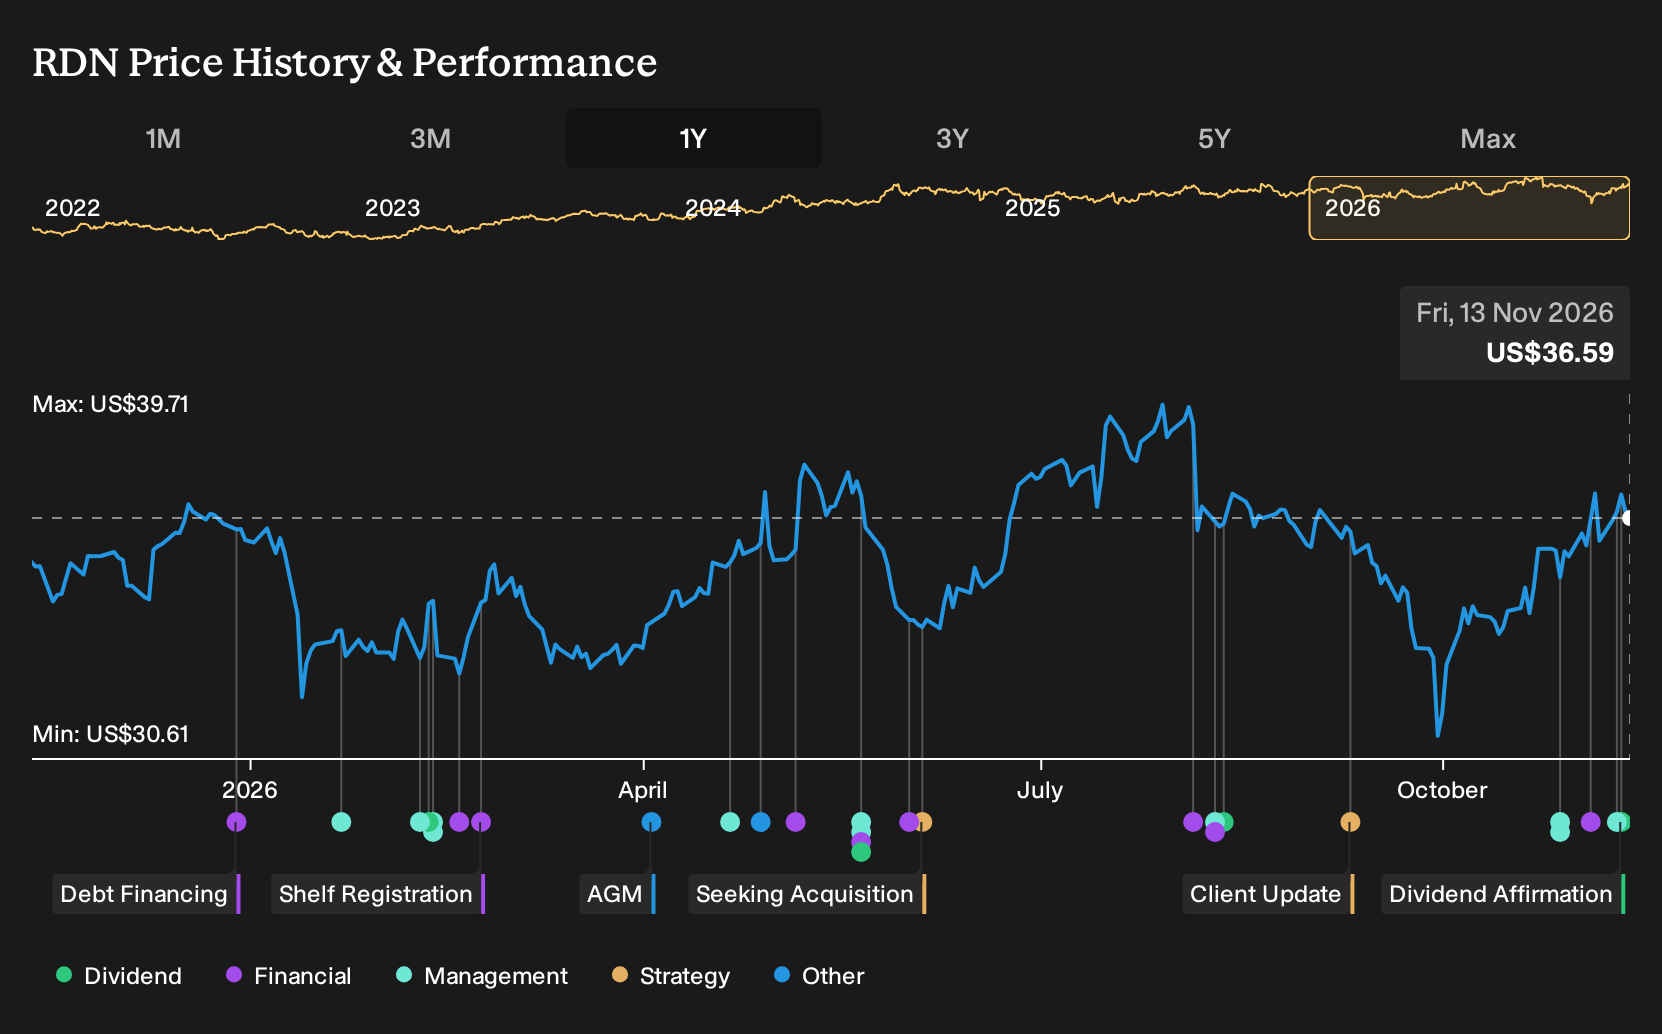
- Radian Group reported third quarter 2026 revenue of US$624.11 million and net income of US$163.66 million, and declared a quarterly dividend of US$0.255 per share payable on December 8, 2026, with the ex dividend and record dates on November 23, 2026.
- Board director Anne Leyden plans to retire effective January 31, 2027, which will reduce the Radian Group board to 11 directors and may slightly reshape governance at a time when earnings per share from continuing operations and total earnings per share are higher than a year earlier.
- The company’s stronger third quarter earnings profile is now in focus in terms of how it might influence the broader investment narrative around the stock.
Scan Radian Group alongside other income focused opportunities by reviewing our curated list of 6 dividend fortresses that pair yield with robust underlying businesses.
What Is Radian Group's Investment Narrative?
Radian Group’s story starts with a simple belief. You need to think mortgage credit risk remains a durable business where disciplined underwriting, capital management and pricing can support steady earnings rather than boom and bust swings. The latest quarter, with US$624.11 million of revenue and US$163.66 million of net income, supports that picture of a sizable, cash generating insurer that can fund a regular dividend and still invest in the franchise.
The affirmed US$0.255 dividend and the planned retirement of Anne Leyden look more like continuity than disruption. Income investors get a signal that the payout is still a priority, while the board adjustment to 11 directors keeps governance tight without a messy dispute. In the short term, the more interesting swing factor is whether Radian Group can sustain its current earnings profile with profit margins that are already below last year’s level.
That said, the part of the Radian Group story that tends to get far less airtime is ...
There's only one way to know the right time to buy, sell or hold Radian Group. Head to Simply Wall St's company report for the latest analysis of Radian Group's Fair Value.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Radian Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Radian Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Radian Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Radian Group?
If you want to benchmark Radian Group against other possibilities and widen your opportunity set, it helps to scan a few focused stock lists rather than starting from scratch with a blank watchlist.
- If preservation of capital is your first filter, start with sturdier balance sheets by reviewing a 31 resilient stocks with low risk scores that emphasises resilience over excitement.
- If you prefer businesses that already carry solid financial footing, compare Radian Group with a list of solid balance sheet and fundamentals (24 results) that can help you narrow in on companies with funding and fundamentals that look more robust.
- If you want a shot at earlier stage stories with strong underlying metrics, check out a 20 high quality undiscovered gems that focuses on quality first and profile second.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com