


EN
Missed Onto Innovation's Rally? Here's What Buyers Saw
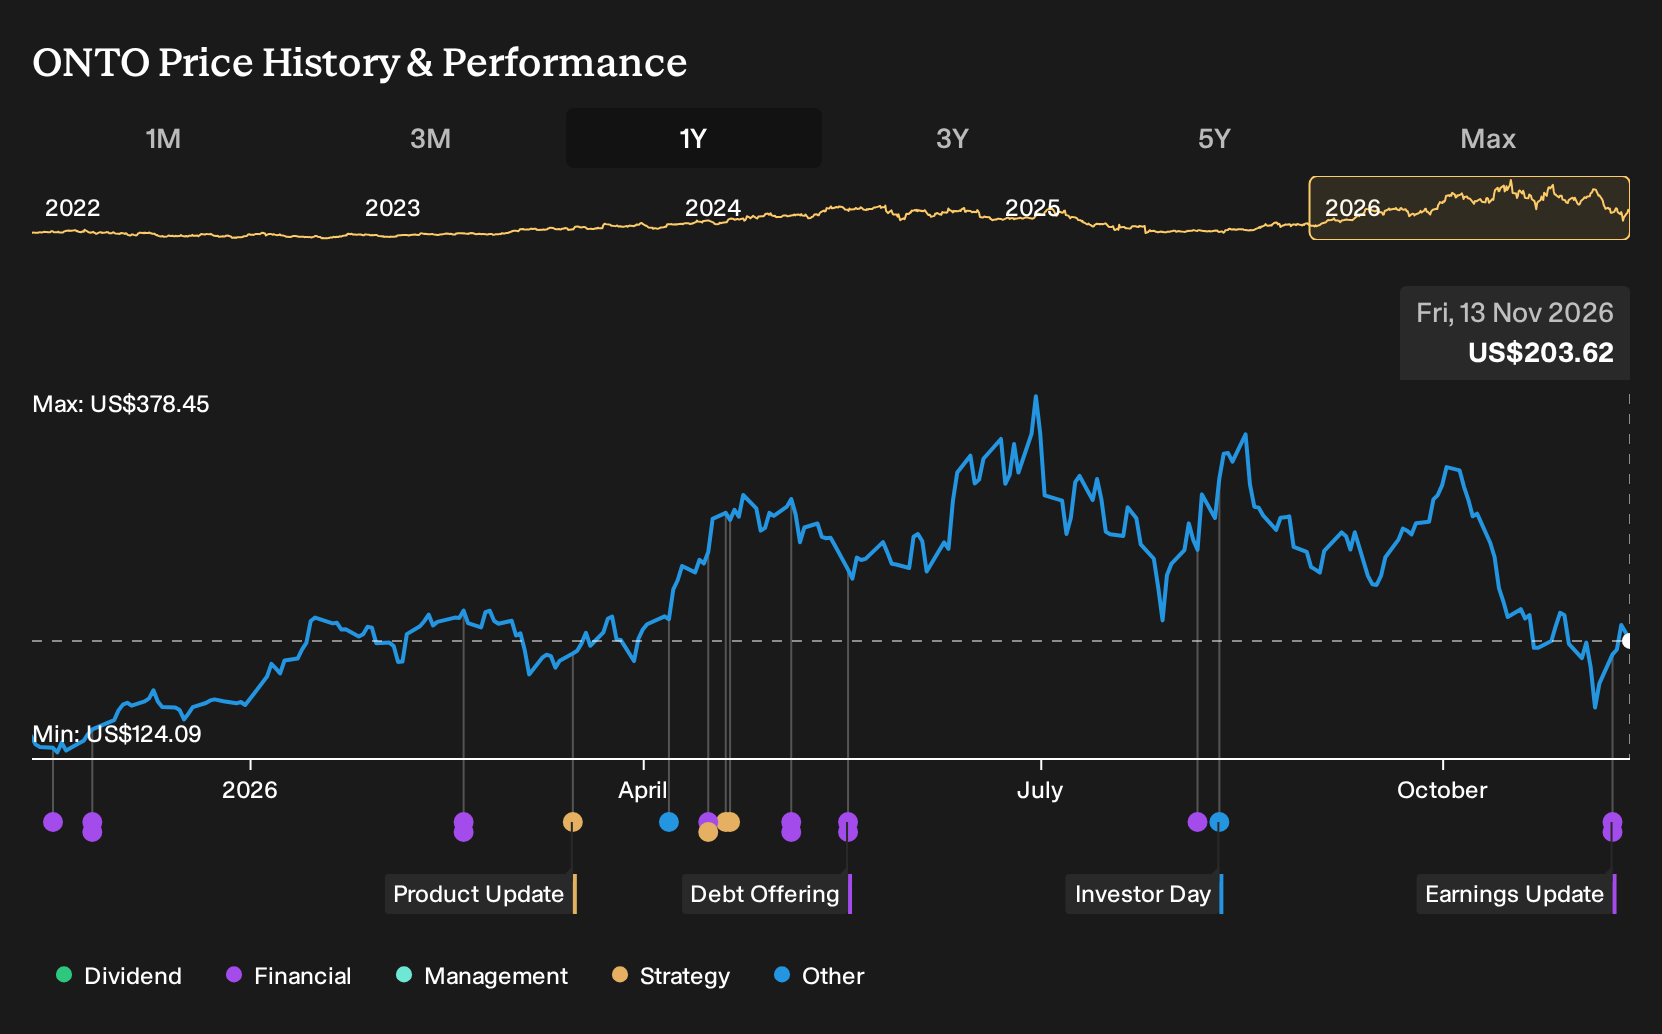
If one headline captured Onto Innovation’s year, it was the decision to commit about US$720 million for a 27% stake in Rigaku to build next generation X-ray process control tools. For Onto Innovation shareholders, the return over the past year was 59.2%, including dividends. If you were weighing a purchase back on 13 November 2025, what would you need to believe about that partnership and the wider AI packaging cycle for that outcome to feel reasonable?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The move put Onto Innovation in the middle of this trade. Scan 53 AI infrastructure stocks for other companies exposed to it.
The Two Stories Onto Innovation Investors Were Weighing
The shares cost US$130 at the start of the period, and Onto Innovation was caught between two sharply different stories about what came next.
On the upside, one bullish Narrative put Fair Value at US$182. That view leaned on AI packaging demand, wider adoption of the Dragonfly platform and Semilab products, and an assumption that earnings could reach US$352.9 million by about September 2028 on a 28.3x P/E.
On the downside, a bearish frame set Fair Value at US$90. That camp focused on rising operating costs from geopolitics and localization, tougher competition in inspection and metrology, and the risk that customer concentration would keep revenue and earnings volatile, even if profits reached US$352.9 million on a 15.9x P/E assumption.
What The Results Changed For Onto Innovation
Onto Innovation closing the US$720 million Rigaku stake and reporting Q3 2026 revenue of US$409.7 million versus US$218.2 million a year earlier supported the focus on AI packaging tools and X-ray process control. Net income also rose to US$46.8 million from US$28.2 million, although net margin slipped from 12.9% to 11.4%, so the stronger profitability narrative was only partly supported. Overall, the evidence was mixed.
The key assumption investors priced in back in November 2025 was that AI packaging demand would feed through to higher sales and sturdier margins. When you look at another chip-equipment stock, track whether revenue, operating profit and net margin all move in the same direction as the story being told about new tools or end markets.
What Onto Innovation’s Run Now Prices In
Onto Innovation shares are now at US$204, up 59.2% over the past year, and the selected Narrative’s Fair Value still sits above that level rather than below it.
According to FundamentalFlow, an investor in the Simply Wall St Community, that hinges on Onto becoming a key AI packaging bottleneck supplier, so a buyer today has to judge whether advanced packaging inspection demand really can stay on that trajectory.
"Onto Innovation is emerging as one of the most strategically important semiconductor equipment companies in the AI supply chain. While much investor attention remains focused on GPU manufacturers and memory suppliers, the next bottleneck increasingly lies in advanced packaging, the complex process of stacking, connecting, and inspecting AI chips and HBM memory at nanometer precision."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Where Onto Innovation’s Demand Connects
Onto Innovation lives close to the sharp edge of chip production. One step away, another business focuses on everything that keeps that computing useful.
Instead of inspection tools, it concentrates on moving, connecting, and securing data. Your AI packaging thesis still needs that downstream plumbing to work.
This other player treats chips as just one ingredient. Its customers care about reliable connectivity, storage traffic, and complex private cloud software.
If AI workloads keep multiplying, demand for that digital infrastructure also matters. The interesting question is how value splits between tools and the pipes around them.
That argument has a Narrative and a number behind it. → See the company one Narrative values 88% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com