


EN
Genius Sports (GENI) Lifts Revenue Guidance, Is The Stock Still Cheap?
Genius Sports (GENI) moved back into focus after its third quarter report on 5 November 2026, which paired higher sales with a narrower quarterly net loss and a modest lift to full year revenue guidance.
At a share price of US$6.26, Genius Sports has seen a 4.86% 7 day share price return and a 2.12% 30 day gain. However, the 90 day share price return is down 25.30% and the year to date move is down 41.93%, while the 1 year total shareholder return is down 35.13% and the 3 year total shareholder return is up 22.50%. This indicates that recent momentum has cooled after earlier strength.
Compare Genius Sports with a curated set of peers by scanning the 32 high quality undervalued stocks that combine solid cash flows with stronger balance sheets than many high growth stories in the market today.
Genius Sports now trades at a steep discount to both analyst targets and estimated fair value after a sharp pullback. Is that a pricing error, or is the market pricing in real risks around ongoing losses and cash burn?
Most Popular Narrative: 42% Undervalued
Genius Sports last closed at $6.26, while the analyst consensus Narrative on Simply Wall St estimates fair value at $10.83 per share. This implies a sizeable gap that investors need to understand before leaning on that upside.
Rapid adoption of interactive, real-time sports content and next-gen fan engagement technologies (e.g. BetVision, GeniusIQ, augmented broadcast, AI-driven analytics) is driving deeper integration with leagues and media partners, creating high-margin, recurring revenue streams and supporting long-term net margin expansion through product differentiation.
See why 27 investors see Genius Sports as 42% undervalued.
The fair value estimate of $10.83 is built on analyst assumptions of revenue growth around 29.7% a year, profit margins normalising from current losses to 16.9%, and a discount rate of 10.19% that reflects the risk analysts assign to Genius Sports' future cash flows. Those inputs point to a business that is still loss making today but expected by analysts to generate $292.3 million of earnings over time on a much larger top line.
Analysts also apply a future P/E of 16.2x in that framework, which they view as below the current multiple for the wider US Hospitality industry at 23.2x. That helps explain why the narrative fair value sits materially above the share price, even though there is wide dispersion between the most optimistic and most cautious forecasts and no clear consensus on how quickly Genius Sports will convert revenue into free cash flow.
Result: Fair Value of $10.83 (UNDERVALUED)
Still, the Genius Sports story can change quickly if key sports data contracts are renewed on tougher terms, or if heavy tech investment keeps free cash flow under pressure.
Find out about the key risks to this Genius Sports narrative.
Another View: What The P/S Ratio Says About Genius Sports
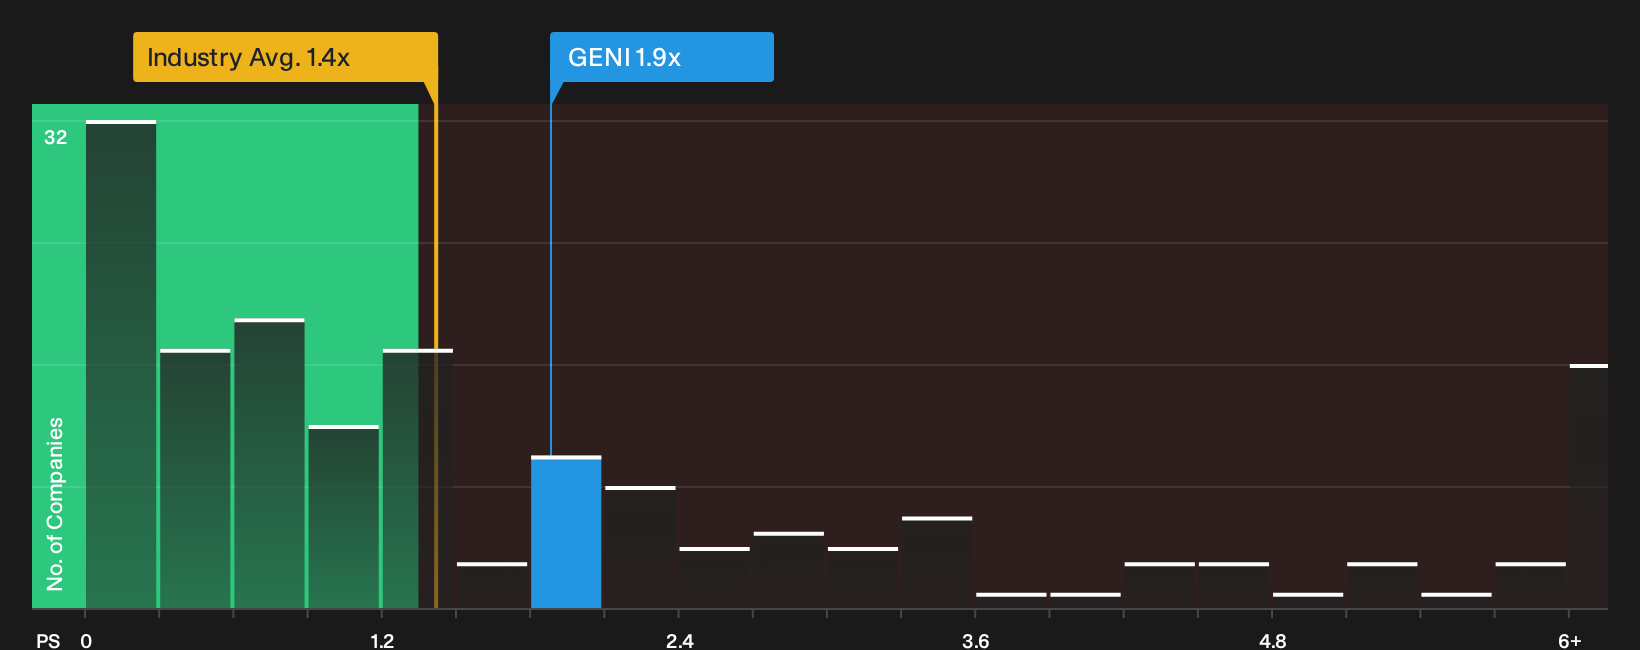
The DCF-based narrative paints Genius Sports as meaningfully undervalued, yet the P/S ratio tells a cooler story. At 1.9x sales versus a fair ratio of 1.4x, and 1.4x for both the US Hospitality sector and peers, the stock trades at a richer multiple that could limit upside if growth or margins disappoint. Which signal matters more for you?
To see how that revenue multiple stacks up against detailed earnings and cash flow assumptions, take a look at the valuation breakdown in See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the split sentiment on Genius Sports feels messy, that is exactly why the data matters. Move quickly, stress test the bullish and bearish assumptions, then weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Genius Sports?
Do not stop your research with a single ticker. The market moves quickly, and a wider watchlist can surface opportunities before they become crowded.
- Target potential mispricings by scanning a curated 32 high quality undervalued stocks that filters for quality fundamentals and compressed valuations.
- Prioritize resilience by reviewing a list of solid balance sheet and fundamentals (24 results) that can highlight companies with lower financial stress risk.
- Hunt for emerging opportunities through a 20 high quality undiscovered gems that focuses on stronger fundamentals before they reach wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com