


EN
Construction Partners (ROAD) Faces A New 2027 Outlook As Valuation Questions Return
Construction Partners (ROAD) has come back into focus after management issued fresh fiscal 2027 guidance in conjunction with a scheduled presentation at the Baird 2026 Global Industrial Conference in Chicago on November 10.
Over the past few months, momentum around Construction Partners has cooled. The share price is down 33.57% on a 90-day share price return basis and the year-to-date share price return is lower by 28.00%, even though the 5-year total shareholder return is still 105.84%.
Scan how Construction Partners compares to other contractors facing earnings resets and fresh guidance by reviewing our curated list of 32 high quality undervalued stocks.
Construction Partners has issued fresh 2027 targets into a stock that has already reset sharply. The real question now is whether the recent slide has cleared space for more upside or already used up the easy gains on valuation.
Most Popular Narrative: 35% Undervalued
At a last close of $80.75, the narrative fair value of $123.71 places Construction Partners at a sizeable discount, according to the analyst consensus Narrative on Simply Wall St. This pulls together analyst price targets and long range forecasts using a 9.9% discount rate.
Construction Partners is set to benefit from continued federal, state, and local infrastructure funding support, with proposals such as the BUILD America 250 Act pointing to higher surface transportation allocations than the IIJA and a track record of resilience under continuing resolutions. This can support public project revenue and earnings over multiple years.
See why 13 investors see Construction Partners as 35% undervalued.
Result: Fair Value of $123.71 (UNDERVALUED)
Still, the Construction Partners story can change quickly if public infrastructure funding slows or if recent acquisitions are harder to integrate than expected.
Find out about the key risks to this Construction Partners narrative.
Another View: What Multiples Say About Construction Partners
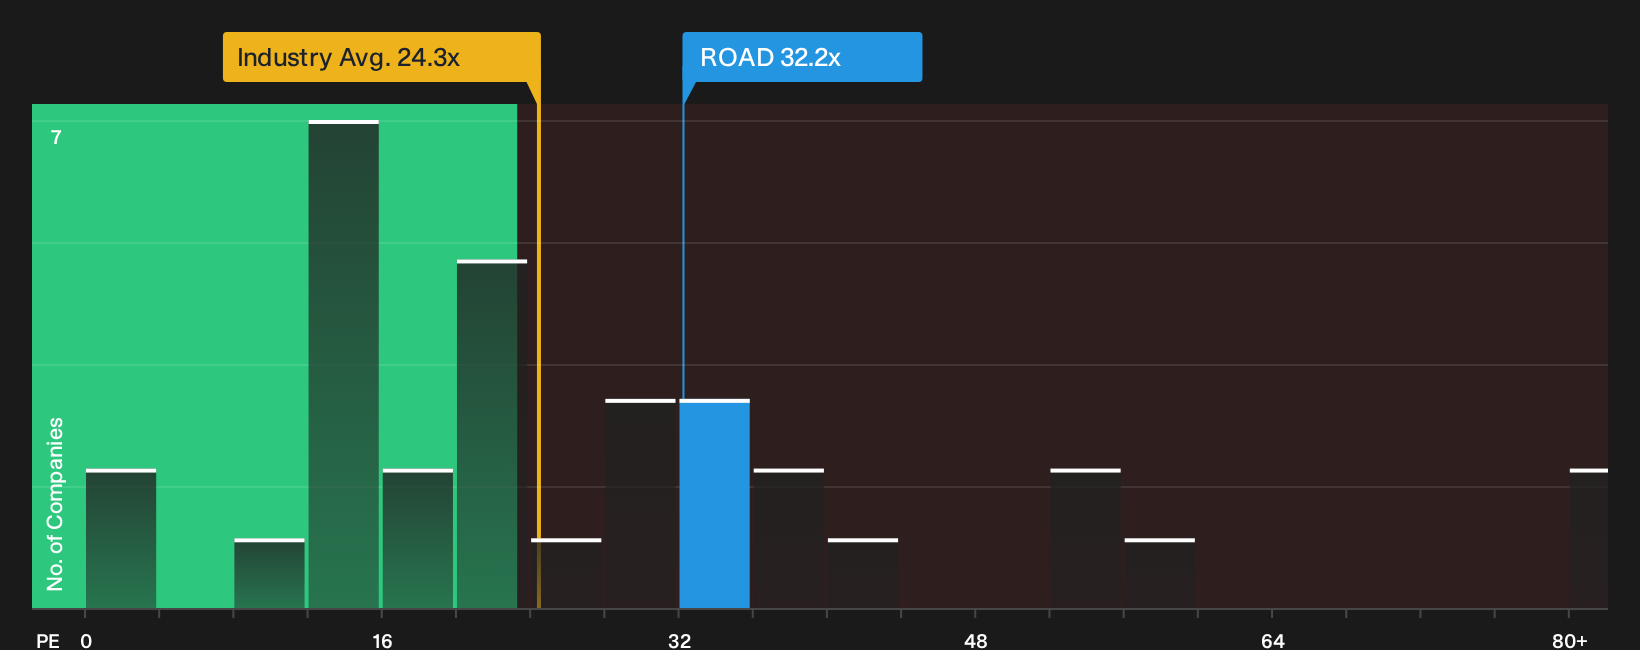
The SWS DCF model points to Construction Partners trading below an estimated future cash flow value, yet the current P/E of 32.2x is far richer than the US Construction industry at 24.4x, the peer group at 22.7x, and even the fair ratio of 23.4x. That gap can either close through stronger earnings or a lower share price. Which outcome do you think is more realistic?
For a closer look at how the P/E stacks up against what the numbers say the ratio could move toward over time, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Opinion is split throughout this Construction Partners story, with both risks and rewards on the table. Move quickly and test the numbers yourself with 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Construction Partners?
If you only focus on Construction Partners, you could miss opportunities sitting in plain sight. Spread your research and let the best setups compete for your capital.
- Target potential bargains early by scanning the market for quality businesses trading below estimated value through the 32 high quality undervalued stocks.
- Prioritise resilience in tougher periods by reviewing a list of solid balance sheet and fundamentals (24 results) that highlights companies with stronger financial footing.
- Hunt for future leaders before the crowd notices by checking out a 20 high quality undiscovered gems backed by solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com