


EN
Corsicana Lease Outlook Could Be A Game Changer For Riot Platforms Stock (RIOT)
- Riot Platforms reported third quarter 2026 revenue of US$181.43 million with net income of US$4.03 million, while nine month results showed US$522.88 million in revenue alongside a net loss of US$733.61 million and ongoing impairment charges on property and equipment.
- The results underline how the shift toward large AI data center leases, including the Corsicana agreement with a frontier AI lab, is reshaping Riot Platforms’ earnings mix and placing execution on long duration infrastructure projects at the center of its financial story.
- We will now look at how Riot Platforms’ investment narrative is affected by the Corsicana AI lease, which is driving long term lease exposure.
Compare Riot Platforms’ AI buildout story with a curated set of potential peers by scanning 53 AI infrastructure stocks now that capital intensive data center projects are reshaping earnings profiles across the sector.
Riot Platforms Investment Narrative Recap
To own Riot Platforms, you have to buy into the shift from a volatile Bitcoin mining story to a long duration AI infrastructure landlord. The third quarter showed that transition is still financially bumpy, with US$181.43 million of revenue but only US$4.03 million of net income and a much larger nine month loss. The near term operating swing factor is execution on data center builds and getting Corsicana and other capacity ready for tenants.
The biggest short term catalyst is visible progress on construction, energization and tenant ramp at AI campuses that can move Riot Platforms toward more recurring lease revenue. The main operational risk is funding and timing. The business relies on a US$573 million interim facility and continues to record sizable impairments, so delays, cost overruns or weaker Bitcoin prices would keep pressure on earnings and liquidity.
The most relevant fresh data point is the latest quarterly report. It shows nine month revenue of US$522.88 million alongside a reported net loss of US$733.61 million and ongoing impairment charges on property and equipment, including US$18.45 million in the third quarter. For an investor, that combination underlines how capital heavy this pivot is and how much is still being spent before long term AI leases fully contribute.
For catalysts, you are watching whether Riot Platforms can bridge the period between heavy construction spend and future Corsicana and Rockdale rent inflows without stressing the balance sheet. Analysts cited in the analyst consensus Narrative on Simply Wall St already point to the importance of project financing replacing the interim facility. The current loss profile, plus impairment trend, keeps execution risk around financing, construction and tenant ramp front and center for the story.
Riot Platforms' current analyst narrative points to forecast 2029 revenue of US$1.8b and earnings of US$217.8 million. This is based on an assumed 37.7% yearly revenue growth rate and a move from current earnings of a US$1.4b loss to positive earnings, which implies an earnings swing of about US$1.6b by 2029.
Uncover how Riot Platforms' fair value indicates a 62% potential upside to its current price before the discount to the market narrative closes.
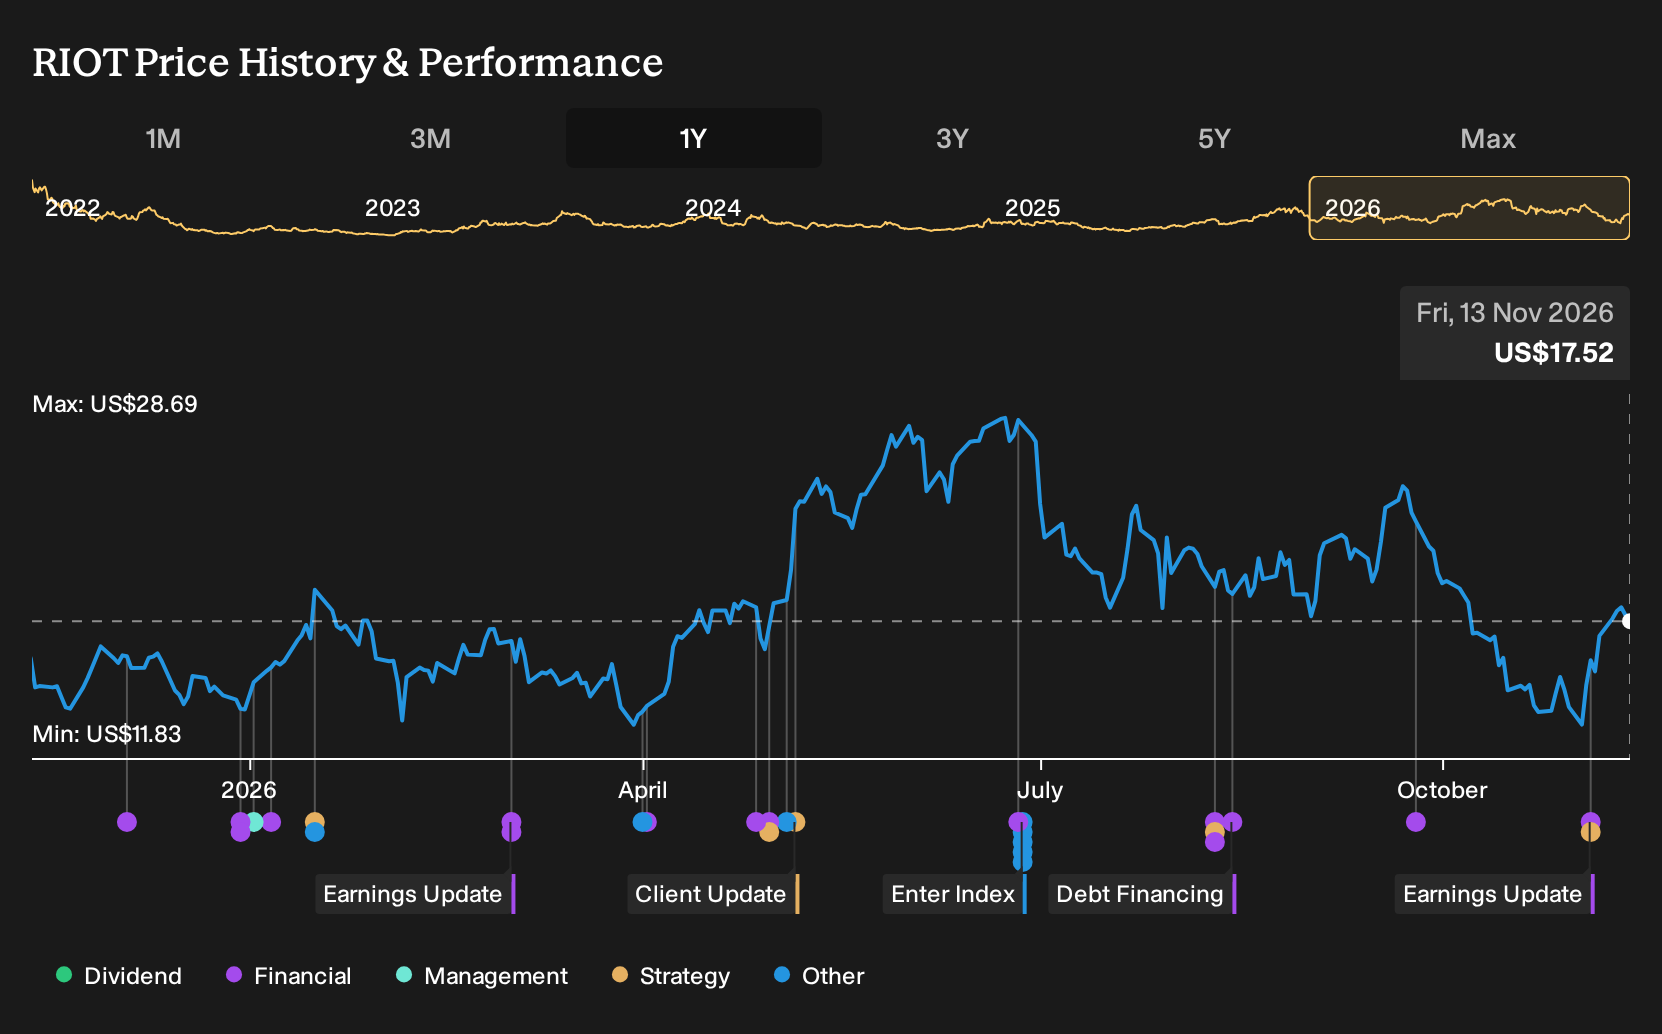
Exploring Other Perspectives
One alternate view focuses on profitability risk. The most pessimistic analysts were working with 2029 revenue of about US$994.2 million and earnings of only US$122.8 million, or even a loss of US$1.6b, before this latest Riot Platforms earnings report. That gap shows how sharply opinions can differ. It therefore makes sense to compare several narratives and decide which assumptions feel closest to your own.
Explore 3 other Riot Platforms fair value estimates, including one that suggests the potential for as much as 14% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Riot Platforms research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Riot Platforms. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Riot Platforms' overall financial health at a glance.
Looking For More Ideas Beyond Riot Platforms?
If the Riot Platforms story has you thinking about portfolio balance, it can help to line it up against other opportunities with very different risk and income profiles. The Simply Wall St Screener makes that comparison easier by letting you filter for the traits that matter most to you, from stability to income to future potential.
- If capital preservation and a smoother ride matter to you, start with a set of companies screened for resilience and lower risk scores through 31 resilient stocks with low risk scores that might help anchor a more volatile portfolio.
- If a strong financial footing is your priority, focus on businesses filtered for robust balance sheets and solid fundamentals via the list of solid balance sheet and fundamentals (24 results) to see which candidates line up with your risk tolerance.
- If you are hunting for potential outliers before they are widely followed, broaden your watchlist with a curated selection of 20 high quality undiscovered gems that pair quality fundamentals with lower current visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com