


EN
DLocal (DLO), Why Is Its Latest Update Drawing Attention?
Earnings snapshot and what changed for DLocal stock
DLocal (NasdaqGS:DLO) just posted its third quarter 2026 report, with higher sales, net income and earnings per share than a year earlier, alongside fresh commentary on volumes, regulation and foreign exchange pressure.
The firm reported third quarter sales of US$398.05 million compared with US$282.48 million a year earlier. Net income for the period was US$67.83 million versus US$51.83 million, with basic earnings per share from continuing operations at US$0.24 compared with US$0.18.
Diluted earnings per share from continuing operations came in at US$0.23 compared with US$0.17. For the first nine months of 2026, DLocal reported sales of US$1.13b compared with US$755.7 million a year earlier and net income of US$164.44 million versus US$141.27 million.
Across those nine months, basic earnings per share from continuing operations were US$0.57 compared with US$0.49, while diluted earnings per share were US$0.56 versus US$0.47. Management commentary pointed to strong total payment volume, deeper merchant relationships and improved operating leverage backing these headline figures.
Alongside the income statement, DLocal highlighted an expanded regulatory footprint with 42 licenses and registrations in 26 markets. That wider authorization base supports its cross border payment offering to global merchants across sectors such as commerce, streaming, ride hailing, financial services and gaming.
Guidance for total payment volume and gross profit was maintained, but management expects foreign exchange headwinds and softer conditions in some smaller markets to moderate operating profit growth for the full year. Currency effects in Brazil, Mexico and Argentina were singled out as key pressure points.
Market reaction around the announcement was mixed. The business beat one widely watched earnings per share estimate but posted revenue slightly below some analyst expectations, and the stock fell 2.9% in after hours trading on November 12, 2026 according to the provided data.
Beyond the income statement, DLocal also used its balance sheet more actively. The company repurchased about US$34.04 million of shares in the quarter and completed a wider buyback program, while also signing a US$150 million credit facility to fund general corporate uses, including further repurchases.
DLocal’s latest figures land against a share price that has eased in recent weeks, with a 30 day share price return of down 6.81% and a 90 day move of down 3.39%. Over a 1 year period the total shareholder return is up 1.78%, while the 5 year total shareholder return is down 60.66%. This points to fading short term momentum but a still mixed long term record as investors weigh strong payment volume growth against foreign exchange risks and the impact of buybacks at a US$13.69 share price.
Capitalize on what DLocal’s latest results reveal about cross border payments by scanning a curated set of resilient enablers in emerging markets via 20 high quality undiscovered gems.DLocal now trades below recent levels even after reporting higher sales and earnings. Is more of the upside still ahead, or has most of the rerating already played out in the valuation?
Most popular narrative: 73% undervalued
DLocal closed at $13.69, while the most followed narrative on Simply Wall St assigns a fair value of $50.96. This points to a deep discount that some investors see as driven by cash generation and balance sheet strength rather than short term sentiment.
DLocal trades below the value implied by discounting its own free cash flow. On a two-stage model running 10 years of +25.0% growth fading to a 2.5% terminal rate, discounted at 9.8%, the shares are worth USD 50.96 against a market price of USD 15.24, a 70% discount, or +234% to fair value. 58% of that value sits in the terminal period. This is the honest caveat: the further out the cash flow, the more the answer is a statement about assumptions rather than about this year.
See why 11 investors see DLocal as 73% undervalued.
That argument comes from J_Tyrader, a Simply Wall St Community investor who focuses on free cash flow, and it leans on high returns on equity and strong conversion of revenue into cash alongside a net cash position to support the case that the current DLocal share price does not fully reflect those characteristics.
Result: Fair Value of $50.96 (UNDERVALUED)
Still, DLocal’s story depends heavily on ambitious long term cash flow assumptions and on cross border payment volumes remaining resilient in the face of potential regulatory or FX shocks.
Find out about the key risks to this DLocal narrative.
Another view on DLocal’s valuation
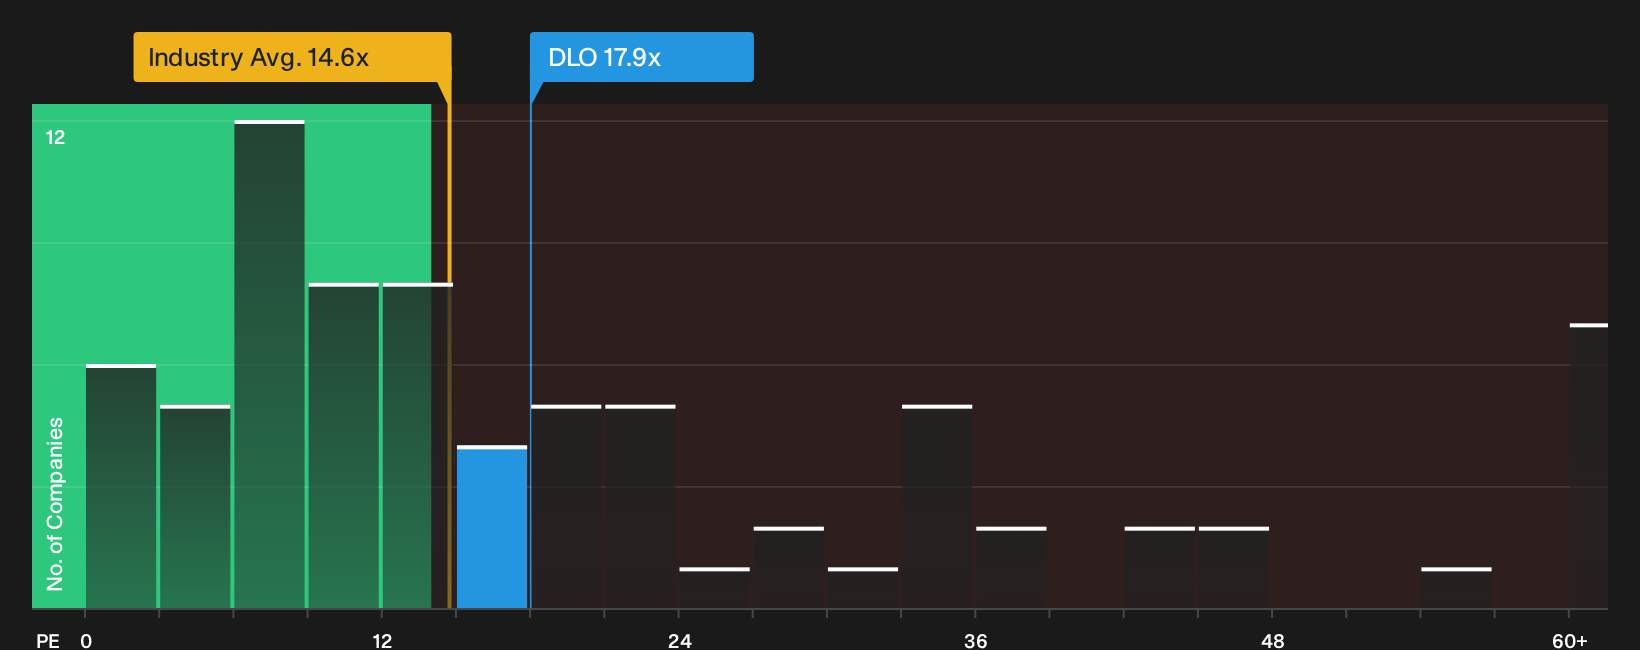
DCF fans see DLocal as deeply undervalued, yet the P/E picture is more cautious. The stock trades on 17.9x earnings compared with a 15.3x fair ratio and a 14.6x industry average, even though it screens cheaper than a 37.2x peer group. Is that a margin of safety or a premium in disguise?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this DLocal update leans optimistic, yet the real edge comes when you interrogate the numbers yourself and pressure test the assumptions. To see what those positives look like in a structured way, take a closer look at the 4 key rewards.
Ready to hunt for more opportunities beyond DLocal?
If DLocal’s update sharpened your thinking, do not stop here. The next edge often comes from comparing ideas side by side and spotting patterns others ignore.
- Target resilient strength by reviewing companies with stronger balance sheets and fundamentals through the list of solid balance sheet and fundamentals (24 results).
- Zero in on value potential by checking the 32 high quality undervalued stocks that combine quality fundamentals with pricing that has not fully caught up.
- Search for future standouts by scanning the 13 elite penny stocks with strong financials that already show solid financial traits instead of just hype.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com