


EN
Motorola Solutions (MSI) Just Gave Investors Something To Think About
Motorola Solutions (MSI) moved back into focus after its third quarter earnings release, where higher revenue coincided with lower net income, and the company raised its full year 2026 revenue guidance.
Recent trading suggests investors are leaning into that guidance. Motorola Solutions has logged a 30-day share price return of 17.6% and a year to date gain of 39.4%. The 5-year total shareholder return of 122.6% points to momentum that has built gradually rather than appearing overnight.
Scan beyond Motorola Solutions and size up other potential beneficiaries of rising demand for critical communications and security with our hand picked 31 resilient stocks with low risk scores list.
After a near 40% climb this year and a fresh revenue outlook from Motorola Solutions, the real tension is simple: pay up at US$531.20 today or wait and risk sitting out further repricing as the valuation case unfolds next.
Most Popular Narrative: 2% Undervalued
On the analyst consensus Narrative on Simply Wall St, Motorola Solutions carries a fair value of $541.82 against a last close of $531.20. This indicates a small implied upside while anchoring expectations to detailed earnings and revenue forecasts.
The transition toward a greater mix of software and managed or recurring services, reinforced by multi year LMR infrastructure and services contracts tied to the D Series P25 refresh and by large ten year arrangements such as the US$139 million Louisiana award, continues to create operating leverage that can support net margin and earnings over time.
See why 35 investors see Motorola Solutions as 2% undervalued.
Result: Fair Value of $541.82 (UNDERVALUED)
Still, Motorola Solutions depends heavily on long dated public safety contracts, as well as on newer areas like Silvus and D Fend continuing to scale without margin strain.
Find out about the key risks to this Motorola Solutions narrative.
Another View: Multiples Paint A Richer Picture For Motorola Solutions
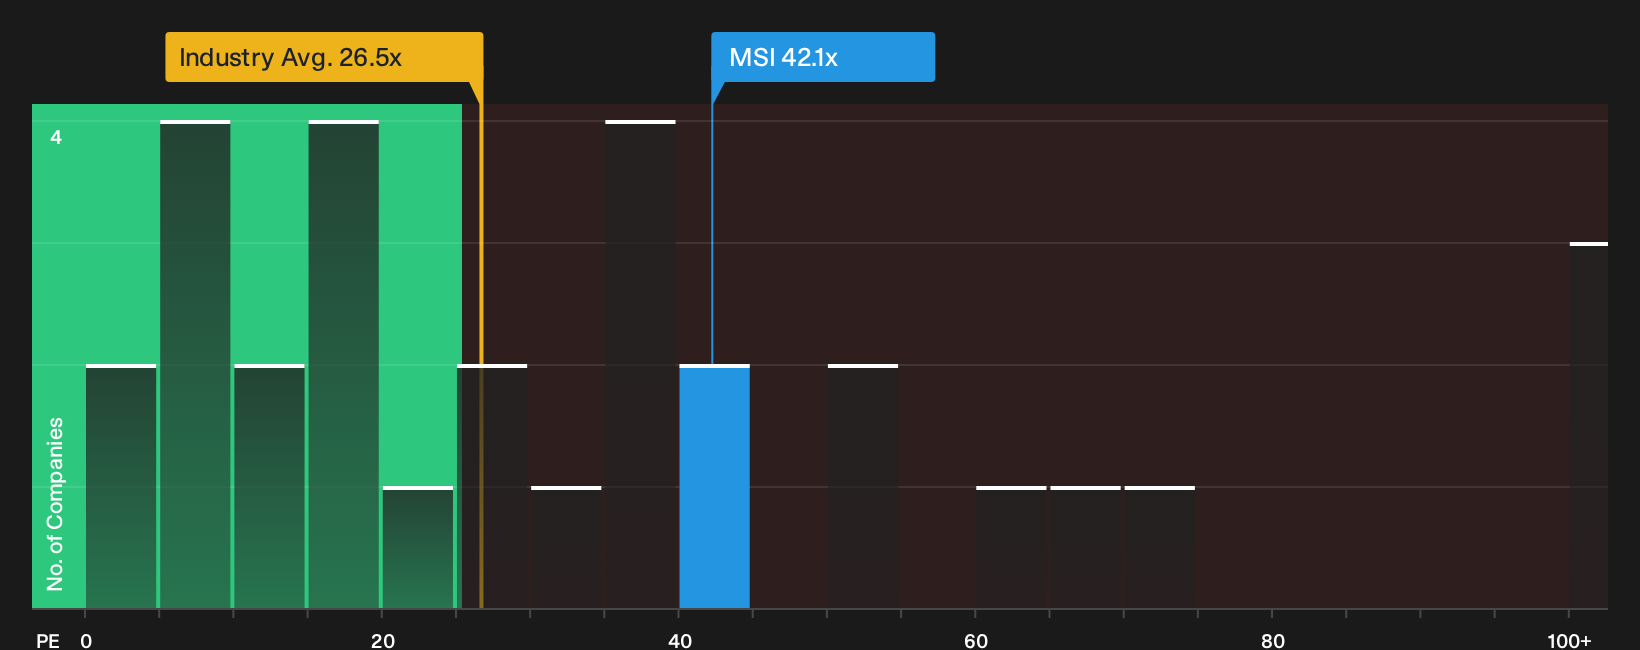
The Simply Wall St fair value narrative suggests Motorola Solutions is around 2% undervalued, yet the P/E tells a tougher story. At 42.1x earnings, the stock trades above the US Communications industry on 26.6x and far above its own fair ratio of 27x. That gap points to meaningful valuation risk if sentiment cools. Are you comfortable paying that premium for this growth profile?
For a closer look at how that premium stacks up against peers and the fair ratio, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed feelings after a big run like Motorola Solutions has had are normal, so review the situation promptly, inspect the numbers and form your own stance using 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Motorola Solutions?
If you stop at Motorola Solutions, you risk missing other opportunities that fit your style, your risk tolerance, and the kind of portfolio you actually want.
- Target resilient potential by scanning a list of solid balance sheet and fundamentals (24 results) that focuses on companies with balance sheets built to handle stress.
- Hunt for mispriced quality using the 20 high quality undiscovered gems and spot businesses with fundamentals that are not yet crowded with attention.
- Stack income candidates by reviewing a 6 dividend fortresses that filters for higher yielding payers with a focus on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com