


EN
Choice Hotels International (CHH) Cuts 2026 Guidance As Valuation Looks Fully Valued
Choice Hotels International (CHH) cut its full year 2026 earnings guidance after third quarter results, citing higher marketing and reservation system expenses related to franchisee tools and guest delivery investments.
The guidance cut lands after a strong run in the share price, with a 30 day share price return of 14.83% and year to date share price return of 23.60%. The 1 year total shareholder return of 26.38% contrasts with a 5 year total shareholder return that is down 18.05%, suggesting that momentum in Choice Hotels International has been strong in the near term but softer over a longer holding period.
Scan beyond Choice Hotels International and line up other consumer-focused businesses showing sharp momentum and fresh catalysts with the curated 20 high quality undiscovered gems.
Bulls see Choice Hotels International investing through a temporary earnings hit, while bears see a maturing story wrapped in rich pricing. Which case do the current valuation signals actually support?
Most Popular Narrative: 3.6% Overvalued
Choice Hotels International last closed at $118.78, while the analyst consensus Narrative on Simply Wall St estimates fair value at $114.60 using a 9.51% discount rate. That gap frames a story where the current price leans ahead of the modelled fundamentals.
The main thing that has to go right is that Choice Hotels International converts its technology and AI investments into better franchisee economics and demand generation, so tools like CHARLIE and EasyBid continue to lower franchisee costs and support higher quality revenue across the system.
See why 2 investors see Choice Hotels International as 4% overvalued.
Result: Fair Value of $114.60 (OVERVALUED)
Still, Choice Hotels International faces pressure if its roughly 300 basis point U.S. RevPAR gap persists or if higher interest and tax costs continue to erode EPS guidance.
Find out about the key risks to this Choice Hotels International narrative.
Another View: What P/E Says About Choice Hotels International
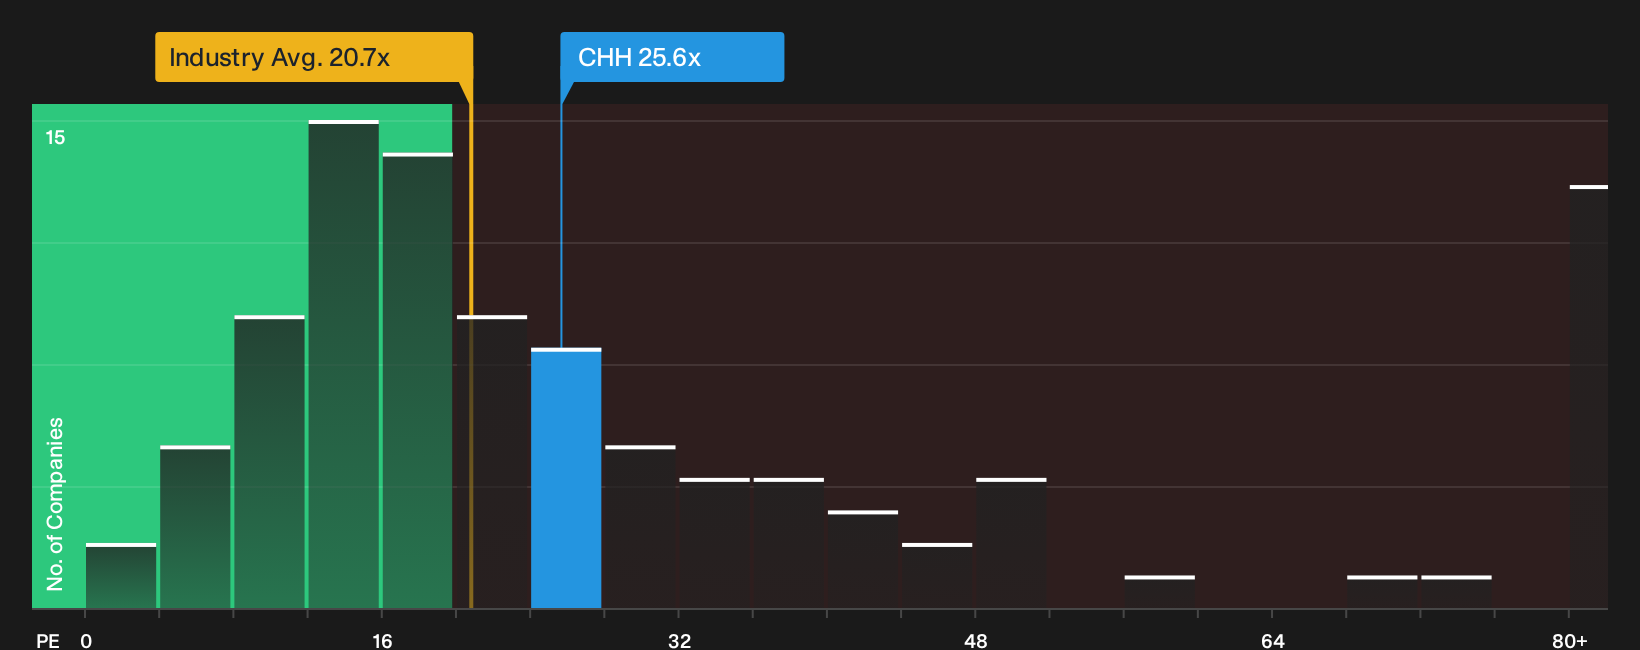
Analysts on Simply Wall St see Choice Hotels International as about 3.6% overvalued against their $114.60 fair value. The current P/E of 25.6x sits far below peers at 43.5x and only slightly above the US Hospitality industry on 20.7x, while the fair ratio sits at 24.7x.
That mix of a premium to the sector, a discount to peers, and only a small gap to the fair ratio points to limited valuation room in either direction if sentiment or earnings expectations shift quickly. Which side of that tight range do you want to be on when the next piece of news lands?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Choice Hotels International can feel noisy, so it may help to move quickly, review the key risks and potential upsides for yourself, and weigh the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Choice Hotels International?
If Choice Hotels International has sharpened your focus on valuation and momentum, do not stop here. Broadening your idea search now could matter more than any single ticker.
- Spot potential mispricings early by scanning companies that pair healthy fundamentals with attractive prices through the 32 high quality undervalued stocks.
- Stack your watchlist with businesses that combine income potential and sturdier payouts by reviewing the 6 dividend fortresses.
- Prioritize resilience by screening for companies with cleaner balance sheets and steadier fundamentals using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com