


EN
Does Earnings Beat Change The Bull Case For Sysco (SYY)?
- Sysco declared a quarterly cash dividend of $0.55 per share, payable on January 29, 2027, and confirmed Brandon Sewell as Executive Vice President and Chief Financial Officer following the first quarter of fiscal 2027, which showed higher sales, net income and earnings per share compared with the prior year period.
- The combination of rising first quarter earnings and the move from interim to permanent CFO gives investors fresh information on Sysco's profit engine, cost control and leadership continuity, while the dividend continues to return cash to shareholders.
- We will look at how Sysco's first quarter earnings and permanent CFO appointment reshape the existing AI and Restaurant Depot narrative.
Sysco Investment Narrative Recap
For Sysco, the central question is whether its scale, AI projects and the planned Restaurant Depot acquisition can support earnings growth while the balance sheet carries higher debt. The latest quarter showed higher sales and profit metrics, which supports that operating story in the near term. The key short term swing factor remains how smoothly Restaurant Depot is integrated and how those cash and carry economics appear in margins.
The biggest current risk is that higher leverage, equity issuance and a paused buyback could keep valuation under pressure if sentiment turns against debt funded deals. The fresh dividend affirmation and solid quarter do not remove that risk. They simply indicate that the business is still generating cash while taking on those integration and funding tasks.
The dividend declaration to pay US$0.55 per share on 29 January 2027 is the announcement that brings this news together. Sysco is planning to return roughly US$1b of dividends in fiscal 2027 according to the analyst consensus Narrative on Simply Wall St, at the same time it absorbs Restaurant Depot and funds AI projects. That combination puts execution under the spotlight.
For you as a shareholder or potential shareholder, the question is whether Sysco can maintain that payout while working leverage down from about 4.5x net to the 3.5x target within 24 months. Progress on AI driven cost savings, the mix toward local and noncommercial customers and the performance of the international segment all matter, because they influence how much free cash flow is left after servicing debt and funding the dividend.
Sysco's narrative includes analyst expectations for US$96.9b in revenue and US$2.9b in earnings by 2029. This implies forecast revenue growth of 4.7% per year and an earnings increase of about US$1.1b from current earnings of US$1.8b.
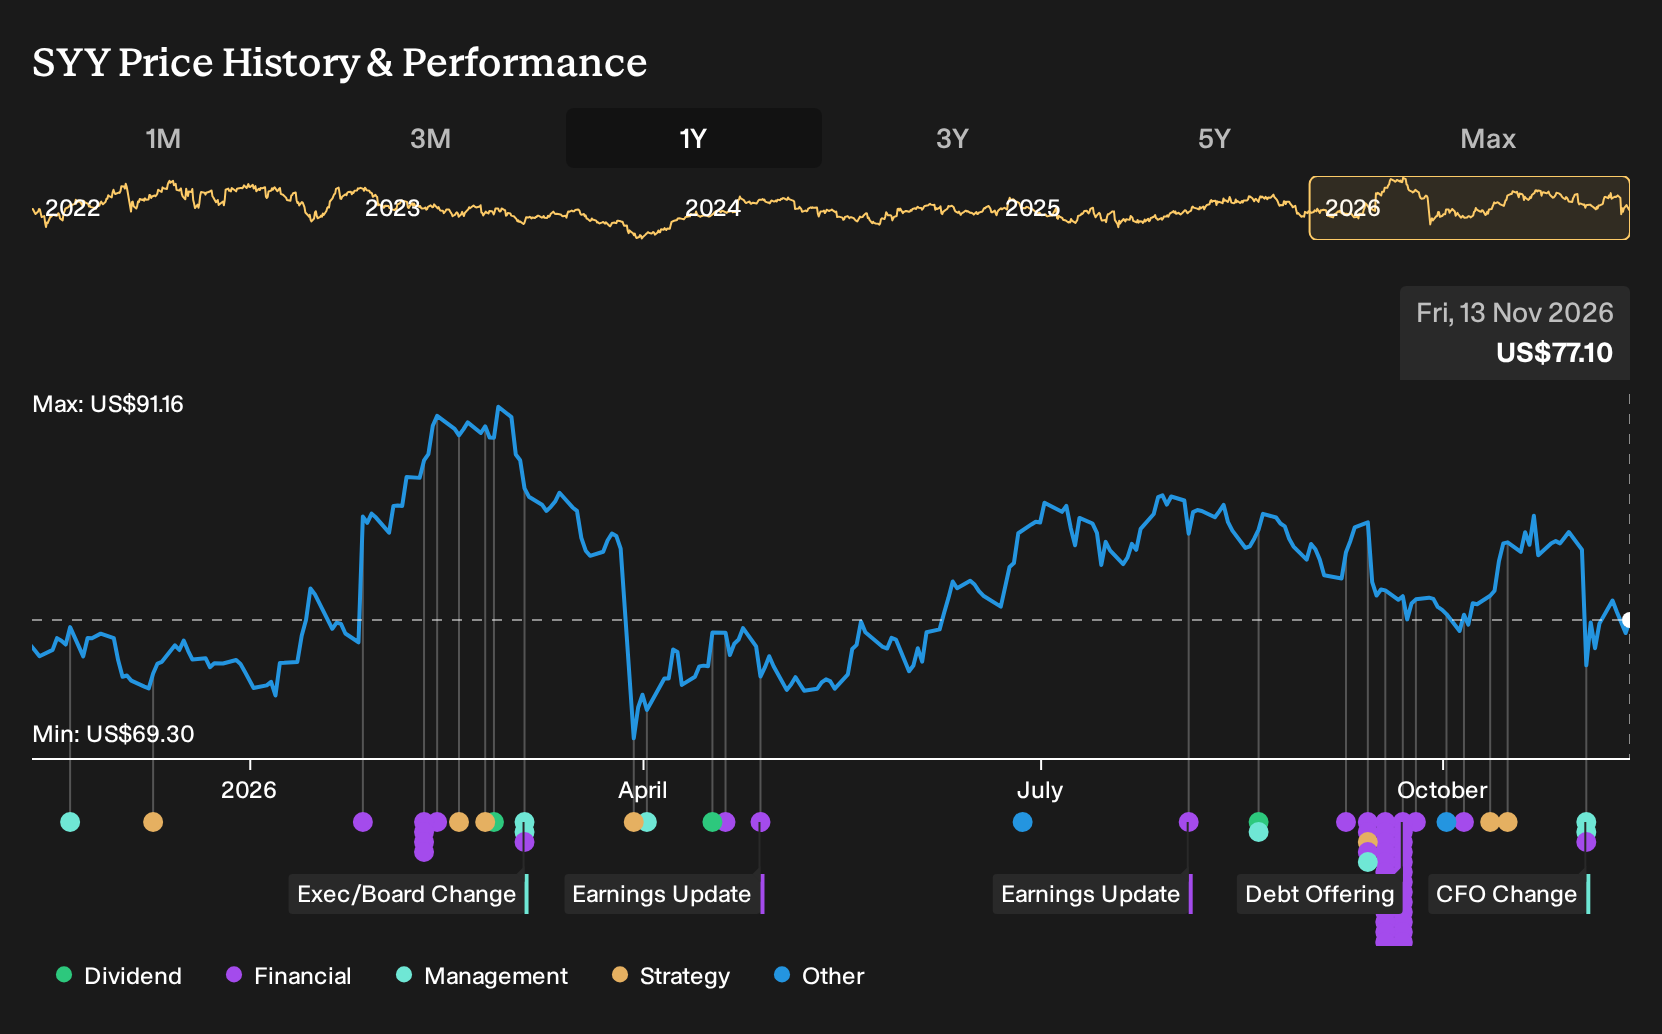
Uncover why Sysco's fair value indicates a 17% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$90 to US$177 per share, so you are seeing very different views on Sysco’s upside. Those opinions pre date the dividend affirmation and permanent CFO appointment, so reassess them in light of higher leverage, AI spending and the Restaurant Depot deal risk.
Explore 2 other Sysco fair value estimates, including one that suggests it could be worth just $90.31.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sysco research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sysco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sysco's overall financial health at a glance.
Looking for more investment ideas beyond Sysco?
Once you have a view on Sysco, it can help to compare it with other opportunities that line up with your own risk, income and quality preferences. The Simply Wall St Screener lets you filter for those traits quickly so you can spend more time weighing business quality and less time trawling through tickers.
- If you want potential mispricing with strong fundamentals as your anchor, start with 20 high quality undiscovered gems that pair solid balance sheets and earnings quality with less crowded ownership.
- If capital preservation sits high on your checklist, narrow the field to 31 resilient stocks with low risk scores that score well on stability, debt levels and earnings volatility.
- If you care most about resilient finances before anything else, sort candidates using the list of solid balance sheet and fundamentals (24 results) to focus on businesses with robust cash and manageable obligations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com