


EN
Sleep Well At Night With Hershey And Other Defensive Dividend Stocks
With the Fed tying future rate moves closely to inflation data and keeping policy tight while growth and jobs hold up, the market is rewarding resilience instead of excitement. Income investors now face a clear trade off between chasing rate sensitive stories and focusing on durable dividends that can weather bumpier data releases. This article walks through three high quality defensive dividend stocks exposed to this macro backdrop and what that could mean for your portfolio.
The three stocks below are only a sample of this income theme, and the full screen surfaced 7 more large caps with equally compelling defensive dividend stories that are not covered here. If you want to identify and analyze the highest conviction ideas from this broader universe, head straight to the High-Quality Defensive Dividend Stocks screener.
Del Monte (DMC)
Del Monte plugs neatly into the High-Quality Defensive Dividend Stocks theme because it sells everyday food staples, and the analyst consensus Narrative on Simply Wall St argues that the real story is how its fruit mix and prepared foods platform could reshape earnings power over time.
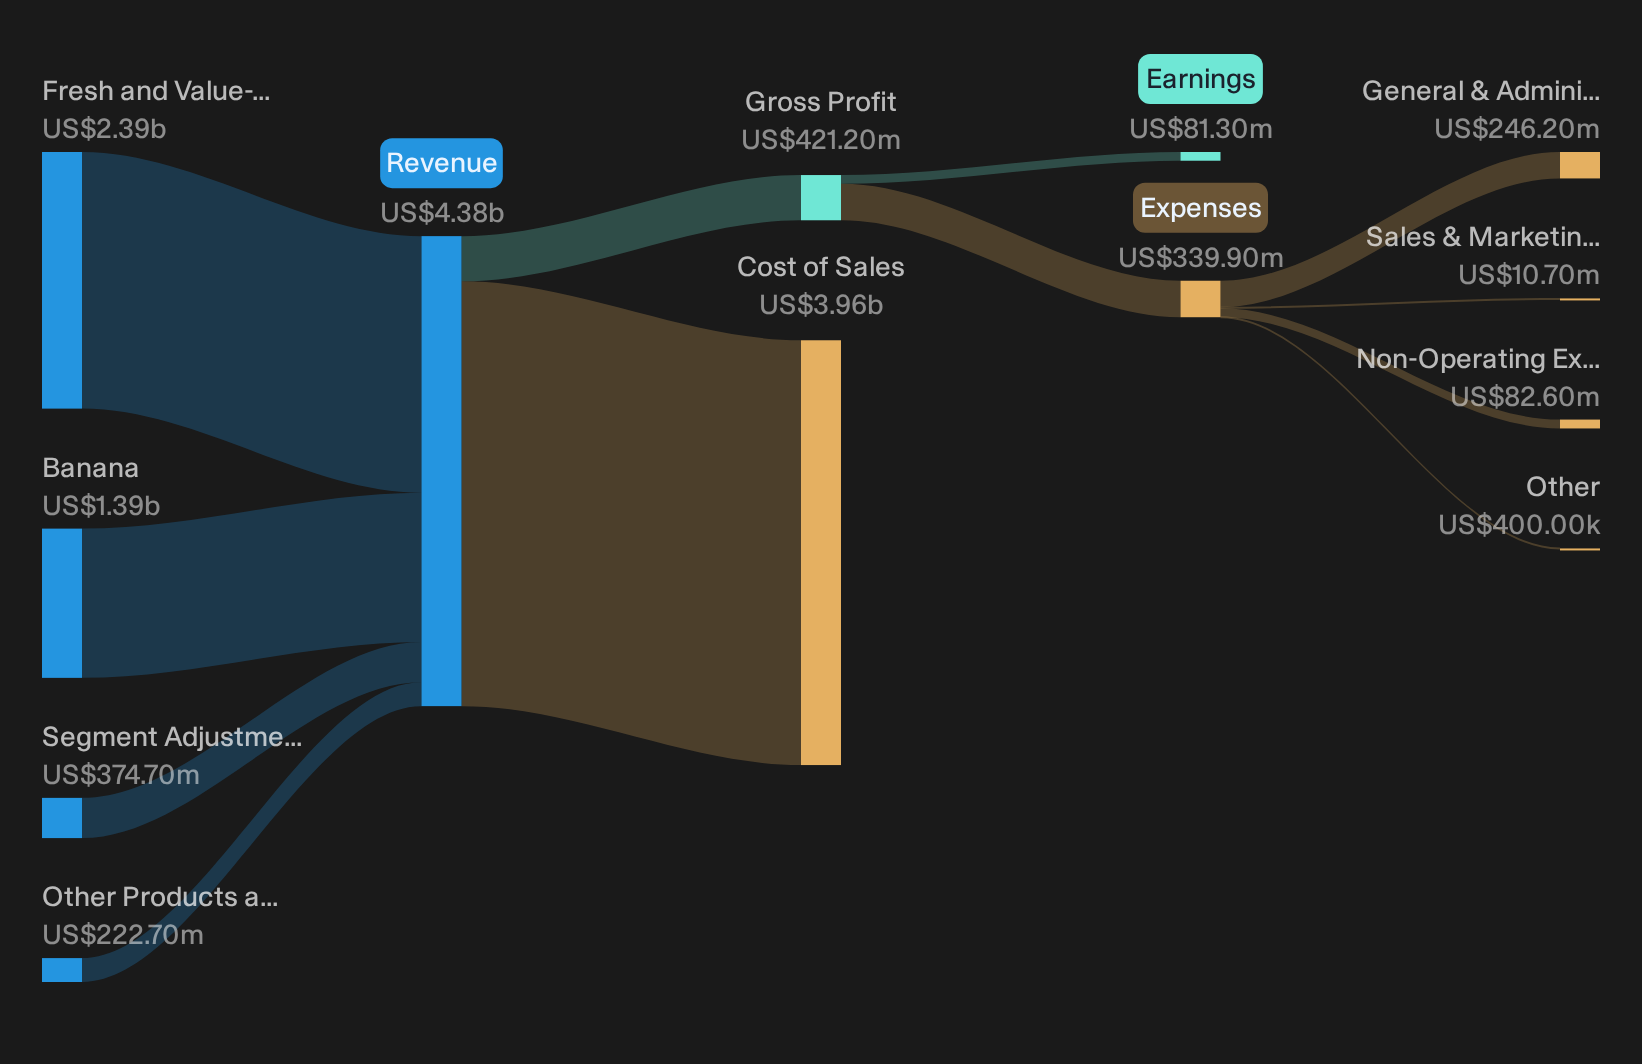
Del Monte runs a global fresh and prepared produce platform. Fresh and Value-Added Products generate about US$2.4b of revenue and Bananas generate about US$1.4b, alongside smaller Other Products and Services of roughly US$200 million, all backed by a market cap near US$1.3b.
"Reallocation of Costa Rica farmland away from higher cost banana farms into premium Del Monte Gold, Honeyglow and other pineapple varieties, alongside strong pricing and demand for these proprietary pineapples, points to a future volume and mix shift that could lift fresh segment gross margins and earnings quality."
What happens if a single pressure point in that broader mix evolution bends margins in a different direction than income investors expect?
If that margin story is what grabs you, read the full narrative for Del Monte to see how Del Monte's mix shift, capital choices and risks really interact.
Coca-Cola FEMSA. de (KOF)
Coca-Cola FEMSA. de brings the classic consumer staples dividend profile from Latin America into a US listing. This fits the High-Quality Defensive Dividend Stocks theme for investors who want recurring beverage demand while the Fed keeps policy closely tied to inflation data.
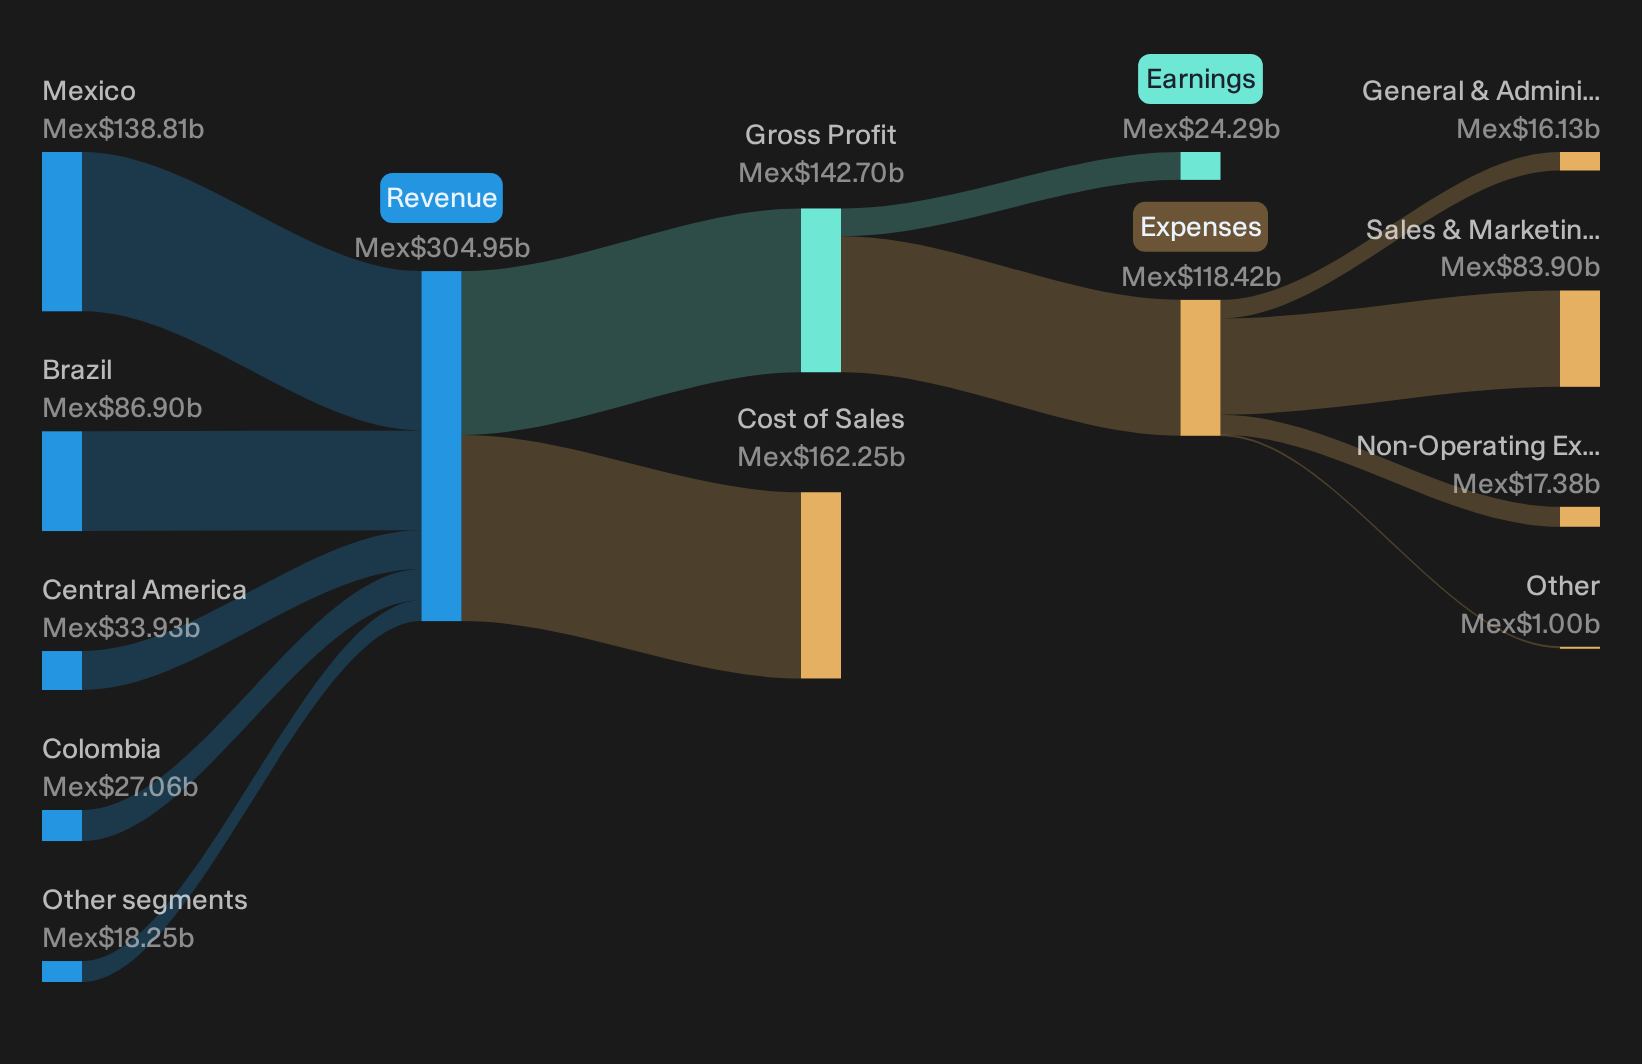
Coca-Cola FEMSA. de runs Coca-Cola branded and related beverage bottling, marketing, and distribution across Latin America. It generates about MX$304.9b from non alcoholic drinks and carries a market value near US$24.9b.
Coca-Cola FEMSA. de has caught attention in the bullish analyst Narrative on Simply Wall St as a bottler that tries to balance dividend income, rate sensitivity and emerging market risk with a more predictable beverage cash flow story.
"Further rollout of Coca-Cola FEMSA’s Juntos+ digital ordering and Juntos+ Advisor tools into additional territories beyond Mexico and Brazil could extend the uplift in purchase frequency, average ticket and cooler coverage already seen in these markets."
How much that dividend friendly profile holds up depends on one less obvious pressure that could quietly shift both margins and pricing power.
That quiet pressure point is exactly where the story gets interesting, and the full narrative for Coca-Cola FEMSA. de shows how Coca-Cola FEMSA. de could see pricing power and cash flows decoupling expectations.
Hershey (HSY)
Hershey fits the High-Quality Defensive Dividend Stocks theme as a consumer staples heavyweight. According to Esteban, an investor in the Simply Wall St Community who wrote about the business, the real interest is how a resilient cash engine behaves when rate policy keeps investors focused on stable income.
"The 2025 cocoa shock, a ~60% GAAP EPS collapse driven largely by non-cash hedge mark-to-market, obscured an underlying cash engine that remained intact."
The next chapter for Hershey’s dividends and pricing power hinges on how one quiet margin pressure plays out against that cash engine.
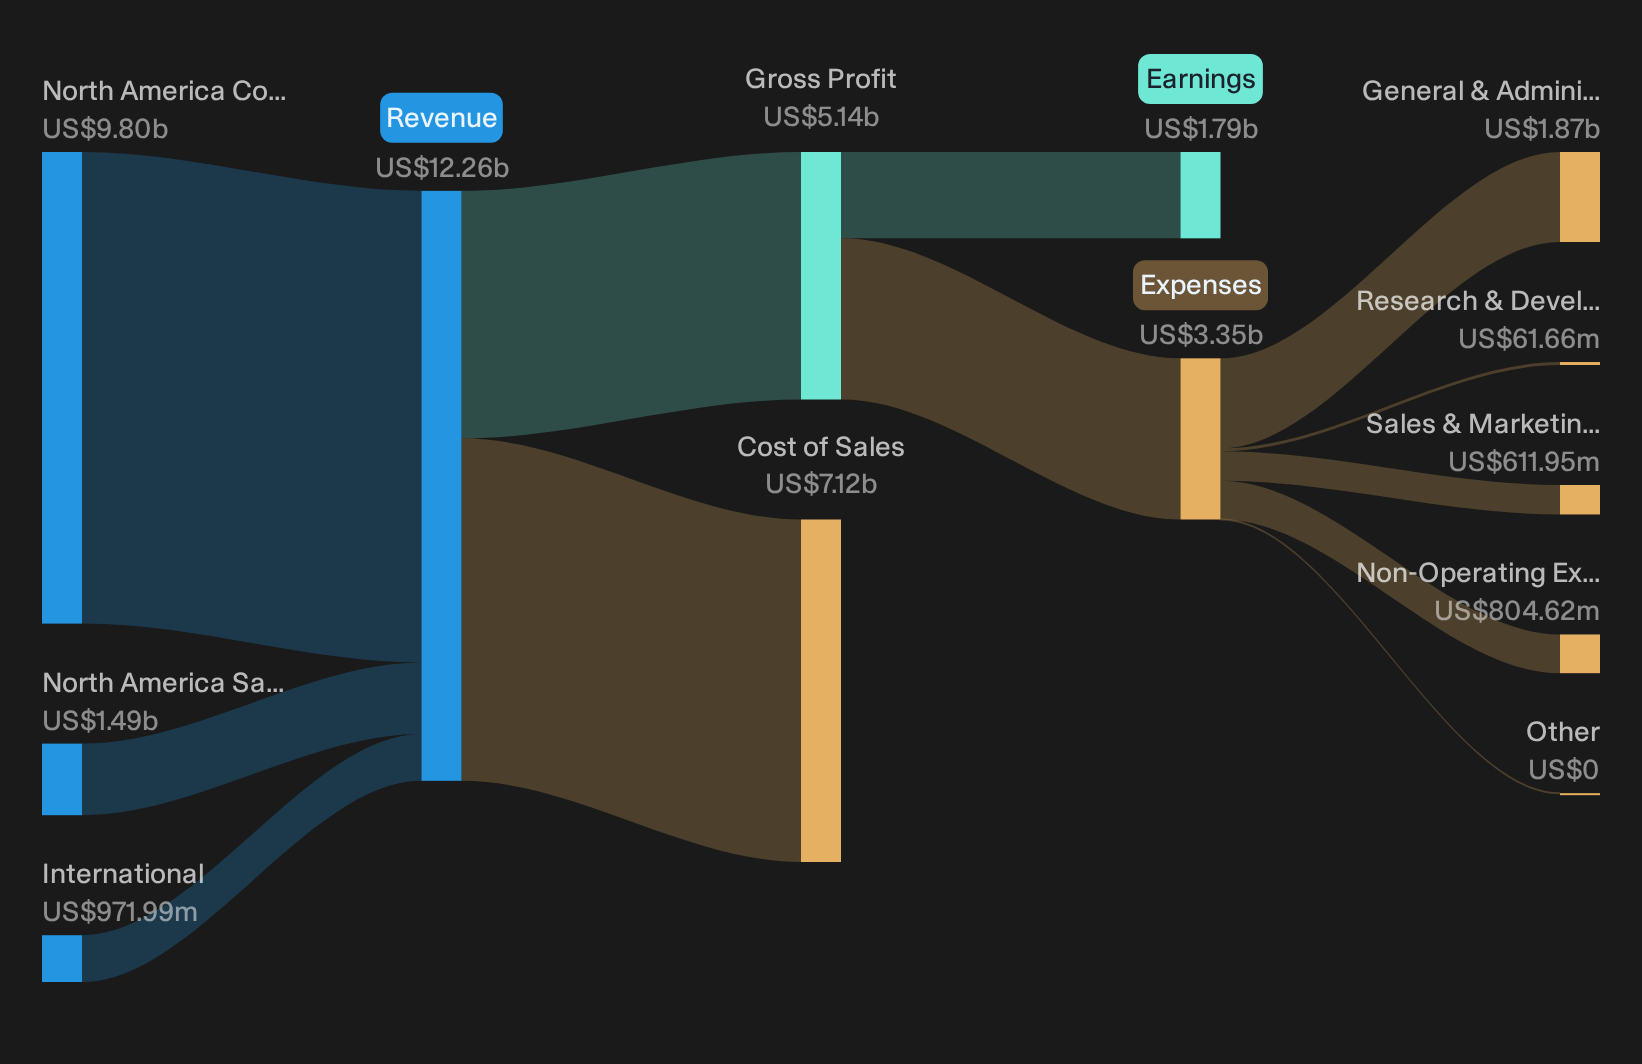
Hershey manufactures confectionery products, salty snacks and pantry items across brands like Hershey’s, Reese’s, Kit Kat and SkinnyPop. North America Confectionery generates about US$9.8b of revenue, North America Salty Snacks about US$1.5b and International about US$1.0b, supporting a roughly US$34.8b market value.
That margin pressure is only half the picture, and the full narrative for Hershey lays out how Hershey’s cash engine, cocoa volatility, and dividend ambitions could be quietly decoupling expectations.
Seeking Alternatives Before Momentum Flies
Fresh ideas move first. Once momentum builds, entry points can vanish while prices keep flying. Scan new watchlist candidates under the radar for now and get in early.
- Spot income opportunities that aim to stay standing while others wobble by running a curated set of higher yield 6 dividend fortresses before the crowd piles in.
- Track capital flowing into real-world infrastructure and grid upgrades by focusing on 43 power grid technology and infrastructure stocks while policy support and spending trends still matter most.
- Position around the next leg of computing progress by using 25 quantum computing stocks while these potential breakout stories are still dropping fresh filings and staying mostly overlooked.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com