


EN
How Investors May Respond To CoreCivic (CXW) Strong Quarter Lower Outlook
- CoreCivic reported third quarter 2026 sales of US$744.09 million and net income of US$1.344b, with diluted EPS from continuing operations of US$14.49, compared to US$580.44 million in sales, US$26.31 million in net income and US$0.24 in diluted EPS a year earlier.
- The company paired these strong quarterly figures with slightly lower full year 2026 guidance, trimming expected diluted EPS to US$15.42 to US$15.48 and net income to US$1.461b to US$1.467b. This highlights management's caution regarding how recent operating momentum will translate across the full year.
- Next is a look at how CoreCivic's sharp third quarter profit jump and modestly lower full year guidance could reshape the investment narrative.
Compare CoreCivic's results driven story with other companies showing strong fundamentals and momentum in a curated list of 20 high quality undiscovered gems.
CoreCivic Investment Narrative Recap
To own CoreCivic, you need to be comfortable with a story built on federal detention demand, active facility use and disciplined capital allocation. The analyst consensus Narrative on Simply Wall St leans on that backdrop. The huge third quarter profit and nine month net income of US$1.419b show what full facilities and capital recycling can look like, while the slightly trimmed 2026 guidance signals management is treating that spike as unusual.
In the short term, the key catalyst is how consistently CoreCivic can convert current federal usage into steady operating earnings rather than one off gains. The biggest risk is still policy and budget exposure, especially to ICE contracts and broader federal funding priorities, which could pressure volumes or pricing if conditions tighten.
The full year 2026 guidance update sits at the center of this story. CoreCivic now expects diluted EPS of US$15.42 to US$15.48 and net income of US$1.461b to US$1.467b, trimmed from earlier ranges. That adjustment frames the third quarter surge as partly driven by items that are not expected to repeat at the same level.
For you as an investor, the guidance range is a practical reference point when thinking about catalysts such as detention counts, facility sales and share repurchases. It also highlights risk. High reported EPS, a very low P/E and a large portion of earnings coming from non cash sources mean you need to focus on underlying cash generation and contract durability, not just headline profit.
CoreCivic's narrative projects US$3.4b revenue and US$516.8 million earnings by 2029, which assumes revenue grows at 11.6% per year and earnings rise by about US$388.9 million from US$127.9 million today.
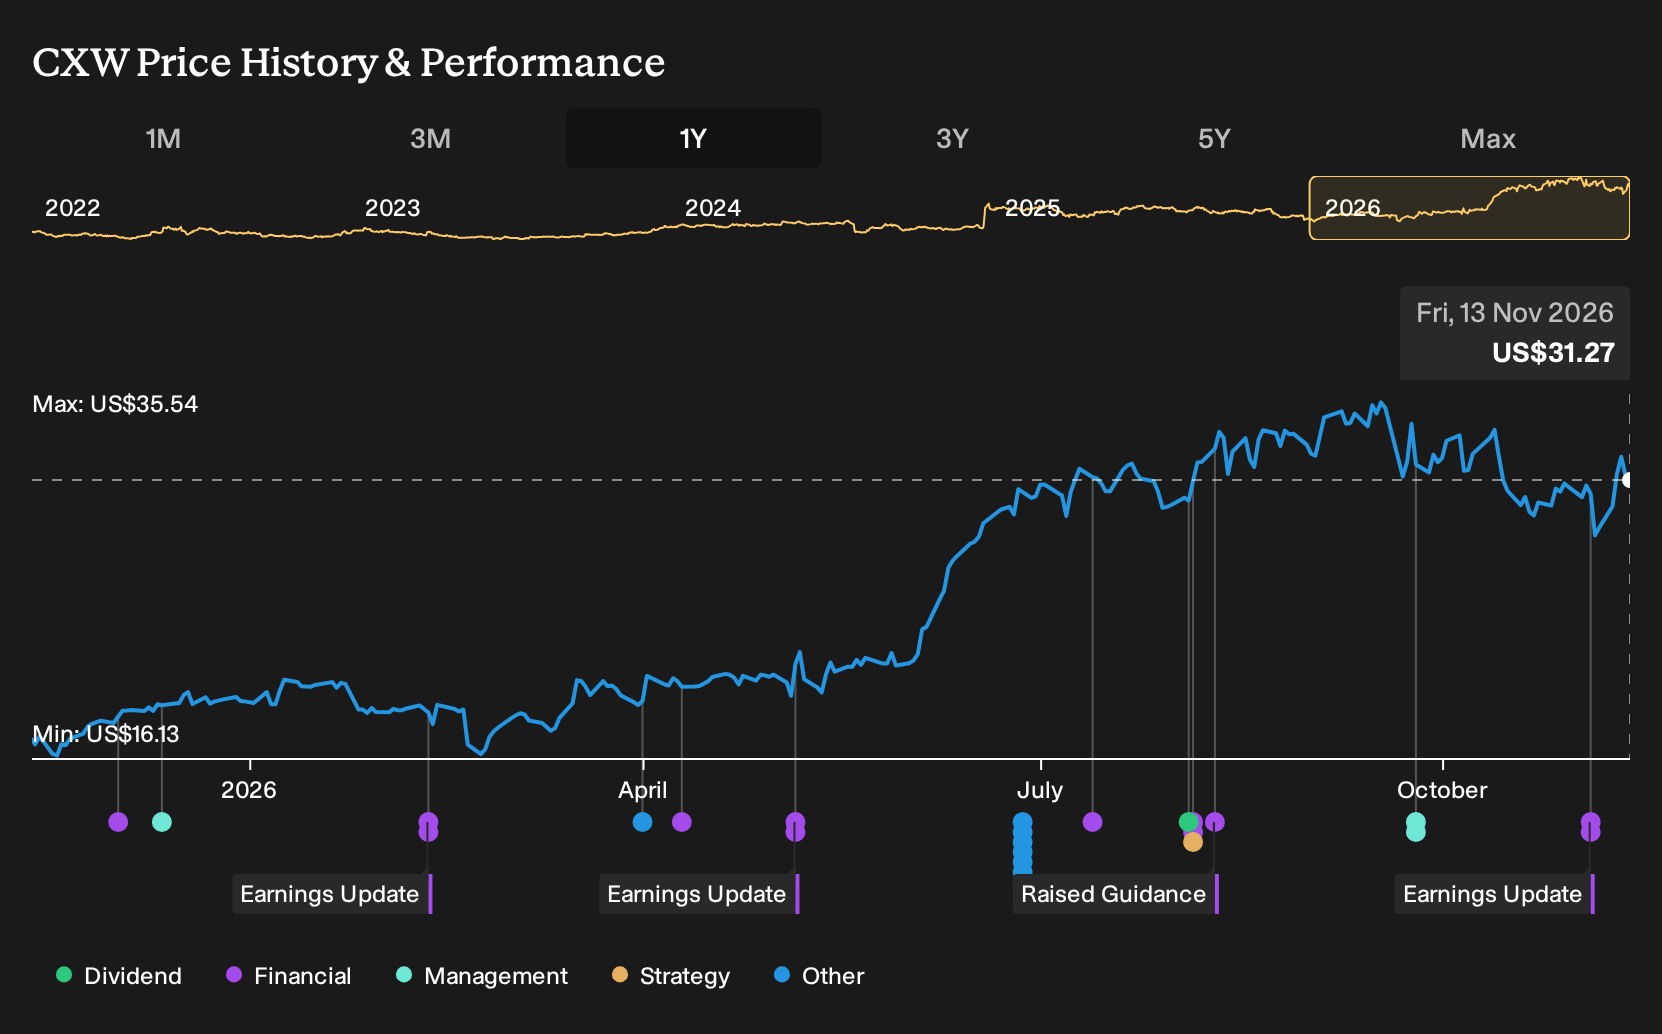
Uncover how CoreCivic's fair value indicates a 34% potential upside to its current price that could narrow quickly as CoreCivic's story spreads.
Exploring Other Perspectives
One alternate view on CoreCivic leans hard into capital recycling as the key catalyst. Before this earnings release, the most optimistic analysts were already assuming revenue of about US$3.5b and earnings of US$245.1 million by 2029. That camp sees buybacks and facility sales as underappreciated, and this latest guidance tweak may force every narrative back to the drawing board.
Explore 2 other CoreCivic fair value estimates, including one that suggests potential upside of as much as 35% from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CoreCivic research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for CoreCivic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CoreCivic's overall financial health at a glance.
Looking For More Investment Ideas Beyond CoreCivic?
If CoreCivic's story has sharpened your thinking and you want to test your thesis building on a wider set of opportunities, the Simply Wall St Screener can help you quickly surface other companies that fit different risk, income and quality profiles.
- For investors who care about steady income and resilience, check companies that look like potential 6 dividend fortresses built around sizeable yields.
- If capital preservation and balance sheet strength matter most to you, start with a list of solid balance sheet and fundamentals (24 results) and filter for businesses that can better handle financial pressure.
- When you want ideas that are not yet widely followed but still show strong fundamentals, scan through a 20 high quality undiscovered gems and see which stories deserve a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com