


EN
Jabil (JBL) Shares Moved, So What Is Driving Attention Now?
Jabil (JBL) has moved back into focus after fresh research highlighted rising cash flows and higher fiscal 2027 earnings estimates, which are tied closely to management’s optimistic projections for AI infrastructure and several other key end markets.
Recent trading has been choppy for Jabil, with the share price down 29.98% over the past 90 days and 13.49% over 30 days, even after a 6.34% 7 day share price gain and fresh enthusiasm around AI driven earnings.
That disconnect between the weaker recent share price return and a 26.09% 1 year total shareholder return, plus a 314.87% total shareholder return over five years, suggests long term holders have still been rewarded while short term sentiment adjusts to the new guidance and risk profile.
Scan beyond Jabil and spot other AI driven hardware and infrastructure plays using our hand picked 53 AI infrastructure stocks to see how the theme is spreading across the market.
Bulls view Jabil as a cash-rich AI infrastructure beneficiary, while bears see a cyclical hardware contractor that has run too far ahead of itself. Which side does the current valuation actually support?
Most Popular Narrative: 40% Undervalued
Jabil's last close at $254.25 sits well below the analyst consensus Narrative fair value of $425, which frames the current AI story through a discounted cash flow lens using a 9.15% discount rate from the analyst consensus Narrative on Simply Wall St.
The asset light model, with net capex of about 1.3% of fiscal 2026 revenue and planned capex of 1.5% to 2% of revenue, alongside adjusted free cash flow of more than US$1.5b and a plan to return at least 80% of that over time, gives Jabil room to continue sizeable buybacks that can support earnings per share even if headline revenue growth moderates.
See why 39 investors see Jabil as 40% undervalued.
Result: Fair Value of $425 (UNDERVALUED)
Still, if component shortages linger or inventories remain above Jabil’s 55 to 60 day target, the AI heavy Intelligent Infrastructure thesis could quickly look stretched.
Find out about the key risks to this Jabil narrative.
Another View: What Jabil’s P/E Is Really Saying
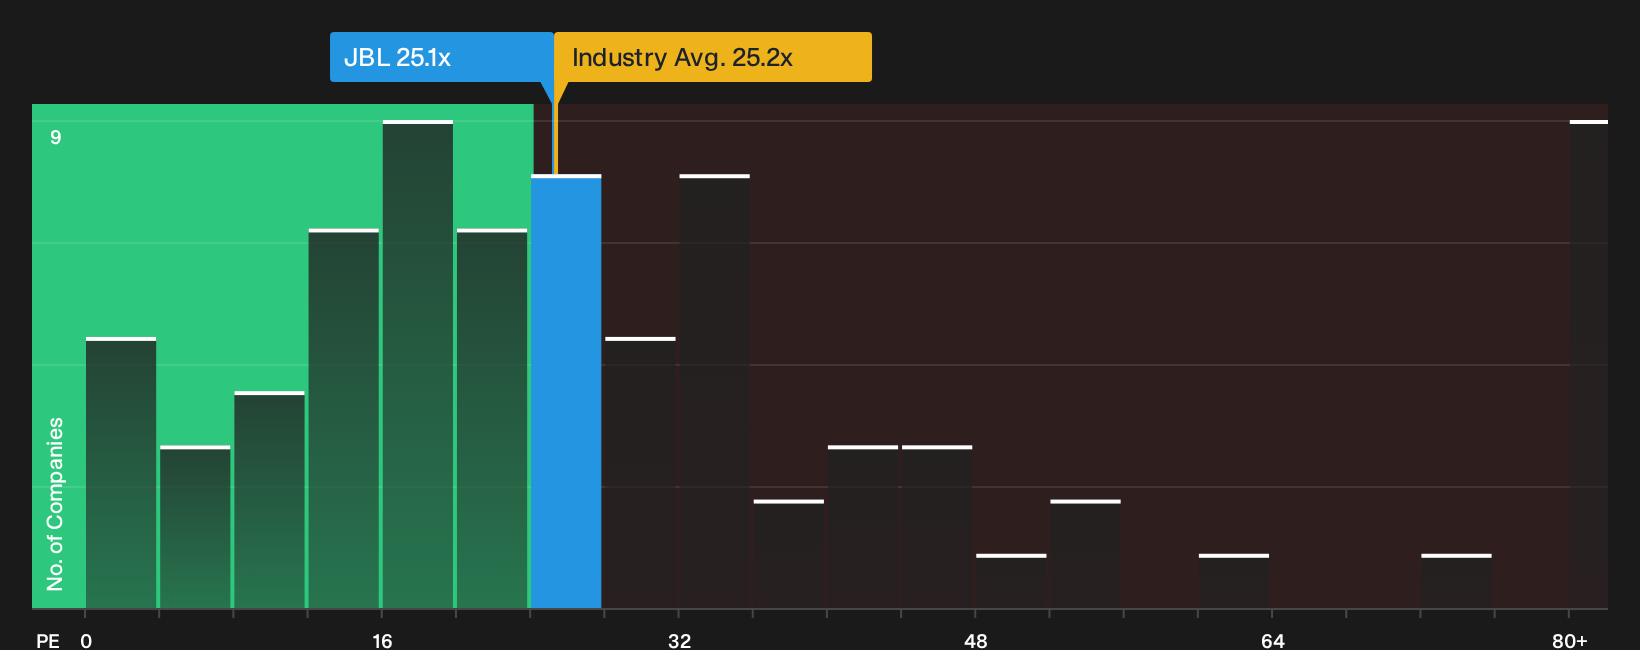
Jabil may look inexpensive on cash flow models, yet the earnings multiple tells a more cautious story. The stock trades on a P/E of 25.1x, which is slightly higher than peer averages at 23.1x, even though the fair ratio sits higher again at 33.6x.
That mix creates an unusual setup. Pricing is richer than similar stocks, but still below where the fair ratio suggests the market could move over time. Investors need to decide whether that gap feels like a margin of safety or a warning about expectations already built into the earnings line.
To stress test that view against hard numbers and see how the current earnings multiple stacks up under different scenarios, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like this rarely stay unresolved for long, so it can be helpful to look at the underlying data yourself and decide where you stand. To weigh those concerns against the upside case in one place, review the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Jabil?
Do not stop your research with Jabil alone. Broaden your watchlist with focused screens that surface very different types of opportunities before the crowd pays attention.
- Target potential mispricing by scanning a curated 32 high quality undervalued stocks that filters for quality fundamentals and valuations that may not fully reflect underlying business strength.
- Strengthen your defense by reviewing a 31 resilient stocks with low risk scores that highlights businesses with more resilient profiles and lower overall risk scores.
- Spot future favourites early by working through a 20 high quality undiscovered gems that concentrates on under-followed companies with solid financial traits.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com