


EN
Cheesecake Factory (CAKE) Draws Fresh Earnings Optimism, Is It Still Below Fair Value?
Cheesecake Factory (CAKE) is back in focus after research updates pointed to earnings growth expected to run ahead of the wider restaurant industry, with fresh upward EPS revisions supporting the recent move in market value.
Recent trading tells a story of a stock that has run hard and is now pausing. Cheesecake Factory’s 1 day share price return of 2.74% and 7 day gain of 2.20% come after a 30 day share price pullback of 3.31% and a 90 day decline of 3.77%. Yet the year to date share price return is 106.61% and the 1 year total shareholder return is 146.48%, signalling longer term momentum even as some holders lock in gains following a long holding period and a fund exit.
Scan for other restaurant stocks where earnings momentum and revisions look just as strong as Cheesecake Factory by starting with our hand picked 20 high quality undiscovered gems in this corner of the market.
After a 1 year return of 146.48% and a valuation now sitting above the average analyst target, Cheesecake Factory is no longer an obvious bargain. Does the current risk reward still lean toward new buyers, or favour patience?
Most Popular Narrative: 29% Undervalued
Cheesecake Factory last closed at $109.11, while the most followed narrative on Simply Wall St points to a fair value of about $154, indicating a sizeable gap between the current share price and that narrative estimate.
According to RedCandleRx, an investor in the Simply Wall St Community who wrote the narrative on Cheesecake Factory, the long term appeal is less about the dessert menu and more about how its concept pipeline could reshape the growth profile of the whole group.
"The Cheesecake Factory prints cash day in and day out, pays a rock solid dividend, and gives money back to shareholders. That part is real. But the part that actually excites me is this: I think CAKE has a legitimate shot at becoming a true growth company, and almost nobody is pricing it that way."
See why 36 investors see Cheesecake Factory as 29% undervalued.
Result: Fair Value of $154 (UNDERVALUED)
Still, this storyline can unravel if unit economics for newer concepts disappoint, or if higher build costs erode returns on Cheesecake Factory’s planned expansion pipeline.
Find out about the key risks to this Cheesecake Factory narrative.
Another View: Cheesecake Factory On Earnings Multiples
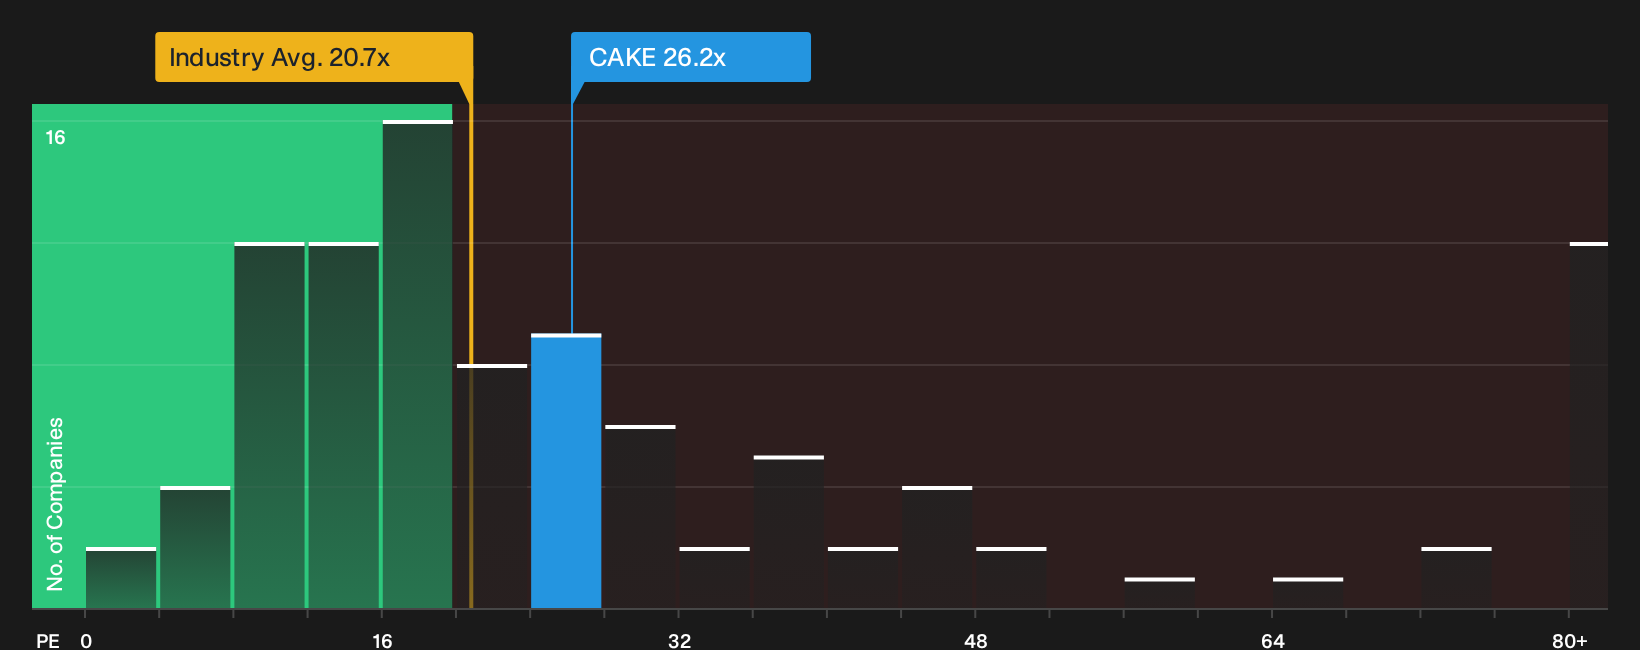
That community fair value of $154 paints Cheesecake Factory as 29% undervalued. The preferred earnings multiple tells a different story. At a P/E of 26.2x versus a fair ratio of 19x, the shares look expensive on this metric.
There is a split in the comparison set. Against direct US hospitality peers on 20.7x P/E, Cheesecake Factory trades on a richer valuation. Against a wider peer group on 53.8x, it looks cheaper. For investors, the question is whether the market leans toward the tighter industry number or something closer to the broader set from here.
To see how that gap might close in either direction, and what the current P/E implies in practice, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Cheesecake Factory story today. If you want to move fast and decide where you stand, weigh up the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Cheesecake Factory?
Cheesecake Factory might have your attention right now, but the market will not wait while you weigh options. Line up a few more ideas so you always have a watchlist ready when prices move.
- Target resilient potential by scanning 31 resilient stocks with low risk scores that aim to balance opportunity with tighter risk controls.
- Zero in on quality at a discount by reviewing the 32 high quality undervalued stocks that match strong fundamentals with appealing valuations.
- Build a steadier income stream by checking the 6 dividend fortresses that focus on higher yielding payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com