


EN
Alcon (SWX:ALC) Drew Fresh Investor Interest, Is The Undervalued Case Strong Enough?
Why Alcon Stock Is Back On Investors’ Radar
Alcon (SWX:ALC) has landed back in focus after its Q3 2026 earnings report, a tighter full year sales outlook, fresh intraocular lens approvals, and the Neurotech Pharmaceuticals acquisition.
Recent trading tells a mixed story. Alcon’s share price has climbed about 15% over the past month, helped by the Q3 2026 update, tighter full year sales outlook, ongoing buybacks and fresh product approvals. Yet total shareholder returns over one and five years remain slightly negative, hinting that long term confidence is still rebuilding rather than firmly established.
Compare Alcon’s renewed momentum with a curated group of eye care and medical leaders by scanning 123 healthcare AI stocks that are riding similar product and earnings catalysts.
Alcon’s recent climb could reflect investors finally focusing on new lenses, stronger Surgical and Vision Care trends, and Neurotech, or it could just be a sentiment reset. The valuation numbers now need to do the talking.
Most Popular Narrative: 18% Undervalued
Alcon last closed at CHF61.36, while the analyst consensus Narrative on Simply Wall St points to a fair value of about CHF74.71 using a 4.52% discount rate. That gap sits at the center of a thesis built on premium eye care products, cost savings and newer therapy areas rather than just broad demographic tailwinds.
The multiyear cost efficiency program that targets about US$100 million in annual run rate savings, along with tariff relief and manufacturing efficiencies, is designed to support 90 to 190 basis points of core operating margin expansion in 2026. It can contribute to higher future earnings even if top line growth stays within current guidance ranges.
See why 28 investors see Alcon as 18% undervalued.
Result: Fair Value of CHF74.71 (UNDERVALUED)
Still, the Alcon story can unravel if cataract procedure bottlenecks drag on or if key R&D bets fail and the premium product mix stalls.
Find out about the key risks to this Alcon narrative.
Another View: What Alcon’s P/E Is Telling You
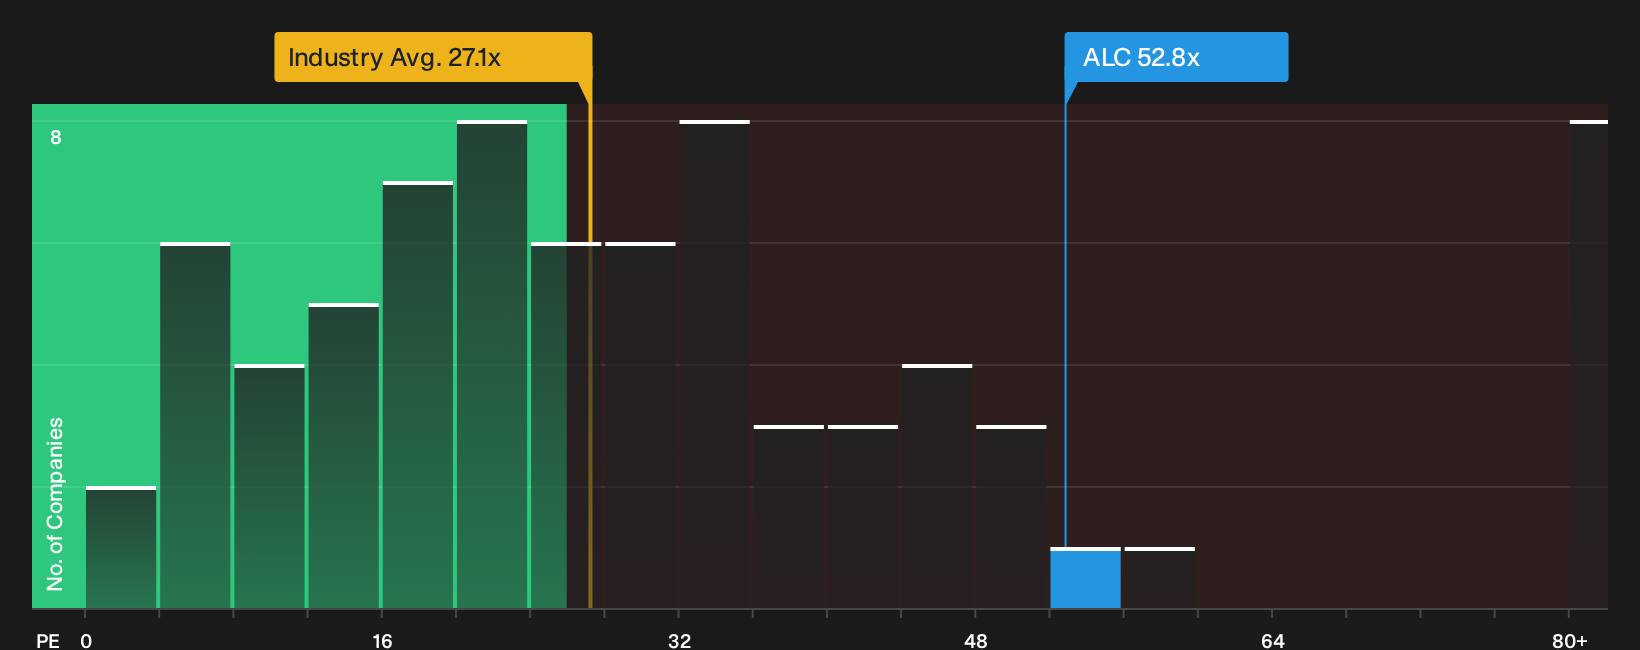
Alcon might look inexpensive compared with a CHF74.71 fair value. However, the market is paying a relatively high 52.8x P/E for the shares. That is well above the European medical equipment average of 27.6x and a fair ratio of 43.5x, which may indicate valuation risk if sentiment or forecasts change.
To see how this pricing gap fits with the broader earnings story, take a closer look at our valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Alcon feels familiar, act while the data is fresh and weigh both sides through the 3 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Alcon?
If Alcon has sharpened your focus on quality opportunities, do not stop here. Broaden your watchlist now and give yourself more options tomorrow.
- Target steadier potential outcomes by reviewing a curated pool of resilient companies through the 210 resilient stocks with low risk scores.
- Hunt for quality at a reasonable price by scanning the 198 high quality undervalued stocks that may trade below their assessed worth with solid fundamentals behind them.
- Build a watchlist around balance sheet strength by filtering for businesses in the list of solid balance sheet and fundamentals (198 results) that can better handle shocks and opportunities.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com